



AI for Edge Devices Market to Expand at 23.5% CAGR — PW Consulting Insight (2026–2032)

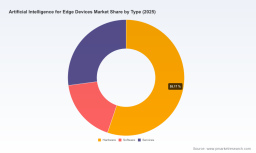
Artificial Intelligence for Edge Devices Market — Strategic Preview for 2026 Decision-Makers
As enterprises prepare capital allocation, product roadmaps, and regulatory compliance strategies for 2026, the edge AI landscape demands a different kind of market intelligence: one that couples robust macro forecasts with executable playbooks and vendor-level nuance. This PW Consulting briefing introduces the firm’s latest market research on Artificial Intelligence for Edge Devices. It highlights the strategic takeaways that should shape boardroom decisions, while preserving the granular segment-level intelligence for the full report where practitioners can access detailed spreadsheets, vendor scorecards, and scenario models.
Artificial Intelligence for Edge Devices Market
Market snapshot: scale, trajectory, and concentration
Edge AI is moving from niche deployments to a mainstream infrastructure layer. Our base-year analysis (2025) positions the global market at approximately USD 11.8 Billion, with a compound annual growth rate (CAGR) of 23.5% through the forecast horizon (2026–2032). By 2032, the market trajectory points to multi‑dozen billion scale, reflecting the cumulative effect of on-device inference adoption across mobile, industrial, automotive, healthcare, and consumer segments.
Artificial Intelligence for Edge Devices Market
Competitive dynamics are moderately fragmented: the top three players account for roughly one-third of the market, while the top five capture just over two-fifths. That concentration profile creates room for specialist challengers and systems integrators to capture differentiated value through software, services, and verticalized solutions.
Artificial Intelligence for Edge Devices Market
Why this matters to 2026 enterprise strategy
- CapEx and procurement timing: With rapid compound growth, procurement windows for edge compute hardware and integrated platforms will compress. Enterprises that delay standardizing architectures risk higher migration and integration costs as vendors accelerate product refresh cycles and raise the bar for security and compliance.
- Vendor selection as strategic choice: Edge AI suppliers are not interchangeable parts. Hardware optimizations, developer ecosystems, and software toolchains materially affect time‑to‑value for pilots and scale-ups. Selecting a partner is simultaneously a technology and a go‑to‑market decision.
- Regulatory and sustainability externalities: New requirements around energy reporting, data sovereignty, and device certification will alter total cost of ownership models. Forward-looking procurement must bake in compliance pathways, not retrofits.
Dynamics shaping the edge AI market in 2026
- Energy and performance tradeoffs: Power consumption remains the central engineering constraint for edge compute. Innovations that enable DRAM‑less architectures and aggressive power reduction are altering BOM and operational models. For technology buyers, this translates into new ROI horizons: lower energy draw can reduce device-level operating costs and enable deployments where previously infeasible.
- Standards and certification: Governments and standards bodies are converging on frameworks for transparency and interoperability. New guidance for evaluating AI standards and certification catalogs for edge systems are emerging as de facto purchasing criteria for enterprise procurement teams.
- Policy-driven demand flows: Public financing and strategic assistance programs are beginning to direct capital toward secure, resilient edge solutions in geopolitically sensitive regions. This creates pockets of accelerated demand for vetted platforms that meet security and compliance thresholds.
- Platformization vs. specialization: The market is bifurcating into broad platform providers that offer verticalized suites and specialized accelerators optimized for particular inference workloads (vision, audio, low-latency control). Both plays can be profitable—what matters is alignment between workload economics and partner capabilities.
Technology and vendor landscape — how to read the field
Leading semiconductor and systems companies each bring distinct value propositions that influence enterprise architectures. Market leaders offer high-performance platforms and robust software ecosystems, enabling use cases from robotics to automotive. Mobile and consumer device incumbents embed AI capabilities at device scale, while a cohort of startups and semiconductor specialists focuses on ultra‑low power accelerators and MLSoCs designed for embedded vision and inference.
- High-performance platform providers: Companies delivering integrated edge platforms for robotics, industrial automation, and autonomous systems emphasize throughput, developer tooling, and ecosystem partnerships. Their products are favored in use cases that require sustained inference performance and complex model support.
- Mobile and consumer AI suppliers: Providers that embed on‑device AI into phones and personal devices prioritize energy‑efficient designs and tightly integrated software stacks to deliver end‑user capabilities with minimal latency.
- Specialist accelerators and MLSoCs: Emerging players focus on power-efficient, low-footprint accelerators tailored to vision and inferencing tasks where BOM and thermal constraints dominate design decisions.
Because vendor selection is consequential, the full report provides a practical competitor matrix and vendor profiles that evaluate partner readiness across performance, power, software ecosystem, security posture, and go‑to‑market alignment.
Recent developments that will matter in 2026
- Public funding initiatives targeting secure edge-enabled devices are mobilizing procurement budgets and creating new buyers—especially where national security and resilience are core requirements.
- Product launches and expanded developer ecosystems from major chipset vendors have shortened the prototype-to-deployment pathway, reducing integration friction for enterprises that adopt reference stacks.
- Strategic partnerships between systems integrators and chipset providers are producing compliant, certified edge platforms tailored for regulated markets—accelerating enterprise confidence in rollouts.
These dynamics combine to form a market environment where technology performance and policy compliance jointly determine supplier attractiveness. Organizations that evaluate both axes simultaneously will have a decisive advantage.
Where enterprise value will be captured
- Software and services around hardware — Integration, lifecycle management, secure update mechanisms, and model management are sustainable revenue pools that yield higher margins than commodity hardware. For buyers, service-level agreements and remote management capabilities are critical differentiators.
- Verticalized solutions — Industry-specific stacks (industrial vision, edge-enabled healthcare monitoring, automotive ADAS) convert throughput into measurable business outcomes. Successful vendors combine domain expertise with optimized inference stacks.
- Operational efficiency — Energy-aware architectures and optimized inference pipelines reduce operational expenditure in distributed deployments, affecting TCO calculations for large-scale pilots and global rollouts.
What the PW Consulting report delivers (practical components)
PW Consulting’s full study is designed for executives who need to translate market intelligence into executable decisions. The report contains:
- Detailed market sizing and forecast methodology (base year 2025; forecast period 2026–2032) with scenario analyses tailored for conservative, baseline, and aggressive adoption cases.
- Vendor benchmarking across technology, software ecosystem, security posture, developer support, and vertical go‑to‑market readiness.
- Use-case value calculators and ROI templates that model real-world deployments (pilot-to-scale economics, CapEx/Opex tradeoffs, and energy impact assessments).
- Procurement and integration playbooks: architecture decision trees, procurement RFP templates, vendor evaluation scorecards, and deployment checklists to accelerate safe, compliant rollouts.
- Regulatory mapping and compliance pathways aligned to current standards and guidance, including energy reporting expectations and certification resources applicable to distributed edge systems.
- M&A and partnership tracker highlighting strategic moves, financing, and alliances that shift supplier landscapes and accelerate access to capabilities.
How to use this intelligence in 2026
- Align procurement with compliance roadmaps: Require suppliers to demonstrate compliance readiness and productized pathways to meet energy and transparency obligations—doing this during vendor selection minimizes retrofit costs later.
- Prioritize pilot-to-scale economics: Use the report’s ROI templates to stress-test business cases across geography and edge topology. Pilot success metrics must map to scaled operational models, not vanity metrics.
- Design modular architectures: Build on interoperable stacks and open toolchains to avoid lock-in as silicon and software rapidly iterate. Modularization reduces migration cost and facilitates selective upgrades.
- Allocate budget for lifecycle services: Expect most value capture to shift into software, monitoring, and managed services. Budgeting for these capabilities is essential for sustained performance and security.
Final counsel — what 2026 leaders should do today
Edge AI is no longer an experimental add‑on—it's an infrastructure inflection. Boards and technology leaders must move from exploratory pilots to disciplined portfolio management: standardize reference architectures, codify compliance requirements, and select partners that align with long-term operational and governance objectives. The macro growth trajectory is compelling, but the devil is in implementation detail: energy constraints, standards adherence, and vendor ecosystems will determine who wins the operational and financial upside.
This preview outlines strategic priorities and the practical intelligence needed to act in 2026. For the granular segmentation, regional and application breakdowns, vendor scorecards, and model-level forecasts that underpin these recommendations, consult the full PW Consulting Artificial Intelligence for Edge Devices Market report. The full study contains the detailed data and worksheets enterprises require to commit capital, negotiate supplier SLAs, and design compliant deployment programs.
For detailed analysis of this topic, please visit the official page: Artificial Intelligence for Edge Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


