



PW Consulting: Central Gateway Module Market to hit USD 6,110M by 2032; 6.7% CAGR

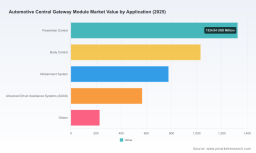
Automotive Central Gateway Module Market — Strategic Primer for 2026 Decision-Makers
As vehicle architectures evolve from federated to zonal and domain-oriented topologies, the central gateway module (CGM) has emerged from a component-level consideration to a strategic control point for automotive OEMs, tier‑1s, and semiconductor suppliers. Our PW Consulting Automotive Central Gateway Module Market study (base year 2025) synthesizes market dynamics, technology trajectories, supplier economics and regulatory imperatives into a single decision-grade briefing designed to inform boardroom choices and capital allocation in 2026.
Automotive Central Gateway Module Market
Why this study matters for 2026 strategies
-
Macro trajectory — The CGM market has moved from roughly USD 2.85 billion in 2020 to about USD 3.93 billion in 2025, and is forecast to grow to approximately USD 6.11 billion by 2032 under a mid‑cycle CAGR of ~6.7% for the forecast period. That pace is sufficient to drive sustained supplier consolidation and to justify multi‑year platform investments, but not so rapid as to remove the premium on disciplined program costing and modularity.
Automotive Central Gateway Module Market -
Strategic inflection — 2026 marks the first operational year when UNECE R155 and ISO/SAE 21434 related requirements for cybersecurity and functional safety are expected to materially affect supplier selection, bill of materials (BOM) design and software update strategies. Compliance is no longer an engineering checkbox; it is a commercial differentiator that alters total cost of ownership, warranty exposure and residual value assumptions.
Automotive Central Gateway Module Market -
Concentration & bargaining dynamics — The market is moderately concentrated: the top three players control nearly half of the market, and the top five account for roughly two‑thirds. For OEMs and Tier‑1s this creates an environment where strategic partnerships can secure preferred access to secure silicon and software stacks, while for smaller suppliers it raises the bar for design-to-cost and niche technical differentiation.
What the report delivers — action over description
Designed as an executable playbook rather than a reference catalogue, the full PW Consulting report blends quantitative forecasting with operational tools you can apply immediately in procurement, product planning and M&A diligence. Key deliverables include:
-
Verified market sizing and scenario-based forecasts (2026–2032) anchored on our 2025 base year and stress-tested against semiconductor cycles, EV penetration scenarios and regulatory shock cases.
-
Technology roadmaps that map CGM functional stacks (communication fabrics, compute and security engines, OTA support) to platform architectures commonly adopted by global OEMs, highlighting where Ethernet and high‑bandwidth backbones become mission‑critical.
-
A procurement risk matrix detailing supplier concentration, single‑sourcing exposure, and raw material / silicon supply vulnerabilities, with recommended mitigation actions for component hedging and multi‑sourcing.
-
Competitive benchmarking and supplier scorecards built around technology readiness, cybersecurity maturity, software update ecosystems and cost-to-serve metrics — tailored for use in RFQs, partner selection and Tier‑1 negotiations.
-
Regulatory compliance playbook that translates UNECE R155 and ISO/SAE 21434 mandates into product requirements (e.g., hardware security module integration, secure boot, intrusion detection and encrypted comms) and verification checkpoints required during 2026 program starts.
-
Investment and M&A frameworks that identify profiles of tuck‑ins, bolt‑ons and platform bets likely to generate near-term margin expansion or strategic lock‑in for OEMs and Tier‑1 integrators.
Market dynamics and drivers you must integrate into 2026 plans
-
Regulatory compliance is now engineering. UNECE R155 and ISO/SAE 21434 have escalated the need for embedded hardware security modules (HSMs), secure boot chains and intrusion detection in gateway products. These requirements increase per-unit complexity and create a recurring software‑driven services revenue opportunity (patching, vulnerability management) that must be priced into supplier contracts.
-
Bandwidth & compute reallocation. The shift toward Ethernet backbones and zonal ECUs increases input/output and compute demand at the gateway. This is accelerating demand for higher‑performance processors, real‑time virtualization, and deterministic Ethernet stacks — affecting BOM composition and thermal/EMC design considerations.
-
Supply‑side coupling. Semiconductor availability, raw material constraints and the need for close collaboration between component makers and raw material suppliers are shaping program timelines. Long lead components and qualification cycles can add 3–6 months to project schedules unless procurement hedges are in place.
-
Software-defined economics. As OTA capabilities become table stakes, CGMs are evolving into continuous service gateways. This changes lifetime economics — suppliers that can offer secure update frameworks, vulnerability monitoring and analytics capture will command premium margins and closer OEM engagement.
Competitive landscape — what distinguishes winners
The market combines established automotive electronics integrators with semiconductor leaders that supply the foundational building blocks. Success in 2026 will hinge on three capabilities: systems integration (hardware + middleware + cybersecurity), supply resilience, and software lifecycle services.
-
Systems integrators — Companies with deep vehicle systems expertise and global program management capabilities remain advantaged. Their ability to deliver cross‑domain connectivity, validate functional safety cases and scale production globally keeps them at the center of tiered supply chains.
-
Semiconductor and IP suppliers — Foundational silicon vendors that tightly couple processor performance with security IP and automotive-grade peripherals are shaping the BOM and locking in design wins earlier in platform cycles. Their roadmap cadence directly impacts module capabilities and cost curves.
-
Regional challengers and fast followers — Localized players are competing on cost and speed to market for regional OEMs; however, as compliance and cybersecurity requirements rise, these challengers must invest materially in security architectures to remain competitive.
Representative names in the ecosystem include historic automotive electronics leaders, global tier‑1 integrators and semiconductor suppliers. Each brings distinct strengths: deep vehicle integration and cybersecurity features (for global tier‑1s), connectivity stacks and ADAS integration experience, as well as processor and security IP from semiconductor vendors. For program evaluators, comparing supplier capabilities across integration depth, security compliance and long‑tail software support is essential.
Strategic playbook for 2026 — recommended actions
-
Reprice programs to reflect compliance costs: Build UNECE R155 / ISO 21434 compliance into target costs and supplier KPIs. Expect a step‑function increase in initial engineering hours and recurring vulnerability management fees.
-
Lock in secure silicon early: For new platform launches, prioritize early access to validated processors and HSM partners. Where possible secure multi‑year allocation agreements to avoid late‑cycle program slippage.
-
Design for software monetization: Treat the gateway as a subscription enabler. Define clear responsibilities for OTA infrastructure, data ownership and revenue sharing before production sign‑off.
-
Pursue focused M&A to plug capability gaps: Target bolt‑ons that bring certified cybersecurity stacks, OTA management platforms or advanced Ethernet switch expertise rather than broad horizontal acquisitions that dilute integration focus.
-
Stress test supply chains: Run 18‑month scenario analyses on single‑source components and validate second‑source paths for critical silicon. Incorporate escalation clauses and buffer inventory strategies in supplier contracts.
How to use our report in 2026 program cycles
Procurement teams will find the supplier scorecards and cost models immediately actionable during RFP rounds. Systems engineering will value the technology roadmaps and regulatory checklists for architecture decisions and validation planning. M&A and corporate strategy teams can use the scenario forecasts and concentration analytics to prioritize targets and quantify upside. Importantly, our scenario analyses are parameterized so you can rerun projections with your own EV penetration, ADAS adoption or semiconductor pricing assumptions.
What we intentionally withhold in this primer — and why
To preserve the commercial value of the underlying research and to ensure readers obtain the full, verifiable datasets needed for program-level decisions, this introduction omits core segment‑level tables and granular regional/application splits. The full report contains detailed segmentations, market share tables, unit‑level BOM breakdowns and downloadable vendor scorecards that are indispensable for bid modeling and contract negotiations. Think of this article as the strategic trailer: it maps the terrain and points to the exact datasets you will need to execute in 2026.
Closing guidance — a checklist for decision-makers
-
Embed UNECE R155 / ISO 21434 into supplier RFQs and program KPIs.
-
Prioritize early silicon commitments and multi‑source strategies for high‑risk components.
-
Redesign commercial terms to capture lifecycle software and security service revenues.
-
Use market concentration metrics to inform negotiation stance and M&A prioritization.
For teams preparing bids, signing strategic supply agreements or shaping 2026 product roadmaps, the full PW Consulting Automotive Central Gateway Module Market report provides the empirical backbone and practical instruments required to convert market growth into defensible margin improvements and strategic lock‑in. Visit our research portal to access the complete dataset, supplier scorecards and implementation templates necessary to move from strategy to execution.
For detailed analysis of this topic, please visit the official page: Automotive Central Gateway Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


