



Lateral Flow POC Reader Market to Hit USD 701.17M by 2032 at 3.0% CAGR — PW Consulting

Lateral Flow POC Reader Market — Strategic Outlook for 2026 Decisions
PW Consulting’s latest Lateral Flow Point-of-Care (POC) Reader Market briefing is designed as a strategic decisioning tool for executive teams, corporate development groups, and investors planning commitments in 2026. The market is no longer a peripheral accessory business: it is maturing into a measurable, device-driven diagnostic segment with steady growth, rising regulatory scrutiny, and new commercial architecture. This article synthesizes the report’s most decision-relevant insights while preserving the detailed, proprietary segmentation and model outputs for subscribers.
Lateral Flow POC Reader Market
Executive snapshot: Why this matters right now
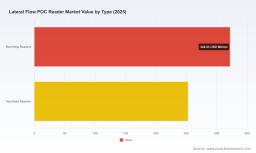
- The lateral flow POC reader market is established and growing. After notable expansion in the early 2020s, the global market reached an estimated USD 575.0 Million in 2025 (base year) and is projected to continue expanding through our 2026–2032 forecast window at a compound annual growth rate (CAGR) of approximately 3.0%.
- Growth that persists in a low-single-digit band signals a shift from a pandemic-driven spike to structurally driven, incremental adoption — driven by reimbursement shifts, regulatory clarity, and platform convergence across immunoassay and molecular point-of-care modalities.
- Competitive dynamics are consolidating: the top three players capture roughly half of the market, and the top five around two-thirds, creating meaningful scale advantages for incumbents while leaving pockets of opportunity for agile specialists and OEM partners.
Market trajectory: data-driven context without giving away the map
PW Consulting’s historical series traces market value from 2020 through the 2025 base year and projects through 2032. The trajectory shows a recovery from the volatility of the pandemic years into a steady mid-single-digit expansion path. By 2026 the market crosses a new threshold, reflecting the interplay of recurring POC demand and replacement cycles for both benchtop and handheld readers. By 2032 our consolidated forecast indicates continued expansion, driven by incremental penetration in routine clinical workflows, new reimbursement categories, and incremental product upgrades that emphasize quantitation, connectivity and regulatory compliance.
Lateral Flow POC Reader Market
Importantly for 2026 planning: the modest but persistent CAGR means strategic options that rely on scale and margin expansion (pricing discipline, consumables lock‑in, bundled service contracts) compound value meaningfully over a multi-year horizon; conversely, one-off tactical plays without a path to either recurring revenue or channel ownership will struggle to achieve acceptable returns.
Lateral Flow POC Reader Market
Forces shaping the market — what to watch this year
- Regulatory momentum and product eligibility: Recent clearances and CE/IVDR activity are reducing uncertainty. Examples include new FDA clearances and CLIA waivers in early 2026 for POC molecular platforms that sit adjacent to lateral flow diagnostics, and established IVDR pathways for quantitative readers. Regulatory clarity is reducing time-to-market for platform upgrades but increasing the need for compliance investment early in the product lifecycle.
- Reimbursement reclassification: Several European markets have moved reimbursement codes that recognize digital diagnostics as diagnostic devices rather than mere accessories. This reclassification elevates the commercial profile of readers (and the economic value of digital quantitation) and will materially affect purchasing decisions among hospital networks and primary care chains.
- Platform convergence and partnering: Expect continued horizontal integration across molecular and lateral-flow modalities. Strategic supply agreements and M&A in early 2026 underscore vendor emphasis on offering broader POC portfolios rather than single-use readers alone.
- Channel economics and OEM demand: Manufacturers of assays continue to weigh OEM reader partnerships versus app-based smartphone solutions. The economics of consumables, service, and software subscriptions increasingly dictate the most attractive GTM approaches.
Competitive pulse: who’s moving and why it matters
The market comprises established vendors, specialist OEMs, and emerging platform players. PW Consulting’s competitive analysis spotlights a set of companies with differentiated strategic postures:
- QuidelOrtho Corporation (San Diego, USA) — A leading integrated diagnostics firm that combines lateral flow readers with immunoassay and molecular POC assets. Recent strategic moves include a supply agreement with analyzer platform partners and an acquisition that expands their ultra-fast PCR portfolio. These actions indicate a deliberate pivot from single-product offerings to platform breadth and channel depth — a blueprint for scale-driven defensibility.
- Lumos Diagnostics (Australia) — Focused on clinical-grade LDX readers optimized for lateral flow assays in POC settings. Their positioning emphasizes clinical integration and performance, targeting adoption in ambulatory and decentralized testing sites.
- Axxin (Sweden) — Known for benchtop quantitative readers with strong regulatory positioning (CE, IVDR compliance and active FDA submissions). Axxin’s approach highlights technical robustness and compliance as enablers for partnerships with assay manufacturers seeking expedited market access in regulated jurisdictions.
- Detekt Biomedical (UK) — A supplier of OEM and custom reader platforms, operating in the niche between in-house development and off-the-shelf procurement. Their value proposition centers on customization and rapid integration for POC programs.
- Gold Standard Diagnostics (USA) — Markets quantitative readers for infectious disease and allergen testing. Their RapidScan line demonstrates that vertical specialization combined with quantitation capability remains a viable route for differentiation.
- Operon (Spain) — Offers off-the-shelf readers targeting POC immunoassay quantification. Operon’s strategy is to serve fragmented demand with accessible devices and streamlined procurement.
Collectively, these firms illustrate three viable strategic archetypes in 2026: platform consolidators (broad portfolios and channel reach), compliance/quality specialists (regulatory and performance differentiation), and OEM/integration players (customization and partnership-driven growth).
Strategic implications for 2026 decisions
- For medical device incumbents: If your objective is share expansion, prioritize platform breadth through targeted partnerships or tuck-in acquisitions that add complementary POC modalities and consumables. The economics of recurring consumables and service contracts will drive long-term value more than one-time device sales.
- For diagnostics innovators and assay developers: Validate two GTM pathways in parallel — an OEM partnership route (to access regulated, blue‑chip customers) and a direct, device‑agnostic digital approach (to accelerate adoption in low-barrier markets). Reimbursement wins in Europe make the OEM route increasingly attractive for clinical-grade assays.
- For private equity and strategic investors: Market concentration presents buy-and-build opportunities but requires disciplined playbooks to integrate regulatory, software, and service capabilities. Look for targets with established regulatory filings or modular platforms that can be cross‑sold into larger installed bases.
- For hospital networks and large buyers: Negotiate bundled contracts that lock in consumables and remote device management. Reimbursement changes increase the case for capital procurement, but buyers should insist on interoperability and upgrade pathways to mitigate obsolescence risk.
- For companies considering market entry: Avoid broad country-by-country rollouts. Prioritize geographies and channels where reimbursement and regulatory frameworks are favorable, and where distribution partners can deliver rapid access to clinical decision-makers.
What the PW Consulting report delivers (practical, operational outputs)
The full report is built for executives who must convert insight into action. It includes:
- A validated historical market series (2020–2025) and a forward-looking financial model (2026–2032) with scenario analysis and sensitivity tables.
- Proprietary segmentation across region, product type (benchtop vs. handheld), and end-use application, with demand drivers and tipping points per segment (note: detailed segment tables are reserved for subscribers).
- Competitive profiles and capability maps for the market’s leading vendors, with an assessment of product roadmaps, regulatory posture, and channel strategy.
- A regulatory and reimbursement tracker that identifies near-term risks/opportunities and quantifies their impact on adoption timing.
- Commercial playbooks — GTM scenarios, pricing levers, and an M&A/partnership matrix with likely synergies and integration risks.
- An executable 36‑month migration plan for buyers and vendors focused on product upgrades, procurement strategies, and IT/interop considerations.
- An interactive Excel model that allows you to run your own scenarios and test assumptions on penetration, pricing, and consumables attachment.
Recommended next steps for 2026
- Commission a rapid opportunity assessment (6–8 weeks) to quantify your addressable market under the new reimbursement rules and regulatory timelines.
- Prioritize one or two strategic partnerships to fast-track platform breadth; use supply agreements or white‑label OEM deals to bridge capability gaps rather than building from scratch.
- Fast‑track regulatory planning: lock in CE/IVDR compliance and establish a clear FDA engagement plan if the United States is a target market.
- Design commercial pilots that capture recurring revenue (consumables + software) and gather real-world health-economic data to support reimbursement submissions.
- Where M&A is on the table, prefer targets that bring either regulatory clearances or significant consumables attachment rates — those provide the most immediate value accretion.
Closing — how PW Consulting can help
The lateral flow reader market has transitioned from episodic growth into a structurally interesting segment with predictable returns for disciplined players. PW Consulting’s full Lateral Flow POC Reader Market report provides the granular segmentation, competitive intelligence, and executable playbooks needed to convert 2026 strategy into measurable outcomes. This article is a strategic preview: the report retains the proprietary segmentation tables, full company profiles, and the detailed financial model that corporate executives and investors require to make capital allocation decisions with confidence.
For teams preparing 2026 budgets, portfolio pivots, or acquisition screens, our report distills where to commit capital, where to partner, and where to wait for clearer signals. Contact PW Consulting or visit our report page to unlock the detailed model and the complete set of operational recommendations.
For detailed analysis of this topic, please visit the official page: Lateral Flow POC Reader Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


