



PW Consulting: Interactive Whiteboard Market to Grow at 7.27% CAGR Through 2032

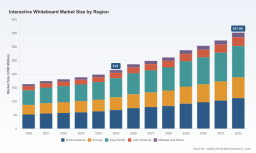
Interactive Whiteboard Market: Strategic Snapshot for 2026 Decision-Makers
Executive summary
As organizations finalize technology budgets and procurement roadmaps for 2026, interactive whiteboards are shifting from novelty peripherals to core collaboration infrastructure. Our PW Consulting analysis shows the global market expanding from an estimated USD 163.15 Million in 2020 to USD 215.0 Million in the base year 2025, and on a clear growth trajectory into the next planning cycle. With a forecast CAGR of 7.27% over 2026–2032, the market is projected to exceed USD 350 Million by 2032. These macro dynamics create distinct windows of opportunity — and risk — for buyers, vendors, and systems integrators.
Interactive Whiteboard Market
Why this research matters for 2026
-
Timing and scale: The market’s steady, mid-single-digit compound growth signals a maturing product category that still rewards first-mover deployments at scale (district-wide, enterprise-wide) while preserving room for differentiated entrants.
Interactive Whiteboard Market -
Procurement complexity: Modern interactive panels are no longer “plug-and-play” displays; they are full software ecosystems (OS versions, certification stacks, conferencing integrations) that materially affect total cost of ownership and upgrade cycles.
Interactive Whiteboard Market -
Competitive landscape: A relatively fragmented vendor base (CR3 ~24.6%, CR5 ~26.2%) means that buyers can exercise negotiating leverage, but also must navigate more variability in service, certification and ecosystem lock-in.
-
Operational impact: Installation, compliance and network integration costs remain significant contributors to project economics, and must be budgeted alongside hardware spend.
Market trajectory and what the numbers reveal
From a capital planning perspective, the historical trajectory and forecast create three practical implications for 2026 decision-makers. First, the category’s expansion validates multi-year refresh plans: the market grew from approximately USD 163 Million in 2020 to USD 215 Million in 2025, and our outlook anticipates an acceleration through the late-2020s, ending the 2026–2032 forecast horizon above USD 350 Million. Second, the 7.27% CAGR over the forecast period reflects a balanced blend of replacement demand, new-build education/corporate deployments, and the steady introduction of higher-margin, software-enabled services. Third, concentration metrics indicate meaningful fragmentation — a double-edged sword that creates both pricing pressure and buyer choice.
Key strategic implications for 2026 decisions
-
Procurement and vendor selection: Prioritize interoperability and software openness. Look beyond headline hardware specs (screen size, touch points) to OS lifecycle (Android versions, EDLA/GMS status), conferencing integrations (Teams, Zoom), and software roadmaps. For public procurement, ensure vendors can demonstrate required certifications and secure supply chains.
-
Pilot-to-scale pathway: Start with targeted pilots that validate interoperability, classroom/meeting-room workflows, and installation logistics. Use learnings to standardize procurement specifications that minimize unit-level variability during large rollouts.
-
Total cost of ownership: Account for installation and integration. Practical installations can create non-trivial labor and electrical/networking scopes that materially change per-unit economics. Entry-level panels lower capital outlay, while premium enterprise-grade panels carry higher platform and lifecycle costs — both must be reconciled against expected useful life, software subscription models, and support commitments.
-
Service and financing models: Consider bundled service agreements and financing options that align upgrades with software license cycles. Vendors with district/enterprise services, robust warranty and global support channels reduce operational friction for long deployments.
-
Risk management: Prioritize security and procurement-compliance certifications (e.g., TAA for government buyers, international quality and safety certifications for education). Also monitor supply-chain signals; certification and secure sourcing will be differentiators for strategic contracts.
Technology and product trends to watch in 2026
-
Platform convergence: Expect interactive displays to increasingly ship as integrated compute platforms (latest Android builds, AI-ready CPUs) coupled with a stronger emphasis on software ecosystems and cloud services.
-
Software-first differentiation: Vendors succeed with sticky, value-adding software (collaborative whiteboarding suites, classroom management, analytics) rather than relying on hardware alone.
-
Certifications and ecosystem access: EDLA/Google partnerships, GMS, and conferencing-certified modules (Chromebox OPS compatibility, Teams/Zoom integrations) will accelerate procurement decisions where manageability and user experience matter.
-
Accessibility and health: Eye-care technologies, blue-light mitigation and ergonomic mounting options are moving from nice-to-have to procurement checkboxes in K–12 and higher-ed budgets.
Competitive landscape — who matters and why
The vendor field is diverse: multinational electronics incumbents sit alongside specialized education-focused suppliers and nimble platform-focused entrants. Strategic buyers should map vendors across three vectors — product platform openness, software ecosystem, and services footprint — rather than raw screen specifications.
-
SMART Technologies (Canada) — Positions itself around education-first features with scaled entry options. Recent launches include highly competitive lower-cost models and a compact interactive podium, both aimed at expanding addressable adoption for budget-constrained institutions.
-
Promethean (UK) — Emphasizes classroom collaboration and ecosystem integration. Its ActivPanel series, paired with ActivSuite and conferencing integrations, targets organizations that require turnkey classroom and hybrid-workroom features.
-
Samsung (South Korea) — Leverages display expertise and wireless collaboration, focusing on high-resolution panels and strong enterprise-grade conferencing integrations. Their offerings tend to appeal where display performance and brand-backing carry weight.
-
TRIUMPH BOARD (China) — Aggressively updates product platforms to the latest Android releases and pursues certifications that help international expansion.
-
BenQ (Taiwan) — Positions on education-centric features like eye-care and AI-readiness, combining hardware quality with content and classroom ergonomics.
-
ViewSonic (US) — Focuses on software-driven collaboration and flexible ecosystem choices, enabling integration across a wide set of enterprise and educational environments.
-
Newline Interactive (South Korea) — Offers open Android platforms and “software freedom” positioning that resonates with buyers wary of vendor lock-in.
-
Boxlight (US) — Deep in K–12 deployments, Boxlight provides district-scale solutions and services that simplify large rollouts and support models.
-
Ricoh (Japan) — Delivers enterprise and education models with a services-first approach, including wireless collaboration and certified models for regulated procurement.
-
ELMO (Japan) — Competes on cost-effectiveness and wireless collaboration, with accessible models tailored for classrooms and budget-constrained buyers.
Recent vendor moves that should shape 2026 strategy
-
SMART’s rollout of a more affordable interactive display and a compact podium solution signals a push to broaden addressable markets, especially in budget-conscious education segments.
-
Promethean’s demonstration of its latest ActivPanel lineup with deeper conferencing and OPS compatibility underscores a race to be the enterprise-class software partner to education and corporate buyers.
-
TRIUMPH BOARD’s platform refreshes to newer Android versions and certification advances reflect how platform currency and certified ecosystems are becoming competitive levers.
Report contents — what the full study delivers
-
Market sizing and calibrated forecasts (base year 2025; forecast 2026–2032) with scenario-based sensitivity analysis.
-
Segment-level frameworks that reveal drivers and constraints (technology, procurement, regulatory) without exposing confidential client-level datasets.
-
Vendor universe profiling and comparative capability matrices covering product roadmaps, software ecosystems, certifications, and services footprints.
-
Deployment economics templates and TCO calculators that include hardware, installation, networking, and multi-year support assumptions.
-
Go-to-market playbooks for systems integrators and channel partners, including bundling and financing strategies for large-scale public and private deployments.
-
Decision-maker checklists and RFP language examples to streamline sourcing and reduce buyer risk.
Signals to monitor through 2026
-
Platform certification adoption (EDLA/GMS) and Android lifecycle policies — these directly affect software compatibility and refresh cadence.
-
Service and integration pricing trends — labor and installation scopes can materially affect unit economics for mid-to-large deployments.
-
Consolidation activity — low concentration suggests M&A could quickly reshape supplier economics and bargaining power.
Practical next steps for buyers and vendors
-
Buyers: Run a 12–18 month pilot that validates conferencing flows, device management, and TCO assumptions. Insist on transparent lifecycle and software roadmaps in supplier contracts.
-
Vendors and integrators: Differentiate on interoperable software services, predictable installation planning, and clear certification roadmaps. Consider bundled support/financing offers to reduce procurement friction.
-
Investors/partners: Look for vendors that combine a defensible software ecosystem with channel reach—these are prime candidates for value creation in a fragmented market.
How PW Consulting helps
Our full Interactive Whiteboard Market study provides the data models, procurement templates, and vendor benchmarking that procurement teams and executive sponsors need to make informed 2026 decisions. The report marries granular scenario analysis with executive-ready strategy playbooks, and is purpose-built to support RFx development, vendor negotiations, and deployment planning.
Call to action
This preview outlines the strategic contours and operational levers that will determine winners and losers in 2026. For the complete segmentation, supplier scorecards, downloadable TCO models, and region- and application-level forecasts that inform contracts and capital plans, access the full PW Consulting Interactive Whiteboard Market report on our website.
For detailed analysis of this topic, please visit the official page: Interactive Whiteboard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


