



PW Consulting: Dry Ice Market Reaches USD 215M in 2025—Outlook and Opportunities

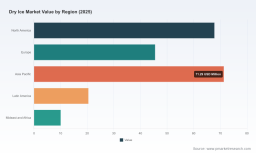
Dry Ice Market: Strategic Outlook for 2026 — A PW Consulting Industry Brief
As organizations prepare budgets, contracts, and supply strategies for 2026, the dry ice market deserves renewed strategic attention. PW Consulting’s latest market study — base year 2025 with a forecast through 2032 — shows a clear, investible growth trajectory underpinned by resilient demand in temperature-sensitive logistics, expanding applications in food and beverage processing, and ongoing innovation in thermal packaging. This brief synthesizes the report’s high‑value signals for executive decision‑makers while withholding proprietary segmentation details to encourage direct access to the full study for implementation‑level intelligence.
Dry Ice Market
Macro trajectory: growth you can plan around
Across the 2020–2025 historical window the global dry ice market moved from a modest mid‑three‑digit million USD base to a stronger 2025 position, reflecting accelerating demand for cold‑chain support and industrial uses. Our forecast projects compound annual growth of 7.5% over 2026–2032, taking the market to roughly USD 345 million by 2032. That pace and scale matter: they convert dry ice from a niche operational input into a predictable category for strategic sourcing, capital allocation for packaging innovation, and targeted commercial investment.
Dry Ice Market
- 2020–2025: steady recovery and structural demand building driven by food, logistics, and healthcare-related shipments.
- 2026–2032 (forecast): a sustained expansion at 7.5% CAGR, reflecting both volume growth and upward pressure on per‑unit logistics and specialty packaging costs.
Why this matters for 2026 corporate decisions
Analogs from other industrial gases and cold‑chain inputs show that when a market reaches the growth profile identified in our study, three classes of corporate decisions become consequential:
Dry Ice Market
- Supply architecture: locking in diversified supply and contingency agreements to mitigate CO2 feedstock volatility and regulatory friction.
- Packaging and logistics investment: selecting insulated packaging and dry‑ice‑compatible solutions that reduce total landed cost and regulatory friction for air and ground transport.
- Channel and product strategy: designing offerings that capture higher‑margin uses such as pharma cold shipments and specialized food processing services.
For procurement leads, the implied annual growth creates negotiating leverage if contracts are timed appropriately. For commercial leaders, the forecast justifies pilots of premium temperature‑assured propositions in high‑value verticals. For R&D and operations, the market parameters support investments in automated on‑site production and more efficient pelletization/form factor conversions — where permitted by safety rules.
Supply dynamics and regulatory risk — the near‑term constraints
Two structural themes in the report demand immediate attention from risk and continuity managers.
- Feedstock concentration and geopolitics. Certain regional CO2 supplies remain tied to a small number of industrial processes. For example, bioethanol by‑product streams can represent a meaningful share of food‑grade CO2 in specific markets, creating a single‑source sensitivity that can ripple into dry‑ice availability. Trade policy shifts that affect bioethanol economics can therefore translate into short‑term supply disruptions for food‑grade dry ice.
- Hazardous‑goods regulation. Dry ice is regulated as a dangerous good for transport. Ground shipments fall under specific hazardous materials rules, and air transport requires full IATA dangerous‑goods compliance, including package labeling (UN1845, net weight) and quantity limits. Notably, current IATA rules allow defined per‑package quantities for non‑dangerous goods shipments — a flexibility that logistics teams should exploit where appropriate but only after validating packaging and labeling compliance.
Practical implication: 2026 supply strategies must combine longer‑term offtake or tolling arrangements with short‑term tactical buffers, and logistics playbooks must be audited for IATA/DOT compliance before scaling volume shipments via air.
Commercial drivers and structural demand
Demand for dry ice no longer depends solely on seasonality. The market is expanding through a mix of structural drivers:
- Food and beverage cold‑chain expansion — rising e‑commerce of perishable goods and just‑in‑time processing increases use cases for dry‑ice‑based temperature control.
- Pharmaceutical and biologics logistics — the need for validated, short‑duration frozen conditions for certain vaccines, biologics, and clinical samples has created a higher‑margin segment where reliability and regulatory pedigree matter more than unit price.
- Industrial and specialty uses — surface cleaning, blast media substitutions, and niche industrial processes continue to sustain baseline demand.
The upshot for 2026: companies that can package a value‑chain offer (supply + validated packaging + documentation) will capture outsized commercial returns relative to commodity suppliers that only sell product by weight.
Competitive landscape — who matters and what they bring
The market is meaningfully consolidated at the top, with leading industrial gas companies holding the majority of commercial volumes and a broader ecosystem of regional specialists and equipment vendors serving niche needs. The concentration profile indicates that top players control a decisive share of market volume, while specialized producers and equipment manufacturers round out the competitive set.
Key strategic players and their competitive roles include:
- Linde plc — Global leader with integrated gas and logistics capabilities; strong across food & beverage cold‑chain and industrial accounts.
- Air Products and Chemicals Inc. — Large scale supplier with extensive cold‑chain and logistics networks, positioned to support high‑volume customers.
- Air Liquide S.A. — Broad international footprint and portfolio of industrial and pharma‑grade solutions for temperature control.
- Messer Group GmbH and other regional integrated gas groups — Strong in temperature‑controlled packaging and distribution within European and industrial markets.
- Equipment and system suppliers (e.g., Cold Jet) — Provide production systems and pelletization equipment that enable on‑site generation and process optimization.
- Specialized regional producers and distribution partners — Offer localized service models and rapid fulfillment for last‑mile cold shipments.
Strategic takeaway: incumbent industrial‑gas firms sustain scale advantages in supply and compliance, but there is commercial room for specialized providers that bundle validated packaging, dedicated logistics, or on‑site production equipment into a managed service proposition.
Innovation signals and recent developments
Product and packaging innovation is accelerating, and 2025–2026 product launches point to where value is migrating:
- Peli BioThermal introduced single‑use dry‑ice‑compatible shipping systems that simplify regulatory handling for one‑way shipments — an important enabler for clinical and commercial cold‑chain distribution.
- Packaging suppliers launched sustainable bulk insulation solutions tailored for palletized dry‑ice shipments, reflecting customer demand to reconcile thermal performance with circularity goals.
These trends imply that technology adoption in packaging and validated shipper systems will be a differentiator in 2026 for buyers and service providers alike.
What the full PW Consulting report delivers (operationally focused)
The full study is designed to move organizations from insight to action. Highlights include:
- Market sizing and validated CAGR across historical and forecast horizons to inform financial planning.
- Commercial playbooks for procurement, including supplier scorecards, suggested contract terms, and contingency buffer sizing.
- Packaging and logistics decision trees that align product form (e.g., blocks vs pellets) with route and regulatory constraints.
- Supplier benchmarking and capability maps covering global leaders, regional specialists, and equipment OEMs.
- Scenario analyses of supply‑shock impacts and mitigation pathways tied to feedstock concentration and trade policy changes.
To preserve the strategic value of our proprietary segmentation and price elasticity models, the report reserves detailed numerical splits and supplier share tables for full subscribers — an intentional gating that protects the tactical playbooks buyers use to negotiate advantage.
Recommendations for 2026 planning
- Audit and align: conduct a 90‑day audit of dry‑ice handling and packaging across your shipping lanes to close IATA/DOT compliance gaps.
- Diversify supply with contracts that combine firm volumes and short‑term flex allowances tied to feedstock price indices.
- Pilot packaging innovations in high‑value corridors (e.g., pharma or direct‑to‑consumer perishables) to measure total landed cost and returns over 12 months.
- Engage top‑tier industrial‑gas suppliers for strategic partnerships on on‑site generation where volume warrants capital investment.
- Build scenario playbooks for CO2 feedstock disruption and monitor geopolitical indicators affecting bioethanol and other CO2 sources.
Closing — why PW Consulting’s study should be on your 2026 agenda
The dry ice market’s profile has evolved from a tactical commodity to a strategic enabler for temperature‑sensitive value chains. With a clear growth trajectory and a convergence of regulation, packaging innovation, and supply concentration risks, 2026 will reward firms that take a disciplined, data‑driven approach to sourcing, packaging, and go‑to‑market design.
PW Consulting’s full report provides the operational templates, supplier scorecards, and scenario stress tests that executives need to move from insight to contracting and deployment. For teams preparing 2026 budgets and supply strategies, the study is structured to be directly actionable — without requiring extensive re‑interpretation.
Access to the complete dataset, proprietary segmentation, and contract playbooks is available on the report landing page. For bespoke advisory support and to translate the findings into a 90‑day execution plan tailored to your organization, contact PW Consulting’s Strategy & Industry Practice.
For detailed analysis of this topic, please visit the official page: Dry Ice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


