



Radiation Detector Market to Reach USD 3,219.94M by 2032 at 8.2% CAGR | PW Consulting

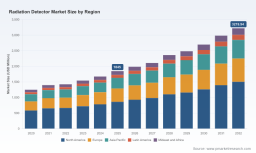
Radiation Detector Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking executive preview of our comprehensive Radiation Detector Market study. Grounded in historical analysis (2020–2025) and a seven-year forecast horizon (2026–2032), this briefing articulates the strategic value the full report delivers to corporate leaders making high-stakes decisions in 2026. We demonstrate where meaningful growth and risk converge — while intentionally reserving granular subsegment tables and proprietary scenario outputs for the full report to preserve its commercial value.
Radiation Detector Market
Why this study matters for 2026 decision cycles
-
Timing: 2026 is a pivot year for procurement cycles in utilities, healthcare capital budgets and national security programs. Our report synthesizes the latest baseline (base year 2025) with near-term regulatory inflection points to advise practical action windows.
Radiation Detector Market -
Scale: The Radiation Detector market has moved from a consolidated but specialized niche to a multi‑billion‑dollar growth market. In our baseline, the global market reached approximately USD 1,845 Million in 2025 and, under central-case assumptions, is projected to expand to roughly USD 3,220 Million by 2032 — a compound annual growth rate of about 8.2% across the forecast period.
Radiation Detector Market -
Concentration: The industry exhibits high supplier concentration at the top — the three largest vendors command a substantial majority of market share, and the top five consolidate over four‑fifths of the market — implications that affect pricing power, standards setting, and channel dynamics.
High‑level market trajectory and implications
From 2020 through 2025 the market exhibited steady expansion driven by healthcare modernization, legacy nuclear facility upgrades, and rising civil security investment. The projected CAGR of 8.2% is not evenly distributed across product types or geographies; rather, it reflects regime shifts in technology adoption (semiconductor detectors, advanced scintillators), regulatory tightening, and growing demand for distributed monitoring solutions. For executives, the headline numbers tell a clear story: the addressable opportunity is expanding rapidly enough to justify accelerated R&D, targeted M&A, or capacity investments — but the optimal path depends on a firm’s risk appetite and strategic objectives.
Key demand drivers and timing considerations
-
Regulatory tightening and standards updates — including new calibration procedures and national compliance mandates — are increasing baseline replacement cycles and creating procurement lift for compliant systems and services. These cycles typically create concentrated tender waves that procurement teams should anticipate in 2026–2028.
-
Healthcare modernization and radiation safety programs are sustaining steady replacement and service demand, while high-resolution imaging and dosimetry innovations open adjacent premium product segments.
-
National security and first‑responder modernization — amplified by geopolitically driven budget shifts — are accelerating demand for portable, isotope‑identifying, and networked detectors.
-
Supply constraints in specific semiconductor inputs and metals continue to shape delivery lead times and component costs. These supply constraints can materially affect time-to-market for advanced solid‑state and CZT‑based detectors.
Supply chain and geopolitical risk — practical red flags for 2026
Strategic sourcing must factor in material and technology concentration risks. Export controls and raw material restrictions have been recent and ongoing considerations: export-control regimes affecting critical materials and certain detector technologies remain active, and at least one major supplier market has maintained export curbs that influence semiconductor and high-density metal availability. For procurement and operations teams, this translates to longer qualification cycles for alternate suppliers, potential premium pricing for forward‑covered components, and the need for playbooks to sustain production continuity under export licensing regimes.
Recommended near-term actions:
-
Conduct a component‑level risk assessment tied to production schedules and key accounts.
-
Pursue dual‑sourcing strategies for semiconductors and shielding materials where feasible.
-
Advance export compliance capability and scenario planning for licensing delays impacting cross‑border contracts.
Regulatory and standards landscape — catalysts and compliance windows
Recent and emerging regulatory inputs carry direct procurement and product‑development implications. New calibration procedures and national monitoring mandates create compliance-driven demand for recertification, replacement detectors, and associated calibration services. Separately, stricter export licensing rules for sensitive technologies are raising the transactional complexity of cross-border deals, particularly for products with advanced isotope identification functionality.
Corporate actions to consider:
-
Accelerate compliance roadmaps to ensure product portfolios meet updated calibration and monitoring standards.
-
Embed regulatory intelligence into product roadmaps to preclude late-stage redesign associated with compliance updates.
-
Integrate export-control expertise into commercial due diligence, especially for international growth strategies and M&A targets.
Competitive landscape — what the top players signal
The market is characterized by a mix of legacy instrumentation firms, specialist dosimetry providers, and fast‑moving niche players in semiconductor and imaging detectors. The top vendors combine broad portfolios (survey meters, dosimeters, high‑resolution spectrometers) with established service and accreditation capabilities — an interplay that raises switching costs for large institutional buyers.
-
Mirion Technologies — established leader offering dedicated products for first responders and comprehensive nuclear measurement systems. Their product breadth positions them well for large institutional contracts and integrated services deals.
-
Thermo Fisher Scientific — leverages scale and portfolio depth across dosimetry and monitoring instruments; attractive to healthcare and large laboratory buyers seeking end‑to‑end vendor relationships.
-
LANDAUER — specialized in occupational dosimetry and badge‑based monitoring; built‑in service and accreditation capabilities provide stickiness among medical and occupational customers.
-
Polimaster — focused on portable and deployable detection systems, including personal and backpack detectors; innovation in field instruments makes them a competitive choice for civil security and mobile response units.
-
Kromek Group — competitive in CZT-based detectors and isotope identification; recent product releases position them for growth in high‑resolution and intelligence-driven applications.
-
AMETEK ORTEC — strengths in high‑resolution semiconductor instruments and spectroscopy solutions; favored where analytical performance commands a premium.
-
Ludlum Measurements — broad portfolio of practical survey and personal meters; well entrenched in industrial and utility maintenance markets.
-
Radiation Detection Company — service‑oriented dosimetry and accredited testing offerings that appeal to regulated occupational markets.
Recent product and demonstration events — including in‑orbit detector tests and new RIID launches — illustrate two market dynamics: first, suppliers are racing at both ends of the spectrum (field‑portable, rugged instruments and high‑resolution laboratory systems); second, demonstrations and standards compliance are increasingly central to commercial differentiation.
Report scope and operational deliverables
Our full report provides practical, actionable intelligence for executives and functional leaders. Highlights include:
-
Market sizing and growth scenarios (historical 2020–2025 and forecasts to 2032) with sensitivity testing under alternate regulatory and supply‑chain shock assumptions.
-
Financial and commercial benchmarks to support pricing, margin improvement, and investment prioritization.
-
Vendor scorecards, capability matrices, and go‑to‑market maps to inform partner, distributor, and acquisition targeting.
-
Procurement playbooks aligned to typical buyer archetypes (utilities, healthcare systems, defense and security agencies, industrial operators), including contract structuring clauses for warranty, calibration, and export compliance.
-
Scenario‑based roadmaps for product development that align R&D spend with near‑term regulatory windows and medium‑term market growth pockets.
-
Service and aftermarket models that quantify lifetime revenue opportunities across calibration, accreditation, and data‑monitoring subscriptions.
How to use this intelligence in 2026 planning
For C‑suite leaders and strategy teams, the value of the report is pragmatic: translate growth forecasts and concentration metrics into decisive actions for portfolios, M&A pipelines, and operational investments. Recommended workflows for calendar‑year 2026:
-
Prioritize targets for capability augmentation where product gaps align with rising regulatory requirements and field performance expectations.
-
Rebalance R&D roadmaps to accelerate features that reduce total cost of ownership for institutional customers (e.g., simplified calibration, remote diagnostics, serviceable modular designs).
-
Define a two‑track supply strategy: near‑term tactical buys to secure components and a medium‑term localization plan to reduce exposure to export‑control volatility.
-
Prepare commercial templates that reflect longer lead times, higher compliance requirements, and potential licensing hurdles for cross‑border sales.
Final observation and call to action
The Radiation Detector market presents an attractive growth trajectory with clear pockets of premiumization tied to performance, compliance, and connected services. Yet, supply‑chain rigidity and evolving export and calibration regimes mean that execution risks are non‑trivial. The macro path to roughly USD 3.22 billion by 2032 (central case) and an 8.2% CAGR masks important heterogeneity that materially affects investment returns.
PW Consulting’s full report delivers the missing granularity — segmented demand profiles, procurement‑ready vendor shortlists, financial models, and scenario maps that translate market projections into investment‑grade decisions. For teams planning capital allocation, product launches, M&A screening, or strategic sourcing in 2026, this intelligence converts uncertainty into competitive advantage.
Contact PW Consulting to access the complete dataset, proprietary subsegment analysis, and bespoke advisory packages tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Radiation Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


