



PW Consulting: Industrial RTU Market: 4.2% CAGR to USD 1,060.39M by 2032; Asia Pacific $326.77M

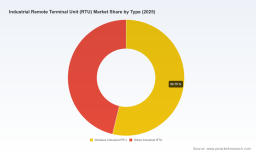
Industrial Remote Terminal Unit (RTU) Market — Strategic Outlook for 2026 Enterprise Decision-Making
As PW Consulting’s lead industry analyst, I present a concise, strategy-first briefing that frames our full Industrial Remote Terminal Unit (RTU) Market study for executives planning decisions in 2026. This briefing demonstrates the analytical depth and practical orientation of the research while deliberately withholding granular segment datapoints and proprietary tables to guide readers to the full report for detailed validation.
Industrial Remote Terminal Unit (RTU) Market
Market trajectory at a glance — what the numbers imply
The RTU market has shown steady expansion through the early 2020s and continues on a modest growth trajectory. Our base-year assessment for 2025 places the global market near USD 801 million, rising at a compound annual growth rate (CAGR) of approximately 4.2% over the 2026–2032 forecast window, reaching just over USD 1.06 billion by 2032. Historical trend analysis shows sustained recovery and investment cycles since 2020, reflecting a combination of legacy-system refreshes, targeted digitalization in industrial verticals, and increasing portfolio mixes that include edge-enabled and wireless-capable RTUs.
Industrial Remote Terminal Unit (RTU) Market
Why this matters for 2026: the market size and mid-single-digit CAGR indicate an environment where disciplined prioritization of capex and differentiated product/service strategies win. Large incumbents and focused specialists alike will chase incremental growth—creating selective opportunity windows for strategic buyers, system integrators, and technology partners.
Industrial Remote Terminal Unit (RTU) Market
Market structure and competitive dynamics — fragmentation with platform concentration
The market is structurally fragmented: the share held by the largest three and five firms is modest, signaling ample room for regional specialists, system integrators, and component vendors to compete. This fragmentation creates strategic consequences:
- Price and specification competition remain intense at the low end, favoring scale players and contract manufacturers.
- At the high end, platform interoperability, cybersecurity, and lifecycle services are primary differentiators.
- M&A and partnership playbooks are the likely medium-term levers for top-tier players to accelerate access to niche capabilities and regional footprints.
Key market participants we track include global automation and control leaders, telecom and communications specialists, industrial computing vendors, and regional RTU manufacturers and integrators. The following qualitative profiles summarize the strategic postures we see in the market (this is an analytical snapshot, not an exhaustive vendor scorecard).
- ABB (Zurich): Leverages broad grid and automation franchises to position RTUs within larger distribution and substations solutions; focus on system-level integration and lifecycle services.
- General Electric (Schenectady): Integrates RTUs into broader asset management and industrial digitalization offers, emphasizing analytics and legacy modernization pathways.
- Schneider Electric (Rueil‑Malmaison): Uses EcoStruxure and system-level offerings to bind RTUs into energy management and process-automation value propositions.
- Honeywell (Charlotte): Positions RTUs as part of its process automation and remote monitoring suites, strong in regulated industries requiring proven safety and compliance traces.
- Siemens (Munich): Offers RTUs within grid automation and industrial digitalization stacks, with emphasis on interoperability and engineering tools.
- Emerson (St. Louis): Focuses on process industries and integration with DCS platforms; competitive where lifecycle services and vendor-managed solutions are required.
- Rockwell Automation (Milwaukee): Competes via control-system integration and scalable automation architectures suited to North American process and discrete markets.
- Motorola Solutions (Chicago): Brings communications and ruggedized networking strengths—relevant where mission-critical remote communications are a core requirement.
- Advantech & Moxa (Taipei): Position as industrial-computing and IIoT gateway specialists that translate RTU data into edge compute and connectivity solutions.
- Yokogawa (Tokyo): Integrates RTUs with DCS and process-control expertise, strong in long-cycle capital projects.
- Red Lion (York) & Fanox (Barcelona): Niche specialists in protocol conversion, remote monitoring, and protection components—important partners for retrofit programs.
- Arteche, Iskra Sistemi, SEL, Dongfang Electronics: Regional and technical specialists providing measurement, protection, and rugged RTU solutions tailored to local grid and industrial standards.
- INTECH Process Automation, Kalki Communication Technologies: Systems integrators and communications specialists that convert vendor stacks into working field deployments at scale.
Strategically, incumbents lean on platform integration and services to expand TAM per customer, while smaller vendors compete on price, agility, and regional compliance expertise. Expect an uptick in alliances pairing global platforms with regional integrators over the next 18–24 months.
Demand drivers and headwinds — shaping priorities in 2026
- Digitalization & IIoT adoption: Edge analytics, remote asset management, and data-driven O&M are primary demand drivers. RTUs that natively support secure edge processing and common industrial protocols gain procurement preference.
- Asset modernization: Utilities and industrial operators with long tail of legacy RTUs will pursue staged refreshes to balance reliability and ROI.
- Cybersecurity mandates: Regulatory and insurer expectations force RTU purchases to include hardened communication stacks and patch-management guarantees.
- Wireless uptake vs. wired reliability: Wireless RTUs unlock lower-install-cost remote monitoring, but mission-critical applications still demand deterministic wired options; product roadmaps must accommodate both.
- Supply chain & materials volatility: Semiconductor supply-chain constraints, and the rising compliance and cost pressures around sustainable packaging and materials, affect lead times and TCO modeling.
Note on regulatory context: broader environmental and packaging regulations in major markets are increasingly relevant to hardware vendors’ supply chains. For example, recent EU and UK directives and taxes on packaging and recycled-content requirements have raised supplier compliance burdens and, in some cases, near-term cost exposure for plastic enclosures and packaging. In Europe, recycled-PET pricing has been higher than virgin PET through 2020–2025 in certain categories—an issue that hardware procurement teams should model into total lifecycle costs and supplier audits.
Strategic playbook for 2026 — recommended actions
- Adopt a two-speed procurement model: fast pilots for wireless/edge RTU use cases and long-lead tender tracks for mission-critical wired deployments.
- Prioritize interoperability and lifecycle services in vendor selection to reduce obsolescence risk and lower long-term TCO.
- Embed cybersecurity and patch-management SLAs into procurement contracts; require supplier transparency on supply-chain resilience.
- Design retrofit-first architectures where practical—use vendor-agnostic protocol gateways and edge compute nodes to extend legacy asset life while enabling phased data enrichment.
- Maintain an M&A/partnership watchlist: regional integrators and niche technology providers offer rapid capability fills for cloud/edge analytics and communications.
- Model regulatory cost exposure linked to packaging and materials compliance as part of capex justification for new hardware rollouts.
What the PW Consulting RTU report delivers (practical content)
Our full study is built for immediate operational use by procurement, OT/IT architects, and corporate strategy teams. Highlights include:
- Market sizing and 2020–2032 forecast with scenario variants and sensitivity to key drivers (base-year 2025 anchoring).
- Segmentation frameworks (by product type, application, and region), plus addressable-market maps for prioritizing growth plays — note: granular segment tables are available in the full report.
- Vendor benchmarking across technical, commercial, and delivery dimensions (capability heatmaps and RFP-ready supplier shortlists).
- Go-to-market playbooks: retrofit vs greenfield decision trees, pilot designs, and integration checklists.
- Financial tools: TCO and ROI templates for procurement justification, and capital planning scenarios under different obsolescence/maintenance assumptions.
- Risk matrix and mitigation playbook covering supply chain, regulatory, and cybersecurity exposures.
- Primary research annex: interview summaries with buyers, integrators, and vendor product leads, plus methodology notes and data sources.
Closing — why use this insight in 2026
By 2026, typical enterprise agendas will combine tighter capital discipline with an increased need to extract operational value from existing assets. The RTU market’s modest growth yet fragmented supplier landscape means that a targeted strategy—combining selective capex, supplier rationalization, and partnerships for analytics and cybersecurity—will generate outsized returns versus blanket replacement programs.
This briefing provides the strategic spine; the full PW Consulting RTU Market report supplies the granular segmentation, interactive models, and vendor-level benchmarking necessary to operationalize these recommendations. We intentionally withheld detailed subsegment tables and proprietary mappings here to ensure readers consult the full dataset for procurement and investment-grade decisions.
To access the comprehensive dataset, vendor scorecards, and downloadable decision tools, please consult the full PW Consulting report and supporting digital workbook.
For detailed analysis of this topic, please visit the official page: Industrial Remote Terminal Unit (RTU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


