



PW Consulting: Fiber-Coupled SLED Market to Reach USD 265M by 2032 (7.45% CAGR)

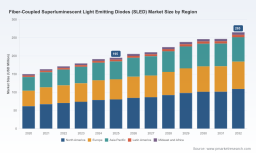
Fiber-Coupled SLED Market: Strategic Intelligence for 2026 Decision-Making
Executive summary
As PW Consulting’s lead industry analyst, I present an evidence-backed overview of the fiber-coupled superluminescent diode (SLED) market tailored to executives and product strategists preparing for 2026. The market has demonstrated steady expansion, growing from approximately USD 150.0 Million in 2020 to USD 195.0 Million in the 2025 base year. Our forecast horizon (2026–2032) models a continuation of this trend, with the market projected to expand at a compound annual growth rate (CAGR) of 7.45%, reaching roughly USD 265.0 Million by 2032. These headline figures quantify a clear commercial runway for suppliers, integrators, and downstream system OEMs—but they only tell part of the story. The purpose of this briefing is to translate that macro trajectory into the discrete strategic choices that will matter in 2026, while preserving the proprietary granularity that lies within our full report.
Fiber-Coupled Superluminescent Light Emitting Diodes (SLED) Market
Why 2026 is a pivotal planning year
-
Technology inflection: Optical coherence tomography (OCT), advanced fiber sensing and certain metrology applications are maturing in parallel with multi-SLED and tunable broadband innovations. Companies that lock in technology leadership or differentiated supply now can capture outsized share as system integration accelerates over the next two to three years.
Fiber-Coupled Superluminescent Light Emitting Diodes (SLED) Market -
Supply-chain tightening and regulatory shifts: New export control regimes and critical-mineral licensing introduced by key suppliers are already changing sourcing economics and valid routes to market. Procurement strategies established in 2026 will materially affect lead times and margin profiles through 2027–2029.
Fiber-Coupled Superluminescent Light Emitting Diodes (SLED) Market -
Consolidation window: Market concentration metrics indicate a moderate incumbent advantage—top-three vendors control a meaningful but non-dominant portion of revenue, and top-five concentration increases that share materially. This creates both acquisition targets for scale players and white-space opportunities for innovative niche entrants.
Market trajectory and what the top-line numbers conceal
The market’s steady growth—evidenced by a rise from USD 150.0 Million in 2020 to USD 195.0 Million in 2025 and a forecast path to roughly USD 265.0 Million by 2032 at a 7.45% CAGR for 2026–2032—masks divergent microtrends that will decide winners and losers. Pricing ranges for single SLED diodes vary by wavelength, fiber type and customization, and we observe transaction price bands from approximately USD 673 to USD 2,624 per diode in typical industry datasets. Standard lead times clustered around five weeks create a planning cadence for OEMs building to production ramps.
But unit economics, integration complexity, and service-level expectations differ sharply by end-market. Organizations that interpret the headline market growth without overlaying technology roadmaps, regulatory risk matrices, and supplier resilience scenarios will misallocate capital. Our work stresses that the aggregate expansion is necessary but not sufficient to inform product investment, M&A, or channel strategy.
Supply chain and regulatory dynamics — actionable implications
-
Material dependencies: Fiber-coupled SLED devices remain dependent on compound semiconductor materials—InGaAs, InP and GaAs—and their associated supply chains. This creates vectors of risk (single-source substrates, specialty wafer processing) that translate to lead-time and cost volatility for system integrators.
-
Export controls and licensing: Recent policy changes instituted by major material-exporting jurisdictions have introduced licensing requirements for components that use certain Chinese-sourced materials or production technologies. These regulatory shifts are not binary; they create a sliding scale of compliance cost and approval delay that should be stress-tested across procurement scenarios.
-
Price and procurement strategy: Given the observed price dispersion, buyers can improve margin capture by redesigning product specifications to accept alternate fiber terminations, modular SLED assemblies, or multi-sourcing strategies. Conversely, suppliers can protect ASPs by bundling optical engines with calibration and software, reducing direct comparability.
Competition and consolidation — interpreting recent moves
The competitive topology is a mix of diversified photonics suppliers, specialist SLED vendors, and agile start-ups focused on spectral engines. Notable players include established component houses and innovators offering both stock and custom fiber-coupled SLED sources. Recent corporate activity underscores two simultaneous dynamics: strategic consolidation among scale players, and capability-driven partnerships targeting high-value applications such as OCT.
-
Portfolio expansion: Strategic acquisitions and partnerships—highlighted by moves to broaden photonics portfolios and co-develop OCT-focused SLED sources—signal that access to combined optical subsystems and integration capabilities is a priority for market leaders.
-
Innovation-driven entrants: A cohort of specialist firms is commercializing ultrawide-spectrum optical engines, multi-SLED modules and tunable broadband sources. Their ability to deliver differentiated spectral characteristics and tighter system integration can outcompete commodity diode suppliers on total system value.
-
Concentration insight: Market concentration measurements show the top three vendors controlling a meaningful slice of the market while the top five raise that share noticeably—evidence of moderate concentration and an active M&A runway. For buyers and investors, that means predictable supplier selection environments but also opportunities to consolidate value through targeted acquisitions.
What PW Consulting’s full report delivers (practical, executable content)
-
Granular market model: A reproducible forecasting model (2026–2032) with sensitivity scenarios for policy disruption, raw-material shocks and accelerated adoption cases. The public summary here shares top-line CAGR and market endpoints; the full model contains the build-up by product architecture, channel and end-use.
-
Competitive playbooks: Vendor capability maps, product-differentiation matrices, and go-to-market playbooks that prioritize high-margin applications and define switching barriers for system OEMs.
-
Supply-chain stress tests: Scenario analyses that quantify the operational and P&L impact of export controls, semiconductor substrate shortages, and single-source suppliers—plus mitigation roadmaps (dual-sourcing, strategic inventories, licensing strategies).
-
M&A and partnership targets: A curated shortlist of acquisition and alliance candidates by capability cluster (broadband engines, tunable sources, integrated spectral modules), with valuations and synergy estimates modeled under three commercial cases.
-
Procurement and engineering playbooks: Tactical recommendations to trim lead time, reduce cost per system, and accelerate time-to-market—covering spec harmonization, design-for-sourcing, and post-quantum compliance checklists.
Strategic recommendations for 2026
-
Invest in spectral differentiation, not commoditization: Focus R&D and product-management resources on ultra-broadband and tunable SLED engines where integration complexity and IP can sustain premium pricing and create switching costs.
-
Operationalize supply-chain resilience: Implement multi-tier sourcing, qualify alternative wafer suppliers, and establish legally vetted sourcing protocols to navigate new licensing requirements. Build a six- to nine-month buffer for critical components during transitional regulatory periods.
-
Pursue bolt-on M&A or technology partnerships: For incumbents seeking scale, target companies with complementary optical engine technologies or software-enabled calibration services that raise total system value and lower buyer commoditization risk.
-
Adopt a value-based commercial approach: Shift from per-diode pricing to outcome-based offers (e.g., calibrated spectral engines, service-level guarantees for OCT systems) to capture more of the system integration value.
-
Embed regulatory scenario planning into capital allocation: Incorporate licensing timelines and potential export restrictions into investment approvals and supply contracts; stress-test business cases with conservative procurement lead times.
Conclusion and next steps
The fiber-coupled SLED market presents a compelling growth trajectory from a compositional and financial perspective, but success in 2026 will be decided by actions taken now on supply chain resilience, product differentiation, and strategic partnerships. Our full PW Consulting study decodes the microstructure beneath the macro figures—providing the granular segmentation, vendor scorecards, and scenario models necessary to make confident capital, product and M&A decisions.
For executives preparing 2026 budgets and commercial roadmaps, the core takeaways are straightforward: treat the headline CAGR and market expansion as directional impetus, but allocate resources to mitigate supply-side risk, lock in spectral differentiation, and pursue targeted consolidation where it accelerates access to high-value applications. Accessing the complete report provides the operational playbooks and data-driven build-ups that translate those strategic priorities into executable programs.
How to obtain the full analysis
PW Consulting’s comprehensive fiber-coupled SLED market study contains the detailed segmentation, vendor-level profiles, and executable recommendations necessary for board-level decisions in 2026. Contact our team to request the full report, which includes the models and supporting annexes excluded from this preview to preserve comparative advantage for subscribers and clients.
For detailed analysis of this topic, please visit the official page: Fiber-Coupled Superluminescent Light Emitting Diodes (SLED) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


