



PW Consulting: Ultrasonic Dissector Market to Reach USD 675.5M by 2032 at 10.5% CAGR

Ultrasonic Dissector Market — Strategic Outlook for 2026 Decision‑Making
As PW Consulting’s Chief Industry Analyst, I present a concise, strategy‑first briefing derived from our full Ultrasonic Dissector Market study (base year 2025, historical coverage 2020–2025, forecast 2026–2032). This briefing synthesizes the macro evolution of the market, the competitive dynamics shaping supplier advantage, and the practical levers executives must pull in 2026 to convert growth potential into defensible revenue streams.
Ultrasonic Dissector Market
Why this study matters for 2026
Ultrasonic dissector technologies—already demonstrating robust clinical utility across general surgery, gynecology and other specialties—are moving from niche adoption to scale commercial deployment. PW Consulting’s market model shows the industry expanding from USD 210.5 Million in 2020 to USD 346.6 Million in 2025, with a baseline forecast that the market will reach USD 675.5 Million by 2032 at a compound annual growth rate (CAGR) of 10.5% over the 2026–2032 period. These macros matter because they quantify not only demand growth but also the pace at which product portfolios, channel strategies and regulatory investments must accelerate.
Ultrasonic Dissector Market
For leadership teams evaluating capital allocation in 2026, the strategic value of this study is threefold:
Ultrasonic Dissector Market
- It translates market momentum into actionable growth targets calibrated to realistic adoption curves and clinical pathways.
- It flags structural risks—supply chain, regulatory, and competitive concentration—so management can pre‑empt value erosion.
- It provides a pragmatic roadmap for go‑to‑market sequencing and partnership priorities that protect margins while scaling sales.
What the full report delivers (practical, operator‑grade tools)
- Market sizing and validated growth scenarios: a base case and two alternative scenarios derived from adoption rates, reimbursement sensitivity, and device substitution dynamics.
- Methodology transparency: raw assumptions, data sources, and a reproducible bottom‑up model calibrated to historical 2020–2025 performance and key event timelines.
- Commercial playbooks: segmented GTM approaches for integrated hospital systems, ambulatory surgical centers, and robotics OEM partnerships—complete with sales force staffing models and expected ramp timelines.
- Regulatory and reimbursement matrix: country‑level filing strategies, dossier requirements, and timelines to expected market access (base year 2025 regulatory landscape incorporated).
- Supply chain and margin stress tests: vendor dependency mapping (notably piezoelectric transducer exposure), alternate supplier options, and contingency cost models.
- Competitive benchmarking and M&A heatmap: capability gaps, likely consolidation targets, and takeout valuation ranges under multiple integration scenarios.
- Investment memo templates and board‑ready slide decks: concise materials to support 2026 funding rounds, partnership negotiations, or internal capital approvals.
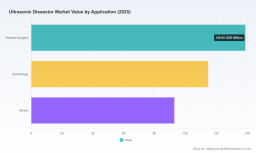
Note: this preview intentionally omits granular segmentation figures (regional and application splits) to preserve the commercial value of the full dataset available in the complete report.
Market dynamics shaping strategy in 2026
- Robust demand trajectory. The market’s multi‑year growth (CAGR 10.5%, 2026–2032) supports investments in commercialization, clinical evidence generation, and selective capacity expansion. Executives should treat this as a window of opportunity to gain share before the market reaches mid‑cycle maturity.
- Concentration and competitive pressure. Top players control a meaningful share of the market (CR3 ≈ 62%; CR5 ≈ 75%). This concentration amplifies the value of differentiated clinical claims, preferred hospital contracting, and interoperable platform partnerships.
- Supply chain volatility. Component pressures—most notably on piezoelectric transducers in 2025—compressed supplier margins and pushed lead times. Companies that secured multi‑source agreements or forward contracts in 2025 found themselves better positioned in 2026.
- Regulatory complexity. Regulatory status varies by device and manufacturer; some offerings faced approval constraints in major geographies as recently as April 2026, creating uneven go‑to‑market terrain. A surgical device’s commercial trajectory now depends as much on regulatory pathway execution as on clinical performance.
Competitive landscape — what to watch
Incumbent surgical energy and device companies and fast‑maturing challengers are pursuing divergent tactics. Representative examples include:
- Medtronic (Minneapolis, MN, USA) — market credibility through established platforms (e.g., Sonicision™ curved jaw cordless systems and newer models focused on vessel coagulation). Their playbook prioritizes platform integration, global distribution scale, and post‑market evidence collection to defend share.
- Saints Sages Surgical Co., Ltd. (Shanghai Zhangjiang Science City, China) — aggressive product commercialization with the SanAgile Ultrasonic Dissector System launched at SAGES 2025. Their strategy emphasizes cost competitiveness, OEM supply agreements, and leveraging regional manufacturing advantages.
- CMR Surgical — expanded energy offerings by adding an ultrasonic dissector to its Versius Plus portfolio (product launch December 2024), signaling a strategy of surgical system OEMs integrating proprietary energy tools to lock in clinical workflows.
Implication: incumbents will double down on platform depth and global access; challengers will lean on price and rapid local adoption. For 2026 strategic planning, it is imperative to map which competitors are likely to pursue price‑based penetration versus capability‑based differentiation.
Actionable recommendations for 2026 executives
- Prioritize regulatory readiness and modular filings. Given uneven approval status across geographies, structure regulatory programs that allow phased market entry—start with jurisdictions offering faster review and scalable reimbursement, while preparing dossiers for larger markets.
- Hedge supply‑side risk now. Lock supplier agreements or qualify alternate transducer sources. Even modest price pressure on a critical BOM item can erode gross margin rapidly as volumes scale.
- Invest in targeted clinical evidence. Build a 12–24 month evidence plan emphasizing endpoints that purchasers care about: OR time savings, device‑driven reduction in thermal spread, and improved patient throughput. Real‑world evidence tied to cost per case will accelerate hospital adoption.
- Choose GTM partners strategically. For firms without an installed surgical systems channel, prioritize partnerships with robotics OEMs and ISV integrators; for incumbents, invest in reseller and direct hospital contracting where lifetime revenue from disposables justifies initial discounts.
- Adopt a two‑track pricing strategy. Use premium pricing for differentiated, evidence‑backed offerings and targeted lower‑price SKUs for high‑volume sites where procurement is price sensitive.
- Scan M&A selectively. With the market reasonably concentrated, bolt‑on acquisitions that fill capability gaps (clinical evidence, disposables manufacturing, regional distribution) can accelerate scale more predictably than greenfield expansion.
Risk map and mitigation
- Regulatory delays. Mitigation: staggered filings; expedited clinical protocols; engage payers early.
- Component shortages & input price rises. Mitigation: dual sourcing, strategic inventory, and pass‑through pricing clauses.
- Competitive price pressure. Mitigation: differentiate via integrated platforms, bundled service contracts, and outcome‑linked pricing pilots.
- Reimbursement uncertainty. Mitigation: health‑economics models demonstrating total cost of care improvements and targeted negotiations with high‑volume accounts.
How to use this study in board and investor conversations
The full PW Consulting report converts market growth metrics into investment grade narratives. Prepare three slide decks from the study for 2026 stakeholders:
- Investment thesis: emphasize TAM growth, runway to scale, and defensibility via regulatory and clinical moats.
- Commercial blueprint: show phased market entry, expected ROI on clinical studies, and break‑even scenarios under conservative adoption curves.
- Risk & mitigation playbook: quantify impact of supply and regulatory shocks and present contingency costs and timing.
Closing — the strategic choice for 2026
We are at an inflection point. The Ultrasonic Dissector market has moved beyond early adopter dynamics into a phase where clinical proof, distribution muscle, and supply resilience will determine the winners. With the market more than doubling from mid‑cycle levels in the coming decade under our base case, 2026 is the year to convert intent into irreversible capability: secure supplies, accelerate filings, and field the clinical data that turns preference into procurement.
For a full breakdown of segmentation, regional demand curves, and downloadable models (including the interactive scenario dashboard and board‑ready investment memos), consult the full Ultrasonic Dissector Market report. The detailed segment matrices and company‑level data are intentionally reserved for the report to preserve their commercial utility.
For detailed analysis of this topic, please visit the official page: Ultrasonic Dissector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


