



PW Consulting: Coke Market to Reach USD 357.54 Million by 2032, 3.5% CAGR

Coke Market 2026: A Strategic Preview for Boardroom Decisions
As Senior Strategy Advisor and Lead Industry Analyst at PW Consulting, I present this executive preview of our Coke Market 2026 research. The aim is to surface the precise strategic choices that will matter to leadership teams in 2026, while reserving the granular segment-level data for the full report. This “trailer” highlights the study’s diagnostic depth, decision-ready frameworks, and the key risk/return levers that should drive allocation of capital, commercial priorities, and operational programs over the coming planning cycle.
Coke Market
Headline market signal
The Coke Market demonstrated consistent expansion through the early 2020s, increasing from roughly USD 218 million in 2020 to USD 285 million in the base year 2025. Our forecast models project a continuation of steady growth at a 3.5% compound annual growth rate across the 2026–2032 horizon, taking the market to approximately USD 358 million by 2032. That trajectory reflects a maturing category with structural tailwinds—population and income growth in selective markets, product portfolio innovation, and resilient branded demand—tempered by persistent margin pressure from packaging and commodity cost volatility.
Coke Market
Why this research matters to 2026 decision-makers
-
Portfolio prioritization: The report isolates which product-format-investment combinations are likely to deliver step-change returns versus those that primarily defend share. For management teams balancing innovation funding and cost rationalization, the difference is material to IR messaging and capital allocation.
Coke Market -
Channel and SKUs strategy: With varying recovery patterns across off-premise, foodservice, and convenience channels, our frameworks guide SKU rationalization, pack-size optimization, and channel-specific promotional tactics to improve gross margin per point of distribution.
-
Packaging and sustainability investment planning: Given increasing regulatory and customer scrutiny, the research lays out an actionable roadmap for packaging redesign, rPET targets, and recycling partnerships—prioritized by payback and regulatory exposure.
-
Supply chain and commodity risk mitigation: Scenario-ready cost curves and hedging playbooks address aluminum, PET, CO2, and sweetener risk—helping procurement and finance leaders stress-test budgets and set rolling hedging policies.
-
M&A and bottler engagement: We map where capacity gaps, distribution whitespaces, or adjacent product capabilities could be closed faster through targeted deals or strategic partnerships with independent bottlers.
Market dynamics shaping strategic choices
-
Regulatory pressure and labeling: Jurisdictions are advancing taxes, mandatory front-of-pack disclosures, and limitations on added-sugar products. These measures create asymmetric impact across flavor and pack formats and will force faster portfolio reformulation and labeling investments.
-
Packaging cost and tariffs: New tariffs and commodity swings materially increase unit packaging costs. Our models show that even modest tariff-driven uplifts can compress category EBIT unless offset by pack redesign, sourcing diversification, or price architecture changes.
-
Consumer price sensitivity: Elevated inflation has increased price elasticity in many consumer cohorts, accelerating downtrading to value formats and private label in price-sensitive channels. Pricing architecture and promotion discipline will be decisive for 2026 gross margins.
-
Sustainability as a commercial filter: Leading bottlers and brand owners are converting sustainability commitments (e.g., rPET targets, recyclable-by-design packaging) into sourcing and merchandising advantages. Early movers capture retailer shelf premium and reduce regulatory tail risk.
-
Distribution complexity: The Coca‑Cola system delivered extensive unit case volume in 2025, underscoring the strategic importance of bottler relationships. Independent bottlers remain critical control points for execution, innovation trials, and local pricing tactics.
Competitive landscape — concentration and strategic posture
The Coke Market is concentrated, with top firms commanding the majority of channel accessibility and brand equity. This concentration creates both barriers to entry and tactical windows: established players benefit from scale in procurement and route-to-market, while nimble independents can pilot packaging or pricing models faster at a regional level.
-
The Coca‑Cola Company (Atlanta) remains the architectural brand owner, licensing concentrates and orchestrating global marketing. Its system-wide unit case volume in 2025 underscores its leverage over national and cross-border distribution.
-
Large bottlers—such as Coca‑Cola FEMSA, Coca‑Cola Europacific Partners, Coca‑Cola HBC, Arca Continental, and Swire Coca‑Cola—operate as semi-autonomous commercial engines. They balance local execution with adherence to global brand rules, and they are primary vectors for innovations and packaging pilots.
-
Recent initiatives illustrate strategic priorities: mini-can expansion into convenience stores, recyclable multipack trials replacing plastic film with glue-dots and cardboard handles, and progress toward design-for-recyclability and rPET content targets. These examples reflect a dual focus on convenience-led growth and sustainability-driven cost avoidance.
Practical contents of the full report (what you will unlock)
-
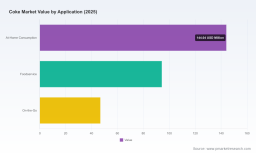
Segmented demand and supply forecasts by region, flavor and application with scenario variants and elasticities (note: detailed segment tables and numeric splits are available in the full study).
-
Price and margin sensitivity models with commodity pass-through mechanics and recommended hedging thresholds for procurement.
-
Competitive playbooks for brand owners and bottlers: commercialization sequencing, co-investment templates, and pilot evaluation scorecards.
-
Packaging optimization library: design options, estimated capex and opex impacts, and retail shelf implications—ranked by payback and regulatory alignment.
-
Regulatory and tariff impact matrix with near-term compliance priorities and longer-term policy watchlist to be monitored by government affairs teams.
-
M&A opportunity map and valuation multiples by strategic rationale (capacity, distribution, category adjacency), plus integration checklists focused on cost synergies and route-to-market uplift.
-
Practical templates: executive dashboards, GTM test protocols, and a 12–36 month implementation roadmap customized for enterprise, bottler and retail partners.
Actionable strategic implications for 2026
-
Rebalance SKU portfolios toward high-margin, sustainability-aligned formats. Short-term SKU pruning should free investment for scalable pack innovations that reduce per-unit material intensity.
-
Lock in packaging supply through multi-year agreements and diversified sourcing to blunt tariff and commodity shocks; consider indexed pass-through clauses that protect margin while maintaining competitiveness.
-
Coordinate with key bottlers on joint pilots: speed-to-market for mini and convenience formats, retailer pack innovations, and shared sustainability investments deliver asymmetric advantage at lower cost.
-
Embed consumer price sensitivity analytics into promotion planning: shift from broad discounting to targeted, measurable promotions that protect base price architecture.
-
Operationalize sustainability claims: set near-term, verifiable targets (e.g., percentage rPET, recoverability by design) and align procurement and packaging teams to ensure claims translate to lower regulatory and reputational risk.
-
Prepare M&A and partnership playbooks: use the report’s opportunity map to prioritize acquisitions or alliances that fill distribution gaps, add cold-chain capacity, or acquire adjacent beverage competencies.
How to use this preview in your 2026 planning cycle
Use the insights here to focus your Board and Executive team conversations—identify which operational levers to stress-test in your 2026 budget process. The full report converts each high-level recommendation into executable steps with financial implications, scenario-tested outcomes, and a prioritized implementation timeline suitable for a Q1 strategic review.
Closing and next step
This preview is intentionally selective: it surfaces the market trendline, competitive dynamics and the decision levers that matter most in 2026, while reserving the segmented forecasts and granular commercial matrices for the full PW Consulting report. For teams making capital allocation, pricing and sustainability trade-offs this year, the complete study provides the detailed data and the ready-made operational frameworks required to convert insight into measurable outcomes. Contact PW Consulting to access the full Coke Market 2026 study and the accompanying implementation toolkits.
For detailed analysis of this topic, please visit the official page: Coke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


