



PW Consulting: AFM Probe Market Poised for 7.85% CAGR Through 2032

AFM Probe Market 2026 Strategic Preview — What C‑Suites Need to Know
Executive snapshot
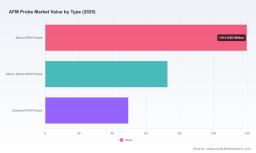
Atomic force microscope (AFM) probes are a foundational consumable across semiconductor R&D, materials science and an expanding set of life‑science applications. Our latest PW Consulting preview, anchored on a 2025 base year and a historical window spanning 2020–2025, shows a market that expanded from roughly USD 179.3 Million in 2020 to USD 242.0 Million in 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of 7.85% through the 2026–2032 forecast window — reaching approximately USD 405.0 Million by 2032. The market displays high concentration at the top (CR3 ≈ 72.5%, CR5 ≈ 88.0%), a factor with immediate strategic consequences for supply, pricing and M&A planning in 2026.
AFM Probe Market
Why this report matters for 2026 decision cycles
-
Procurement and supply‑chain resilience: Growth and concentration create both supply risk and leverage. Buyers must decide whether to centralize spend with incumbent leaders to secure priority manufacturing capacity or to diversify across smaller niche suppliers to reduce single‑source exposure.
AFM Probe Market -
Product roadmap and R&D prioritization: The market’s steady CAGR and technology trajectory mean investments in probe design (e.g., wear‑resistant coatings, ultra‑sharp tips, liquid‑compatible bioprobes) will likely yield compounded returns through higher ASPs and differentiated applications.
AFM Probe Market -
M&A and strategic partnerships: High concentration combined with targeted capability gaps (e.g., ultra‑high purity electrical probes, bespoke biological probes, diamond‑coatings) creates fertile ground for bolt‑on acquisitions and exclusive supply agreements.
-
Commercial models and pricing: Consumable economics and the absence of direct reimbursement pathways for probes (they are consumables within capital AFM systems, not billable items) force suppliers to focus on value‑added features, subscription and bundled instrument‑consumable models.
What the PW Consulting AFM Probe study delivers (practical deliverables)
-
Top‑level market sizing and validated growth trajectories (2020–2025 historical; 2026–2032 forecast) with scenario-driven sensitivity to price declines, substitution and volume expansion.
-
Technology and product roadmap that maps probe types (including wear‑resistant and diamond‑coated tips, high‑aspect ratio probes, and soft contact probes for liquids) to likely application adoption curves.
-
Supplier capability benchmarking: factory capabilities (e.g., clean‑room nanofabrication, in‑house R&D), product line breadth, specialty materials expertise, and distribution reach — actionable for sourcing RFPs and partner selection.
-
Supply‑chain risk heat map covering critical inputs (e.g., high‑purity platinum, platinum‑iridium alloys, diamond coatings, specialized carbon whisker structures), single‑point failure exposures and mitigation levers, including inventory and dual‑sourcing strategies.
-
Commercial playbooks: pricing frameworks, channel strategies, and procurement templates calibrated for 2026 negotiation cycles and CAPEX refresh plans.
-
M&A and partnership candidate shortlists, including rationale tied to capability gaps, integration risk and likely deal multiples in a highly consolidated sub‑market.
-
Regulatory and operational guidance for life‑science adoption: practical notes on liquid environment compatibility, handling protocols and lab infrastructure considerations that reduce integration friction for biological imaging programs.
Competitive landscape — who matters and why
The industry is dominated by a small set of specialist providers and several focused niche players. The full report contains a detailed vendor scorecard; here we surface strategic positioning and capability signals that matter to corporate buyers and investors.
-
Bruker Corporation (Billerica, MA): Operates vertically integrated nanofabrication capacity (Class‑100 clean rooms) and a broad portfolio spanning performance and value probes — a natural counterparty for customers seeking scale, consistency and integration with AFM instrument platforms.
-
NanoWorld AG (Neuchâtel): A leader in high‑precision cantilevers and probes, with a strong orientation toward biological and life‑science imaging — making them a go‑to for labs moving toward living‑cell AFM workflows or high‑speed liquid imaging.
-
NANOSENSORS™ (Switzerland): Specializes in probes optimized for low thermal drift and biological applications, including soft tapping and rounded tips for cell imaging — a supplier to watch for customers prioritizing delicate sample interaction and repeatability.
-
Adama Innovations (Israel): Focused on diamond‑coated, wear‑resistant ultra‑sharp tips, addressing high‑resolution topography and conductive imaging needs — attractive for customers with heavy throughput or abrasive sample sets.
-
NuNano Ltd. (UK): Provides bespoke silicon probes via direct channels and partners; their expanded distribution agreements (notably added SPARK series to major instrument eStores in 2024) broaden access to specialized probe types.
-
Rocky Mountain Nanotechnology (Utah): Niche specialist in ultra‑high purity platinum and platinum‑iridium probes for electrical modes and nanoprobing — a critical upstream supplier for high‑precision electrical AFM applications. Notably, Park Systems announced a strategic acquisition in April 2026, signaling further vertical integration in electrical probe supply.
Recent technology and commercial inflection points (selected)
-
Distribution expansion: NuNano’s 2024 distribution deal broadened access to certain silicon probe series via major instrument eStores and regional offices — an example of how channel plays accelerate adoption without immediate manufacturing scale‑up.
-
Fabrication innovation: A 2025 publication described a batch fabrication method enabling ultra‑sharp probes with novel handle geometries, indicating potential for scale‑economics improvements in high‑end probe production and a likely price‑performance squeeze over the medium term.
-
M&A: The 2026 Park Systems acquisition of Rocky Mountain Nanotechnology highlights supplier consolidation around specialty materials for electrical modes and a move by instrument OEMs to secure upstream inputs.
Market dynamics that will shape winning strategies in 2026
-
Materials and input cost sensitivity: Innovations such as diamond coatings, EBD carbon whiskers (used to create tall, sub‑2 nm tips for biological topography), and ultra‑high purity Pt/Pt‑Ir all introduce cost and sourcing considerations that influence margin profiles by probe subtype.
-
Application environment constraints: Biological AFM is increasingly performed in liquid environments with minimal sample prep. This drives demand for soft contact probes with very low force constants and fluid‑compatible geometries — suppliers who master these specifications can command preference among life‑science labs.
-
Commercial framing: Because probes are consumables within capital instruments (and not reimbursable as standalone clinical items), go‑to‑market strategies must emphasize instrument‑ecosystem compatibility, lifecycle cost and workflow integration rather than fee‑for‑service models.
-
Consolidation and access dynamics: High CR3/CR5 concentration suggests incumbents will retain pricing power for differentiated probe classes, but niche innovators and fabrication advances will periodically disrupt margins and open specialization opportunities.
Practical recommendations for corporate leaders in 2026
-
Sourcing: Implement a two‑track supplier strategy — secure capacity with top incumbents for baseline needs, while piloting secondary suppliers for specialized probes (diamond‑coated, high‑aspect ratio, bio‑optimized) to build optionality.
-
R&D alignment: Prioritize co‑development agreements for probes that reduce sample damage in liquid environments and extend tip lifetime for high‑throughput applications — these features shorten total cost of ownership and drive customer lock‑in.
-
M&A and partnerships: Target bolt‑ons that close capability gaps (e.g., ultra‑pure electrical probes, bespoke bio probes), especially where incumbents show limited focus on a growing sub‑application.
-
Commercial models: Test subscription and bundled consumable programmes with instrument sales to capture recurring revenue and reduce buyer churn; emphasize calibration standards and traceable quality as differentiators.
-
Intelligence posture: Monitor fabrication research outputs and material supply constraints closely; small advances in probe fabrication can quickly shift competitive dynamics and margin pools.
How to read this preview — and where to go next
This preview is designed as a high‑signal executive brief: it presents the macro growth trajectory, concentration metrics and strategic implications needed to inform 2026 planning cycles while intentionally withholding the granular segment‑level tables, regional splits and unit‑price decks to preserve the consultative value of the full study. The full PW Consulting AFM Probe Market report contains the operational annexes decision‑makers use to execute — including supplier scorecards, product feature matrices, segment revenue build‑ups, regional demand models and actionable playbooks for procurement, R&D and M&A.
Closing — timing and next steps
The AFM probe market is neither a niche hobby nor a commodity curtain‑call: it sits at the intersection of instrument ecosystems, material science advances and application adoption in biology and electronics. With a multi‑year CAGR approaching 8% and clear concentration among leading providers, 2026 is a hinge year for locking in supply, accelerating product differentiation and positioning for consolidation. PW Consulting’s full report converts the directional insights summarized here into executable plans — from specific supplier selection criteria to modeled ROI for co‑development and M&A — enabling leaders to move from strategy to measurable action.
For detailed analysis of this topic, please visit the official page: AFM Probe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


