



PW Consulting: Electronic-Grade H2O2 Market Set to Grow at 7.1% CAGR Through 2032

Electronic‑Grade Hydrogen Peroxide Market — Strategic Outlook for 2026 Decision‑Makers
Executive preview
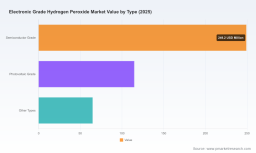
As semiconductor and advanced electronics manufacturing accelerate into a new cycle of capital investment and node migration, electronic‑grade hydrogen peroxide (EG‑H2O2) has re‑emerged as a strategically critical chemical. Our market model shows a sustained upward trajectory from the prior half‑decade into the next planning horizon, with the global market expanding from roughly USD 304 million in 2020 to about USD 429 million in the 2025 base year, and an anticipated compound annual growth rate of 7.1% through the 2026–2032 forecast window. By 2032 the market is projected to approach the high‑six‑hundreds (USD), reflecting both volume growth and ongoing premiumization driven by tighter purity specifications, localization of supply, and specialty‑grade differentiation.
Electronic Grade Hydrogen Peroxide Market
Why PW Consulting’s study matters for 2026 decisions
- Timing: 2026 is a decisive year for procurement commitments and capex schedules in semiconductor fabs built under recent public and private investment programs. Our research converts projected fab build‑outs and process node timelines into demand signals for EG‑H2O2, enabling procurement teams to time contracts and investments to avoid shortages or oversupply.
- Specification risk: SEMI and industry specifications are converging on ultra‑low metallic impurity ceilings for advanced nodes. This report translates those technical thresholds into supplier qualification checklists, contamination‑control playbooks, and risk maps that buyers and quality engineers can act on immediately.
- Supply chain resilience: With a market that is neither atomized nor monopolistic (our concentration analysis shows the top three suppliers control a material majority of capacity while the top five extend that dominance), the balance of supplier power and the fragility of local supply pockets matter. The study provides scenario modelling that quantifies the pricing and availability impact of single plant outages, raw material volatility and new regional capacity additions.
High‑level market dynamics
Demand drivers are multi‑vector: incremental semiconductor wafer area per fab, higher cleaning frequency accompanying advanced node lithography and etch processes, and differentiated product grades for display and other high‑value electronics segments. On the supply side, producers are investing in dedicated purification trains, ultra‑clean packaging, and regional plant expansions to capture customers who increasingly value nearshore supply and vendor traceability.
Electronic Grade Hydrogen Peroxide Market
Notable market mechanics that 2026 strategists must factor into decisions include: (1) the premium yield associated with certified electronic grade manufacturing—small contamination differences translate into outsized yield and earnings impact for customers; (2) regulatory nudges that favor peroxide as a chlorine‑free oxidant in both wastewater and certain process chemistries; and (3) feedstock price volatility which can compress supplier margins and drive short‑term price moves. Our modelling incorporates these levers to produce demand, price and margin scenarios under alternative regulatory and input‑cost regimes.
Electronic Grade Hydrogen Peroxide Market
Regulation, standards and their strategic implications
- Standards compliance: SEMI’s latest electronic‑grade specifications set metallic impurity limits at the sub‑ppb level for advanced node processes. Suppliers and end‑users must synchronize capability roadmaps and quality assurance protocols to meet these thresholds — non‑compliance is a revenue and reputational risk for both sides.
- Environmental policy: U.S. EPA and EU REACH policy direction increasingly favors chlorine‑free chemistries in select applications, creating structural tailwinds for peroxide adoption in certain segments of the electronics industry.
- Industrial policy: Public investment initiatives that target domestic semiconductor capacity expansion uplift local demand for EG‑H2O2 and increase the strategic value of near‑site supply. For corporate planners, this changes the calculus for greenfield versus contract manufacturing and for on‑site storage and purification assets.
Competitive landscape — what to watch in 2026
The supplier ecosystem blends global chemical majors with specialized purifiers and regional champions. Key strategic themes we identify across the competitive set are: capacity clustering with selective regional localization; technology differentiation based on purification and contamination control; and commercial models that range from long‑term offtake contracts to spot delivery and on‑site service offerings.
- Global majors with dedicated electronic‑grade portfolios have invested in purification platforms and joint ventures to secure proximity to advanced fabs. One notable example is a multinational supplier that has recently doubled nameplate capacity at a China facility and operates a joint venture in a leading semiconductor manufacturing hub — an explicit strategic move to capture regional demand and shorten lead times.
- Specialists and legacy electronic‑grade producers compete on ultra‑low contamination performance, packaging integrity, and qualification track records. Their value proposition is safety of supply for the most demanding nodes where elimination of trace metals and particulates is mission‑critical.
- Regional producers in large electronics manufacturing markets have closed the gap on quality, offering competitive sub‑ppb impurity profiles. For many fabs, qualifying a domestic supplier reduces cross‑border logistics risk and supports domestic content goals, but this requires rigorous audit and long‑term engagement.
Supply shocks, input cost sensitivity and margin pressure
Raw material and logistics costs remain a recurring operational risk. Recent commodity surveillance recorded a notable month‑over‑month rise in hydrogen peroxide pricing, and our sensitivity analysis demonstrates that short pulses in feedstock costs or packaging supply constraints can materially affect small, highly concentrated suppliers. For buyers, the implication is straightforward: contract clauses that share or mitigate input cost shocks, and diversified sourcing, will materially reduce price and operational volatility.
What the PW Consulting report delivers — practical components
Our study is structured to be directly actionable for commercial, procurement, and strategic planning teams. Core deliverables include:
- Forward‑looking demand model that translates fab build schedules, wafer starts, and process node mix into volumetric demand for EG‑H2O2 across the 2026–2032 horizon.
- Price and margin scenarios that integrate feedstock cost pass‑through, capacity utilization, and supplier concentration, with sensitivity tables for rapid executive decisions.
- Supplier scorecards and qualification matrices that combine technical performance (impurity profiles, packaging integrity), commercial robustness (delivery lead times, contract flexibility), and geopolitical exposure.
- Regulatory impact assessment that quantifies likely adoption shifts under alternative policy developments (e.g., accelerated local content rules, stricter waste discharge limits).
- Operational playbooks: procurement clauses, on‑site storage recommendations, emergency response plans for supply interruptions, and a step‑by‑step supplier qualification checklist aligned to SEMI and industry QA expectations.
- M&A and greenfield case frameworks that assess returns on capacity expansions, purification upgrades, and vertical integration into upstream peroxide production or downstream specialty mixing and packaging.
Strategic actions for 2026 — three prioritized moves
- Procurement: Move from ad hoc spot buying to a tiered sourcing strategy that secures long‑term capacity with at least two qualified suppliers per region, combined with a negotiated price escalation mechanism tied to defined feedstock indices.
- Quality & operations: Invest in supplier audits and on‑site qualification wells to shorten the qualification timeline for alternative suppliers. For wafer fabs, even small improvements in contamination control can justify the incremental cost of premium supply.
- Portfolio & corporate development: Evaluate minority equity stakes or offtake agreements with high‑quality regional producers that demonstrate robust purification capabilities. Where strategic, consider co‑funded capacity expansions that lock supply and share capital risk.
Use cases: who benefits from the report
- Chief Procurement Officers — for structuring contracts, hedging strategies, and pool sourcing approaches.
- Head of Manufacturing/Quality — for aligning supplier qualification to process node timelines and contamination budgets.
- Corporate Development and Strategy teams — for identifying M&A targets, JV partners, and capex partnering opportunities.
- Policy and sustainability teams — for assessing regulatory risk and planning transitions to greener chemistries.
What we intentionally withhold here — and why
This preview emphasizes the shape of the opportunity and the high‑level quantitative framework without disclosing the proprietary, granular split data and scenario tables that underpin supplier‑level decisions. The report intentionally reserves detailed regional and application‑level revenues, individual supplier volumes, and the full sensitivity matrices for subscribers, because those granular inputs are the core commercial intelligence companies use to reprice supply and adjust capital plans.
Closing perspective
Electronic‑grade hydrogen peroxide sits at the intersection of chemical purity engineering, regional industrial policy, and semiconductor manufacturing economics. For 2026, decisions around supplier selection, contract tenor, local capacity, and contingency planning will determine whether firms capture steady, low‑volatility supply or are exposed to episodic price and availability shocks. PW Consulting’s study synthesizes technical standards, regulatory momentum, supplier investments, and demand modelling into an operational playbook. The top‑line market growth and concentration metrics point to opportunity — but the decisions that protect yield and margin depend on the granular intelligence contained in our full report.
To convert this strategic preview into executable plans for procurement, quality assurance, and corporate development, the full research package provides the necessary segmental detail, supplier scorecards and scenario modelling that senior teams will use to finalize 2026 commitments.
For detailed analysis of this topic, please visit the official page: Electronic Grade Hydrogen Peroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


