



PW Consulting: 1-Octene Market Set to Reach USD 297.7M by 2032 at 5.12% CAGR

1-Octene Market: Strategic Preview for 2026 Decision-Makers
The 1-octene market sits at an important inflection point as we enter 2026. After steady expansion through the early 2020s, the market has demonstrated resilient end‑market demand and improving technology-driven supply economics. PW Consulting’s upcoming 1-Octene Market study synthesizes historical performance and forward-looking scenarios to help corporate strategists, commercial teams, and investors convert macro trends into concrete near‑term choices that will define competitive position across the 2026–2032 planning window.
1-Octene Market
Market snapshot: what the headline numbers tell you
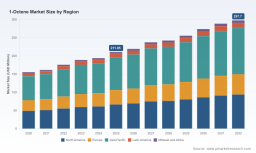
Between 2020 and 2025 the global 1-octene market experienced multi-year growth driven primarily by polyethylene comonomer demand and continued adoption in surfactant and specialty lubricant applications. Our compiled market totals show clear expansion during the base period, and the outlook indicates continued enlargement through the forecast horizon. The market is projected to grow at a compound annual growth rate (CAGR) of approximately 5.12% during the 2026–2032 forecast period, reaching a materially larger scale by 2032.
1-Octene Market
Two strategic takeaways flow directly from these macro dynamics. First, steady volume growth combined with moderate concentration (market-share metrics indicate a fragmented supplier base) creates opportunities for differentiation through technology, cost position and service model rather than purely through scale. Second, the pace of growth supports targeted capacity additions and partnerships—but timing and location will determine whether new entrants capture premium margins or face a commoditizing supply environment.
1-Octene Market
Why this report matters for 2026 corporate decisions
-
Investment prioritization: Our analysis translates market growth trajectories into demand buckets and stress-tested scenarios to evaluate the business case for brownfield expansions, debottlenecking, or greenfield projects within a 36–60 month execution window.
-
Procurement and feedstock strategy: With ethylene remaining the dominant upstream feedstock, the study maps feedstock exposure and shows how contracting structures (long‑term vs. index-linked) alter margin profiles under several oil/ethylene price scenarios.
-
Technology & differentiation: The report benchmarks catalytic and oligomerization technologies—identifying which process innovations deliver step-change cost, yield, or sustainability advantages important for 2026 supplier selection and partnership decisions.
-
Regulatory and operational readiness: Practical guidance on handling and transport, industry regulatory context (including food-contact listings where relevant), and product stewardship obligations that influence logistics design and commercial risk.
What’s inside: actionable modules in the full study
-
Concise market model (historical 2020–2025 and detailed forecast 2026–2032) with scenario toggles for demand shocks, feedstock volatility and new capacity.
-
Commercial playbook: routes to market by customer segment, margin pools across the value chain, and go‑to‑market templates for upstream and merchant producers.
-
Technology deep-dive: technical comparisons of oligomerization platforms, catalyst systems and emerging bio‑derived routes; CAPEX/OPEX benchmarking for greenfield and retrofit options.
-
Regulatory and safety annex: consolidated references to food contact regulation status, transport/handling updates and SDS considerations that affect logistics and insurance.
-
Competitive landscaping and deal flow tracker: profiles of major producers, recent announcements and an assessment grid for M&A or JV targets.
Competitive landscape: who matters and why
The supplier landscape for 1-octene is characterised by a mix of global diversified chemicals majors, specialist olefin producers and regionally focused complexes. Market concentration metrics point to a low-to-moderate degree of dominance by the top suppliers, leaving room for strategic moves that change relative position without necessarily requiring absolute scale.
-
Chevron Phillips Chemical Company LP (Houston): A longstanding supplier with branded offerings for linear alpha olefin comonomer markets. Recent product stewardship updates and transport guidance underscore the importance of operational rigor—an important consideration for buyers seeking predictable logistics and risk management.
-
SABIC (Riyadh): Deploys proprietary low-pressure oligomerization technology with integrated value chain advantages in regions where feedstock integration delivers cost benefits; a natural strategic partner or competitor depending on regional positioning.
-
Shell (The Hague): Combines integrated petrochemical platforms with active catalyst partnerships—an approach that accelerates low‑carbon and bio‑derived pathways and is likely to shape medium-term supply options for sustainability‑minded customers.
-
INEOS (London): Plays across linear alpha olefin portfolios and can leverage flexible commercial structures to serve specialty and polymer markets where technical service differentiates pricing.
-
Sasol (Johannesburg): Maintains unique production routes that can be relevant in specific regional feedstock or energy contexts; companies with non‑standard upstream linkages should study the supply implications closely.
-
ExxonMobil Chemical (Irving): Recent announcements highlight catalytic process innovations that aim at higher yield and lower energy intensity—technology that can alter cost and emissions equations for licensees and integrated producers.
Recent disclosed moves underline two themes: (1) incremental technology and catalyst developments that improve yield, energy use and impurity profiles; and (2) capacity additions in Asia intended to feed regional polyethylene demand. Both dynamics increase the importance of timing—first movers on catalyst partnerships or process upgrades can capture margin uplift, while late movers may face a more price‑competitive environment.
Market dynamics and risk factors to watch in 2026
-
Feedstock volatility and integration risk: Ethylene remains the primary upstream input. Firms with favourable ethylene access or hedging strategies will enjoy structural cost advantage; purchasers without vertical integration should consider hybrid sourcing strategies.
-
Regulatory clarity and product stewardship: 1‑Octene’s status in food contact regulations is established in key jurisdictions; no material reclassifications were recorded in 2024–2025. However, transport and handling guidance continues to be refined by suppliers and will influence logistics costs and incident exposure.
-
Capacity build in Asia and regional imbalances: Announced capacity expansions in major Asian complexes change the forward supply curve—buyers and investors must model regional flow economics rather than relying solely on headline global demand growth.
-
Technology and sustainability transitions: Catalyst partnerships and bio‑sourcing initiatives are moving from pilot to commercial scale. These developments introduce new competitive dimensions—life‑cycle emissions and feedstock origin will increasingly affect offtake terms with large polymer and consumer-facing customers.
Strategic playbook for 2026
-
For producers: Prioritise selective capital allocation—focus on retrofit projects and catalyst licenses that improve yield or lower energy intensity, rather than undifferentiated greenfield capacity. Evaluate tolling and merchant models to fill plant utilisation gaps quickly.
-
For polymer and surfactant manufacturers: Secure flexible offtake contracts with logical indexation and clause structures that share upside and downside with suppliers. Invest in upstream partnerships to access differentiated 1‑octene grades aligned to product performance needs.
-
For investors and PE: Target assets with demonstrable feedstock integration, proprietary technology or service‑differentiated commercial models. Beware of plain-vanilla merchant plants in regions where new capacity is already announced.
-
For procurement and supply chain leaders: Re-examine logistics routes and safety protocols in light of updated SDS and transport guidance. Scenario‑test supply interruptions and incorporate transport liability into supplier scorecards.
How to use the full PW Consulting report
This article is a strategic preview designed to orient your 2026 decisions. The full PW Consulting 1-Octene Market report provides the granular models, supplier scorecards, techno‑economic comparisons and scenario tables you need to execute with confidence. If your 2026 plan includes capacity planning, technology licensing, regional sourcing changes, or M&A, the full study supplies the primary data and decision templates to convert our insights into executable investments.
Conclusion: a pragmatic edge for 2026
In a market characterised by steady growth, technological change and regional capacity shifts, 2026 will reward organisations that pair macro awareness with tactical precision—those who align feedstock strategy, select differentiated technology partners, and hard‑wire logistics resilience into commercial contracts. PW Consulting’s 1-Octene Market study is structured to give you both the high‑level view and the operational detail needed to make those calls while preserving the market granularity and supplier intelligence that can only be accessed in the full report.
To move from strategic intent to execution-ready decisions, access the complete study for scenario models, supplier matrices and the appendices that operationalise the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: 1-Octene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


