



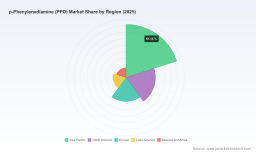
PW Consulting: PPD Market to hit USD 737.5M by 2032 at 4.75% CAGR; Asia Pacific $221.19M

p-Phenylenediamine (PPD) Market Outlook 2026: Strategic Imperatives for Corporate Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise but deep preview of our p-Phenylenediamine (PPD) Market research — a tactical guide for boards, corporate strategy teams, and commercial leaders preparing decisions in 2026. The PPD value chain sits at the intersection of specialty chemicals, consumer personal care, and industrial elastomers. Our 2025 base-year study and forward-looking model to 2032 combine quantitative trend projection with decision-grade, operational diagnostics. Below we summarize the strategic takeaways and the practical modules inside the full report, while intentionally withholding proprietary segment-level tables to invite a closer read of the full intelligence pack.
p-Phenylenediamine (PPD) Market
Why PPD matters for 2026 corporate strategy
PPD is a small-molecule intermediate with outsized commercial sensitivity. Its end-uses — hair dyes, textile dyes, rubber processing, photographic and various industrial intermediates — expose manufacturers and buyers to a mix of consumer-regulatory risk, feedstock cost volatility, and concentrated supply. From a capital allocation and commercial planning perspective, three attributes make PPD a 2026 priority:
p-Phenylenediamine (PPD) Market
- Predictable baseline growth: Our model uses a 2025 base and projects a compound annual growth rate (CAGR) of 4.75% across the forecast horizon, driven by continued demand in hair dye and rubber-processing segments alongside steady industrial applications.
- Feedstock sensitivity: PPD manufacturing is materially exposed to aniline and benzene feedstocks and shows meaningful margin swings tied to short-term raw material dynamics and logistics constraints.
- Regulatory asymmetry: Recent regulatory initiatives and proposals — from tightened chemical handling and emissions oversight to proposed limits on PPD concentration in colorant formulations — create uneven demand impacts across geographies and applications.
Headline market sizing (high level)
Using 2025 as the base year, the total PPD market is quantified in our model and shows expansion over the forecast period. The market trajectory captures post‑pandemic recovery dynamics, the impact of regulatory measures, and structural shifts in end‑use demand. The headline statistics — which we disclose publicly to orient executive planning — show mid‑single-digit CAGR growth and a materially larger market by the end of the forecast window. For the full, interactive model (country-level demand curves, price scenarios, and unit economics), please consult the complete report page.
p-Phenylenediamine (PPD) Market
Competitive landscape and what it means for strategy
The global PPD supply base blends regional champions, specialty players and diversified chemical majors. Market concentration at the top end is moderate: the three-largest producers account for a meaningful share of supply, and the five-largest firms control a clear majority. This structure creates both competitive risk (capacity-driven price cycles) and opportunity (strategic partnerships with leading producers).
- Aarti Industries and select Indian specialty players are executing capacity and quality upgrades with enhanced safety and ESG credentials; these moves strengthen their position in premium and regulated markets.
- Large chemical groups and East Asian volume producers continue to emphasize cost leadership and integrated feedstock sourcing; capacity investments in high‑purity grades support textile and rubber intermediates at scale.
- Recent strategic transactions and targeted facility investments by diversified global players signal consolidation of higher‑margin specialty lines and vertical integration to control feedstock and technical know‑how.
For commercial teams, the implication is straightforward: supplier selection must account for capacity elasticity, regulatory compliance history, and the ability to provide formulation support under tighter chemical limits. For M&A and corporate development, look for bolt-on targets that expand technical grade ranges and regulatory-compliant production footprints.
Regulatory & raw-material dynamics to watch in 2026
- Heightened safety and emissions oversight in major producing countries is raising compliance costs and restricting storage/transport flexibility. Companies with modernized facilities and documented environmental management systems gain a sourcing advantage.
- Feedstock markets are showing renewed firmness, with price spikes and logistics tightness driving cost pass-through challenges. Buyers should expect periodic, multi‑week price dislocations and plan hedging or contracting strategies accordingly.
- Regulatory proposals in consumer markets — including efforts to reduce allowable PPD levels in dye formulations — could compress demand for technical PPD in specific geographies and products. Firms must model both compliance costs and potential product reformulation timelines.
- Sub‑national regulatory attention (e.g., candidate chemicals lists and public comment processes) introduces geographic unpredictability for derivative products; legal and regulatory monitoring should be elevated to board reporting frequency.
What our full report contains — decision‑grade deliverables
The PW Consulting PPD Market report is intentionally practical. We organize findings into modules that feed directly into 90–180 day action plans and three‑to‑five‑year capital allocation decisions. Key deliverables include:
- Interactive market model (2020–2032) with scenario toggles: base, regulatory‑constrained, high‑raw‑material, and accelerated substitution. Users can re-run demand and margin forecasts by changing price, regulation and capacity inputs.
- Supply‑side heatmaps and plant‑level benchmarking showing safety, emissions, and ESG risk scores — enabling rapid supplier triage without disclosing proprietary segment numbers in this preview.
- Raw material sensitivity and pass‑through frameworks: quantitative rules-of-thumb and contractual clauses for price escalators, minimum purchase commitments, and feedstock sharing arrangements.
- Regulatory impact matrices with pathway maps for product reformulation: practical steps and CAPEX estimates required to comply with evolving hair-dye thresholds and chemical handling rules.
- Commercial playbooks for producers and buyers: pricing architecture options (indexation vs fixed), channel segmentation strategies, and technical services that create differentiation in commoditized markets.
- M&A and partnership shortlist: evaluated targets and JV structures prioritized by strategic fit, deliverable synergies, and integration risk (available in full report annexes).
- Stress tests and downside scenarios: tailored guidance for contract portfolios, inventory strategies, and contingency logistics planning under acute supply shocks.
Competitive moves we are monitoring
Several vendor actions over the past two years crystallize likely market outcomes. Capacity upgrades with modern environmental safety systems, strategic acquisitions into specialty intermediates, and facility investments on quality expansion trajectories are all visible. Sustainability credentials — including recognized third‑party supplier ratings — are emerging as differentiators for buyers in regulated consumer markets. These developments reframe procurement from price-only conversations to integrated supplier risk management.
Actionable recommendations for 2026
- Prioritize supply‑security contracts with clauses for regulatory contingency and feedstock pass-through; consider diversified multi‑sourcing to mitigate regional regulatory or logistical shutdowns.
- Accelerate product‑level compliance roadmaps for consumer-facing formulations where regulatory thresholds are under evaluation. Early reformulation pilots reduce risk and create first‑mover marketing advantages.
- Incorporate ESG and safety benchmarking into supplier scorecards; allocate incremental spend to suppliers with verified modernized facilities if regulatory risk is material for your end markets.
- For producers: deploy a dual product strategy — cost-competitive volume grades for industrial channels and premium, high‑purity grades with value‑added technical support for cosmetics and specialty dyes.
- M&A teams: prioritize assets that expand high‑purity capacity, regional compliance footprints, or technical service capabilities rather than simple volume additions.
How executives should use the full PW Consulting report
Executives should treat the full PPD report as a toolkit: a live market model for quarterly planning, a supplier‑risk playbook for procurement, and a strategic dossier for M&A committees. The report enables scenario rehearsals — from short, sharp raw material surges to multi-year regulatory transitions — and translates those scenarios into prioritized actions with estimated timelines and resource implications.
Final note — where this preview intentionally stops
This introduction deliberately demonstrates methodological rigor and strategic focus while withholding granular regional and application-level splits, unit price curves, and facility-level capacities contained in the full intelligence pack. Those detailed tables and the interactive model are core intellectual property: they are the operational inputs you will need to execute with confidence in 2026.
To obtain the complete market model, plant-by-plant benchmarking, prioritized M&A shortlist, and the regulatory compliance playbook, please visit our report page or contact PW Consulting directly. Our team stands ready to run bespoke scenario workshops with your executive and procurement teams to turn these insights into executable plans.
For detailed analysis of this topic, please visit the official page: p-Phenylenediamine (PPD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


