



PW Consulting: Ambulatory Cardiac Monitoring Market to Reach USD 9,370M by 2032 at 8% CAGR

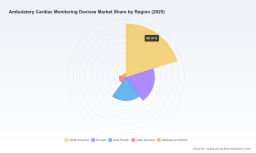
Ambulatory Cardiac Monitoring Devices Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a focused industry primer designed to orient executive teams, investors, and product leaders as they set strategy for 2026. This briefing synthesizes market dynamics, competitive positioning, regulatory and reimbursement headwinds, and practical go-to-market imperatives drawn from our full Ambulatory Cardiac Monitoring Devices Market study. It offers the strategic context you need now — and signals where the full report delivers the granular intelligence required to act with confidence.
Ambulatory Cardiac Monitoring Devices Market
Why 2026 is a Pivotal Inflection Point
The ambulatory cardiac monitoring market is transitioning from device-centric sales toward platform-driven services that combine wearable hardware, cloud analytics, and integrated clinical workflows. The base year for our study is 2025; the forecast window opens in 2026 and runs through 2032. This boundary matters: decisions made in 2026 about product design, reimbursement strategy, and channel investments will determine whether companies capture the high-growth opportunities we identify for the second half of the decade.
Ambulatory Cardiac Monitoring Devices Market
Strategically, 2026 is when several technology and policy vectors converge: freshly-cleared devices and software reach scale, payer audit programs intensify around bedside-to-cloud care pathways, and health systems accelerate adoption of remote monitoring to reduce readmissions and optimize electrophysiology workflows. The combination creates windows for market share gains, but also raises execution risk for firms lacking a calibrated reimbursement and evidence strategy.
Ambulatory Cardiac Monitoring Devices Market
Market Trajectory — The Macro View
At the macro level, the market has delivered steady expansion over the first half of the decade and is set for continued, robust growth. Our model shows the market expanding from approximately USD 3,940 million in 2020 to roughly USD 5,480 million in 2025. Under the baseline scenario, the market grows at a compound annual growth rate (CAGR) of about 8.0% during the 2026–2032 forecast period, reaching an implied market size of roughly USD 9,370 million by 2032.
Key takeaways from the macro trajectory:
- Persistent expansion validates the underlying clinical demand for extended rhythm monitoring and remote diagnostic solutions.
- Growth is driven not only by device volume, but by higher-value services — cloud analytics, AI-enabled interpretation, and subscription telemetry offerings.
- The market’s pace favors incumbents that can bundle device hardware with recurring-service revenue, while leaving niche windows for focused innovators with novel sensing modalities.
Structural Drivers and Market Dynamics
Understanding the structural forces shaping 2026 is essential for prioritizing investments. The following drivers are decisive:
- Clinical need and guideline evolution: Aging populations and guideline-emphasized arrhythmia detection increase baseline demand for ambulatory monitoring.
- Technology convergence: Advances in single-lead and multi-lead wearables, multimodal sensing (ECG, PPG, seismocardiography), and AI/ML signal processing are expanding diagnostic sensitivity while reducing clinician burden.
- Shift to service models: Payers and health systems prefer bundled, outcomes-focused solutions that integrate monitoring with interpretation and care coordination.
- Regulatory and reimbursement friction: External ambulatory monitors remain Class II devices in the U.S. under established 510(k) pathways, but reimbursement nuances — especially prior authorization requirements for mobile cardiac telemetry (MCT) — are material to commercial viability.
Two operational realities deserve particular attention in 2026:
- Coding and payer behavior: Holter monitoring codes for short-term continuous recording have entrenched reimbursement pathways; conversely, MCT codes frequently require prior authorization and face increasing documentation audits. Industry feedback and market intelligence indicate denial rates can climb substantially where authorization workflows are weak — a commercial risk that directly impacts revenue realization and margins.
- Regulatory cadence: Continued 510(k) clearances for novel sensors and software modules mean entrants can reach market faster, but post-market evidence demands and cybersecurity expectations increase lifecycle costs.
Competitive Landscape — Who Matters and Why
The industry exhibits moderate concentration: the combined market share of the top three players is meaningful, and a top-five group captures a clear majority of value. That structure yields both stability and opportunity — incumbents hold scale advantages in distribution and payer relationships, while innovative challengers can displace legacy approaches through differentiated sensing, analytics, or business models.
Representative strategic positions of core competitors — and the implications for 2026 playbooks — include:
- iRhythm Technologies — Market-leading single-lead continuous patch platform with embedded AI interpretations. Strengths: brand recognition, payer relationships, high-volume diagnostic throughput. Strategic vector: scale long-term continuous monitoring services into new geographies and care pathways.
- LifeSignals — Disposable biosensor-based Holter systems that emphasize low-friction deployment. Strengths: supply-chain focus and single-use convenience. Strategic vector: leverage sterile-dispense and workflow simplicity for urgent-care and home-based programs.
- InfoBionic — Multi-lead wireless platform cleared for Holter-style and event monitoring. Strengths: sensor modularity and clinical monitoring flexibility. Strategic vector: aim for adoption in electrophysiology clinics where signal fidelity and multi-lead data matter.
- Cardiosense and HeartBeam — Early-stage innovators with multimodal and synthesized 12-lead approaches, respectively. Strengths: novel physiologic signals and ambulatory 12-lead assessment. Strategic vector: pursue niche clinical claims and strategic partnerships with device or analytics incumbents.
- Large medtech OEMs (Philips, GE Healthcare, Nihon Kohden, Schiller, Fukuda Denshi, Hill-Rom) — Portfolio breadth across monitoring modalities and institutional channels. Strengths: global sales reach, integration into hospital IT stacks. Strategic vector: bundle ambulatory offers with enterprise telemetry and cardiac care services.
- Digital-native challengers (AliveCor, Bardy Diagnostics, VitalConnect) — Consumer and clinical hybrid models that emphasize low-cost, repeatable monitoring. Strategic vector: target outpatient cardiology and remote patient monitoring (RPM) programs through subscription and app-based channels.
Recent vendor developments — product launches and regulatory clearances across 2024–2025 — accelerate competition in both hardware innovation and regulatory-approved software. These moves lower technical barriers for late entrants but sharpen the importance of scale in data interpretation and payer engagement.
Commercial and Clinical Execution Playbook for 2026
Winning in 2026 requires aligning product, evidence, and payer strategy. Tactical priorities we prescribe for clients are:
- Design evidence-generation for reimbursement: Sponsor pragmatic clinical studies and health economic dossiers that demonstrate diagnostic yield, downstream care impacts, and potential cost offsets versus standard pathways. Time-to-publish matters — aim for early 2026 outcomes to influence payer policies.
- Operationalize prior authorization and denial mitigation: Build automated authorization workflows and dedicated payer-liaison roles for MCT products to reduce claim denials and accelerate collections.
- Productize services: Move beyond one-time device sales; package analytics-as-a-service, interpretive reporting, and clinician dashboards to create recurring revenue and higher lifetime customer value.
- Pursue selective partnerships: Leverage OEM distribution for institutional channels while forming clinical alliances with electrophysiology networks and remote patient monitoring platforms for outpatient scale.
- Invest in cybersecurity and post-market surveillance: As regulatory scrutiny and payer audits grow, demonstrated compliance becomes a commercial differentiator.
- Segment-focused go-to-market: Target high-yield clinical use cases (e.g., unexplained syncope pathways, cryptogenic stroke workups) where diagnostic yield and reimbursement align; avoid scattershot market entry that dilutes sales effort.
What the Full PW Consulting Report Delivers
Our published Ambulatory Cardiac Monitoring Devices Market study is structured to convert strategic questions into executable plans. The report includes:
- Proprietary market model and base-case/alternative scenarios calibrated to 2020–2025 historicals and 2026–2032 forecasts, with transparent assumptions and sensitivity levers.
- Regulatory and reimbursement trackers that map coding, payer policies, and audit risk across major jurisdictions — including practical guidance to de-risk reimbursement pathways for MCT and Holter offerings.
- Vendor deep dives and competitive scorecards that analyze product portfolios, evidence pipelines, pricing posture, channel strategies, and M&A likelihood.
- Commercial playbooks (sales, marketing, pricing, partnerships) tailored to incumbents, scale-ups, and early-stage innovators.
- Primary interview insights from payers, hospital cardiovascular leaders, and cardiology practitioners that illuminate adoption barriers and workflow preferences.
- Downloadable financial model and go-to-market checklist to accelerate internal planning and board-level decision-making.
In keeping with the “trailer” principle, this briefing deliberately outlines the strategic contours while reserving granular segmentation and proprietary line-item forecasts for clients who access the full research package. The complete report provides the detailed regional, product, and end-user splits, plus downloadable Excel models that support scenario testing and valuation work.
Final Strategic Prescription
Executives facing a 2026 decision horizon must balance two imperatives: invest to capture the recurring-revenue, analytics-driven opportunity — and simultaneously shore up reimbursement and compliance capabilities to protect near-term cash flow. The market’s 8.0% projected CAGR and the trajectory from 2020 through our 2025 base year confirm ample growth; the differentiator will be execution. Firms that align product design with payer realities, accrue meaningful post-market evidence early, and build integrated services will capture outsized value.
PW Consulting’s full study equips you with the granular intelligence and decision tools to choose where to commit capital, whom to partner with, and how to sequence commercial initiatives in 2026. For access to the complete dataset, vendor scorecards, and the model workbook, visit PW Consulting’s report page or contact our advisory team to schedule a targeted briefing.
For detailed analysis of this topic, please visit the official page: Ambulatory Cardiac Monitoring Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


