



PW Consulting: Organic Corrosion Inhibitors market USD 877M in 2025, 4.2% CAGR

Organic Corrosion Inhibitors Market: Strategic Imperatives for 2026
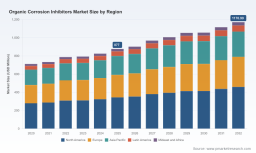
As companies prepare capital allocation, product development and commercial strategies for 2026, the organic corrosion inhibitors market presents a mix of steady growth, regulatory-driven transformation and concentrated supplier dynamics that demand targeted responses. PW Consulting’s in-depth study (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) synthesizes macro trajectories, compliance risk, raw-material exposures and competitor playbooks into a decision-ready framework. The global market reached approximately USD 877 million in 2025 and, on the trajectory captured in our model, expands at a compound annual growth rate of roughly 4.2% across the forecast window—reaching the neighborhood of USD 1.17 billion by 2032. This introduction outlines the strategic value of those findings for 2026 decision-makers while intentionally omitting the granular subsegment datapoints reserved for the full report.
Organic Corrosion Inhibitors Market
Why 2026 Is a Pivotal Year
The market’s steady mid-single-digit growth masks a set of inflection points that make 2026 a year of outsized strategic consequence. First, regulatory regimes in major markets are crystallizing preferences for organic, bio-based and lower-toxicity chemistries—altering eligible supplier lists for industrial water treatment, potable systems and certain oilfield services. Second, supply-chain dynamics—accentuated by antidumping rulings on certain imports and episodic feedstock volatility—are changing the cost calculus for formulators and downstream buyers alike. Third, incumbent suppliers are investing selectively in capacity, sustainability and regional footprint, which creates both consolidation risks and partnership opportunities for agility-focused players.
Organic Corrosion Inhibitors Market
Market Dynamics That Should Drive Your 2026 Playbook
-
Regulatory-led reallocation of demand: Policies such as REACH updates and procurement preferences for certified bio-based materials are re-shaping buyers’ technical and commercial specifications. Compliance is no longer a check-box; it is a procurement differentiator that can determine market access in key accounts.
Organic Corrosion Inhibitors Market -
Trade and tariff dislocations: Recent antidumping actions targeting specific exporters have introduced significant cost and availability disruptions, prompting buyers to reassess sourcing pools and nearshoring options to protect continuity of supply.
-
Raw-material and margin pressure: Volatility in amine precursors and petroleum-linked feedstocks is a recurring margin headwind for formulators. Recipe-level sensitivity analysis (contained in our report) shows where margin compression is acute and which formulation architectures are more resilient.
-
Certification and service demands: H2S service qualifications, NSF/ANSI 60 and eco-label credentials are increasingly required in bids. Suppliers with auditable compliance pathways and documented environmental performance are realizing preferential contract terms.
Strategic Actions for 2026 Decision-Makers
PW Consulting’s report is intentionally practical. Below are the priority actions we recommend for executives preparing budgets and go-to-market plans in 2026, along with how the full study supports each action.
-
Portfolio prioritization: Rebalance R&D and product pipelines toward formulations that meet the new regulatory and procurement thresholds. Use the report’s formulation risk matrix to rank products by expected regulatory exposure, margin resilience and scale potential.
-
Supply-chain resilience: Execute a supplier segmentation and dual-source strategy for critical precursors. Our procurement playbook includes a supplier-risk heat map and a short-listing methodology that reduces single-source exposure and mitigates antidumping-related shocks.
-
Targeted capex: Where capacity expansion is warranted, prioritize modular, flexible lines that can accommodate both legacy and bio-based chemistries. The report provides scenario-based capacity planning tools calibrated to the forecast’s growth bands and cost sensitivities.
-
Commercial and pricing discipline: Adopt value-based pricing for channels where environmental-certification and service packages create a willingness to pay premium. Our commercial scorecards identify buyer segments and contracting models that sustain higher gross margins.
-
M&A and partnership screening: Given meaningful market concentration among the leading suppliers, bolt-on acquisitions and targeted alliances remain efficient routes to broaden technical portfolios and regional access. The report contains an M&A filter aligned to strategic priorities and regulatory compatibility.
-
Regulatory & claims governance: Implement documentation systems and third-party verification programs to support environmental and safety claims. Our compliance playbook maps the certification ladder (USDA BioPreferred, EU ecolabels, NSF/ANSI) to procurement impact so you can prioritize investments with clear ROI.
Competitive Landscape — What the Full Analysis Reveals
The market exhibits moderate concentration: the combined share of the top three suppliers indicates that market leadership is meaningful but not insurmountable, and the top five account for a decisive majority of market influence. Leading players profiled in the report include multinational chemical and specialty firms that compete on formulation expertise, service models and certification credentials. Representative organizations examined are BASF SE, Dow Inc., Ecolab Inc., Henkel, AkzoNobel, Solvay, Clariant, LANXESS, Lubrizol, King Industries, ChampionX, Nouryon, Cortec, SUEZ Water Technologies & Solutions, Solenis and ChemTreat—each profiled for capability, channel focus and recent strategic activity.
Recent sector moves reinforce strategic themes: major incumbents are launching sustainability-focused formulations, expanding regional capacity and pursuing acquisitions to shore up local portfolios. Examples include new sustainable product introductions, regional capacity expansions and targeted acquisitions to strengthen presence in growth markets. These developments create windows for challengers to exploit white spaces—particularly where certification and service-orientation are valued.
What the Full Report Contains (Operational, Decision-Ready Deliverables)
-
Comprehensive market model (2020–2032) with demand drivers, sensitivity testing and scenario outputs aligned to different regulatory and feedstock trajectories.
-
Supplier scorecards and a competitive heat map that rate technology depth, certification coverage and channel strength for the top players.
-
Procurement playbook with cost-to-serve analysis, strategic sourcing templates and negotiation levers calibrated to antidumping and feedstock risk scenarios.
-
R&D and formulation roadmap highlighting high-retention chemistries, substitution pathways and sample stage-gate investments to de-risk new product introductions.
-
Regulatory impact assessment and compliance sequencing tool that links certifications (USDA BioPreferred, EU Ecolabel, NSF/ANSI 60) to tender success probabilities.
-
M&A screening framework and valuation heuristics tailored to integration risk in this specialty chemical space.
-
Commercial playbooks for key verticals—industrial water, metalworking, oil & gas and building materials—covering pricing, bundling and aftermarket services.
How PW Consulting’s Findings Translate to Board-Level Decisions
For boards and C-suite teams, the report converts market dynamics into capital and operational choices that can be actioned in 2026: which product lines to accelerate, what certification investments will unlock premium tenders, where to commit growth capital, and how to structure supplier agreements to control raw-material risk. Instead of abstract trends, the study delivers quantified trade-offs—e.g., margin impact under different feedstock cost scenarios, probability-weighted revenue outcomes under regulatory scenarios, and the implied return on capacity investments—so directors can prioritize initiatives that preserve optionality while capturing upside.
Closing: Why Access the Full Report
This introduction outlines the strategic levers that matter in 2026, but the practical value lies in the granular tools and datasets that convert insight into action. If your 2026 planning cycle includes portfolio rationalization, procurement re-design, or M&A screening in the corrosion-inhibitor space, PW Consulting’s full report provides the calibrated models, supplier intelligence and regulatory scenarios necessary to make confident, defensible decisions. The public preview intentionally omits detailed subsegment tables and proprietary scoring to preserve the analytical edge available in the full deliverable—accessing the complete report will enable you to apply the precise figures and playbooks directly to your 2026 budgets and strategic roadmap.
For detailed analysis of this topic, please visit the official page: Organic Corrosion Inhibitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


