



PW Consulting: Ceramic Package Market to Grow at 6.44% CAGR to 2032

Ceramic Package Market 2026: Strategic Intelligence for Executive Decision-Making
As companies plan capital allocation, product roadmaps, and supply-chain reconfiguration for the coming three to five years, high-quality intelligence on the ceramic package market will be a differentiator. PW Consulting’s new Ceramic Package Market study (base year 2025; historical 2020–2025; forecast 2026–2032) provides that intelligence—combining a rigorous, transparent market model with tactical playbooks intended to inform board-level strategy and operational execution in 2026.
Ceramic Package Market
Why this study matters for 2026 decisions
The ceramic packaging sector is no longer a niche materials play; it sits at the intersection of semiconductors, RF/mmWave components, power electronics, and high-reliability industrial applications. Our model shows market expansion from an estimated USD 12.11 Billion in 2025 to USD 13.17 Billion in 2026, and continued growth through 2032, reaching USD 18.74 Billion under the report’s central scenario. The forecast period (2026–2032) carries a compound annual growth rate (CAGR) of 6.44% under base assumptions—sufficient momentum to justify near-term capacity investments yet not so rapid as to obviate the need for careful segmentation and partner selection.
Ceramic Package Market
For 2026 planners, this combination of steady growth and structural change creates three strategic priorities:
Ceramic Package Market
- Secure materials and process capabilities that control the largest components of cost and yield volatility.
- Design flexible production footprints to manage trade-policy-driven supplier diversification and nearshoring pressures.
- Invest in differentiated packaging technologies (e.g., multilayer substrates, high-frequency molded ceramics) where product roadmaps meet rising demand from AI, 5G/6G radio, and power-dense systems.
Market dynamics that will shape 2026 outcomes
Our analysis synthesizes supply-side developments, regulatory shifts, and cost-structure mechanics to produce actionable implications for procurement, R&D, and corporate development teams.
- Supply-side capacity shifts: Major incumbent manufacturers are expanding advanced packaging capacity and in some cases building greenfield facilities. These capacity moves—both announced and under development—will affect lead times, qualification cycles, and local content calculations used by OEMs.
- Geopolitical and trade policy pressure: Export controls and technology-access rules have prompted OEMs and substrate suppliers to diversify beyond single-source geographies. Expect more regional production hubs to emerge in Southeast Asia and Europe as companies reduce exposure to export-related chokepoints.
- Cost drivers and yield imperatives: Raw inputs—primarily alumina powders and metallization—constitute the lion’s share of production cost. Our sector analysis estimates these materials and metallization processes at roughly 60% of substrate/package cost, with manufacturing yield loss contributing another material share to unit cost. For 2026, suppliers that can demonstrably control material sourcing and improve first-pass yield will command margin and pricing power.
- Compliance and materials governance: Emerging rules related to REX and conflict minerals compliance are already increasing compliance overhead and constraining material sourcing flexibility. Early-adopting firms are building traceability and alternative-sourcing strategies into procurement contracts to avoid downstream qualification delays.
Report scope and the hands-on outputs your team can use
PW Consulting’s study was commissioned and built to be operational for strategy, procurement, and product teams. The deliverables are constructed so that executives can move from insight to action within 90 days of purchase. Key components include:
- Comprehensive market-sizing and a transparent forecasting model (historical 2020–2025; forecast 2026–2032) with scenario toggles for demand shock, price volatility, and regionalization factors.
- Supply-chain heatmaps identifying pinch points for raw alumina, metallization capacity, and yield-critical process steps—aligned to supplier capability and lead-time metrics.
- Cost-build templates and sensitivity analyses showing how material price moves and yield improvements flow to unit economics and gross margins.
- Competitive positioning profiles and scorecards for the leading suppliers, covering technology breadth, capacity, vertical integration, and customer concentration.
- Regulatory and trade-impact playbooks—detailing tactical responses to export controls, subsidy regimes, and local-content requirements.
- Commercial implications: go-to-market frameworks for packaging OEMs, channel strategies for substrate vendors, and procurement playbooks (hedging, consignment, dual-sourcing) tailored to 2026 market realities.
- Executive-level scenario decks and acquisition target prioritization lists, with quantified runway and payback estimates based on our market model.
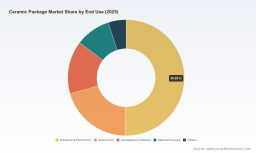
Because the report is intended to be a strategic instrument for commercial action, the public-facing executive summary intentionally omits granular disclosure of certain segment-level splits and account-level forecasts. This selective disclosure follows a “trailer” approach: we demonstrate methodology and directional findings while preserving the full, segment-level intelligence for report subscribers.
Competitive landscape — what the leading players are doing and what it means
The ceramic package market shows moderate concentration: our concentration metrics indicate the top three players account for about 35% of industry revenue, and the top five about 42%. This constellation favors companies that combine advanced materials know-how with scale in substrate manufacturing and tight customer relationships.
- NTK CERAMIC (Japan): NTK’s vertically integrated capability—covering end-to-end design and manufacturing of IC ceramic packages and substrates—positions it strongly in high-value, bespoke packaging for advanced semiconductors. Its strength lies in co-development with strategic OEMs and high-mix, low-volume production where qualification barriers create durable customer locks.
- Kyocera Corporation (Japan): Kyocera has moved rapidly into multilayer ceramic core substrates aimed at AI-class xPUs and switch ASICs; the company commercialized a new product family in April 2026 and is expanding production footprints. Kyocera’s combination of product breadth and announced capacity investments makes it a natural partner for systems companies seeking supply assurance for next-generation compute packaging.
- StratEdge Corporation (United States): StratEdge’s focus on high-frequency molded ceramic packages for RF, microwave, and mmWave applications is tightly aligned with the accelerating RF-content of wireless infrastructure and phased-array systems. Their MC Series showcase through 2025–2026 indicates a practical roadmap to support defense and telecom customers who require high-bandwidth, low-loss packages.
- CoorsTek (United States): CoorsTek’s position as a supplier of advanced SMD packages leverages deep ceramics manufacturing experience and relationships in computer and communication markets. The firm’s agility in adapting ceramic formulations and surface finishes gives it an edge in reliability-sensitive applications.
- Electro Ceramic Industries (United States): With expertise in hermetic glass-to-metal sealing and custom-engineered packages, ECI serves verticals where reliability is non-negotiable—semiconductor test sockets, medical implant devices, and defense systems. Their differentiation centers on materials engineering and hermeticity qualifications.
Recent product and facility developments—such as Kyocera’s multilayer substrate commercialization and strategic capacity expansion projects announced in Japan—underscore a market pivot toward higher layer-count substrates and the need for deeper qualification pipelines. For OEMs, this means evaluation cycles will favor suppliers that can commit qualified process windows and localized capacity.
Practical recommendations for 2026 planning
Based on the report’s synthesis, PW Consulting recommends executives prioritize the following actions in 2026:
- Material security program: Lock long-lead contracts for alumina powders and metallization inputs, create alternative-sourcing clauses, and invest in inbound audit capabilities to ensure traceability against REX/conflict-mineral constraints.
- Yield-first process improvement: Fund targeted yield-improvement projects (e.g., screen-printing, firing controls, metallization adhesion) with rapid ROI thresholds—every percentage point in first-pass yield materially affects unit economics.
- Strategic partnerships over pure-cost procurement: For critical packaging technologies, prefer co-development agreements and capacity reservations with qualified suppliers instead of spot procurement, reducing time-to-production risk for new platforms.
- Regionalization playbook: Model the enterprise P&L for alternative production footprints (domestic, Southeast Asia, Europe) to identify the most resilient mix of cost, lead time, and compliance risk under plausible export-control scenarios.
- M&A and technology scouting: Target small-to-mid sized firms offering vertically complementary capabilities (multilayer core substrates, high-reliability hermetic sealing, advanced metallization) to accelerate time to market.
Accessing the full intelligence
The executive summary above provides the directional implications that should inform near-term strategic decisions in 2026, while the full PW Consulting Ceramic Package Market report supplies the quantitative, segment-level detail necessary to operationalize those directions. Subscribers receive the full forecast model, supplier heatmaps, and a procurement playbook that translate market-level insights into executable plans for sourcing, R&D prioritization, and capital deployment.
To explore the complete dataset—including our granular scenario outputs and supplier scorecards—please consult the full report on PW Consulting’s website. The public synopsis intentionally withholds detailed segment allocations to protect the work-product that underpins our consulting engagements; purchasing the report grants access to the full, auditable model and tailored briefings for your leadership team.
For detailed analysis of this topic, please visit the official page: Ceramic Package Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


