



PW Consulting: Cement Clinker Market Set for 3.8% CAGR to 2032

Cement Clinker Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As PW Consulting publishes its comprehensive Cement Clinker Market study (base year 2025; historical window 2020–2025; forecast 2026–2032), corporate decision-makers face a pivotal planning horizon. The industry’s steady structural growth — underpinned by a projected compound annual growth rate (CAGR) of 3.8% over the 2026–2032 forecast period — masks accelerating disruption around decarbonization, capacity footprint optimization, and trade-policy volatility. This preview outlines the strategic value of the full study for 2026 planning cycles, highlights the competitive dynamics shaping near-term risks and opportunities, and summarizes the actionable components executives will find in the report. To preserve the report’s proprietary intelligence this article signals the insights to be gained without reproducing the detailed segment tables that reside behind PW Consulting’s paywall.
Cement Clinker Market
Macro Trajectory: A Stable Market With Strategic Inflection Points
PW Consulting’s market sizing traces a clear recovery and expansion pattern: the global clinker market climbed from a 2020 baseline and reached an estimated USD 357.5 Billion in the report’s base year, 2025. Under the central forecast, the market increases to approximately USD 462.5 Billion by 2032, aligning with the mid-single-digit CAGR of 3.8% over the 2026–2032 window. The headline numbers indicate reliable underlying demand — driven by ongoing infrastructure programs, housing markets in growth economies, and industrial construction — yet the arithmetic belies the strategic complexity operators must manage.
Cement Clinker Market
- Growth is broad-based but uneven: macro demand will be influenced regionally by public infrastructure spend, urbanization rates, and the pace of industrial activity. The full report contains the granular regional and application breakdowns that inform plant-level and route-to-market decisions.
- Volume growth will coexist with cost and regulatory pressure: fuel and raw-material logistics, plus tightening emissions rules, will increasingly shape capacity economics and retrofit investment cases.
Why This Study Matters for 2026 Corporate Planning
For executives preparing 2026 budgets, investment committees, or M&A strategies, this research is designed to convert market-level visibility into boardroom-ready guidance. The strategic value can be summarized in three decision-use cases:
Cement Clinker Market
- Capital-allocation prioritization: identify which clinker assets merit modernization versus debottlenecking or retirement under plausible carbon price and fuel-cost scenarios.
- Supply-chain resilience planning: stress-test procurement strategies for limestone, clay, and gypsum, together with logistics options that mitigate tariff and export-exposure risks.
- Portfolio rationalization and M&A playbooks: benchmark regional asset economics and competitor moves to validate greenfield versus acquisition pathways.
Competitive Landscape: What the Major Players Are Signalling
The clinker industry remains concentrated around integrated producers that can optimize upstream raw-material sourcing and downstream cement blending. Leading global and regional players are actively reshaping footprints and technology roadmaps. Our study profiles these companies with a focus on strategic initiatives that bear on clinker supply economics, including recent corporate developments:
- Holcim (Zug, Switzerland) — Demonstrated a high-profile electrification pathway in early 2026 by producing Portland-quality clinker using only electricity in a pilot with SaltX Technologies. This move illustrates the potential for disruptive low-carbon production routes, and it raises questions about scale-up timelines, power price sensitivity, and retrofit capex economics.
- Titan America (Athens, Greece) — Executed a targeted inorganic expansion in January 2026 with an acquisition that strengthens its Mid‑Atlantic footprint. The deal underscores ongoing consolidation in higher-cost markets where scale and integration reduce per-ton clinker cost.
- Heidelberg Materials (Hamburg, Germany) — Announced a redesign of its European clinker network as part of a longer-term strategy, signaling continued emphasis on capacity optimization and cost-to-serve improvements across mature markets.
- GCC (Tampa, United States) — Advanced both debottlenecking and major expansion projects in 2026, pointing to opportunities for volume-led margin gains where local demand growth and logistics advantages align.
- CEMEX and CRH — These integrated players continue to leverage plant networks and blended cement strategies to manage clinker utilization and respond to regional demand shocks.
Collectively, these actions illustrate two concurrent themes: (1) incumbents are actively balancing organic capacity upgrades with selective acquisitions, and (2) technological and operational levers (electrification pilots, debottlenecking, asset redesign) are being prioritized to reduce unit costs and emissions intensity.
Regulatory, Trade and Input Risks — Practical Implications
The 2026 planning horizon must explicitly account for regulatory and trade dynamics that are already reshaping clinker economics. Our study incorporates and interprets the latest signals, including:
- Trade flows and export status: the United States shifted to net exporter status for clinker in 2025, altering regional trade balances and competitive pressure in nearby markets. Key suppliers such as Turkey, Canada, and Vietnam now figure prominently in trade-based supply strategies.
- Tariff and trade-policy effects: 2025 tariff actions have had measurable, if uneven, impacts on cement and clinker markets — affecting both price formation and investment incentives along supply chains.
- Environmental regulation pressure: proposed standards for cement kiln operations and hazardous waste handling add both compliance cost and strategic constraints, potentially curbing greenfield modernization in certain jurisdictions unless exemptions or technology-based solutions are available.
These dynamics increase the value of scenario-based modeling for 2026: capital plans must be stress-tested not just for demand shock but for price, carbon-constraint, and trade-swing sensitivities. The full report offers scenario matrices and break-even tables to support that work.
Technology and Decarbonization Roadmap
Decarbonization is no longer a long-term aspiration; for clinker producers it is now a mid-term business problem with direct CAPEX and OPEX consequences. Our analysis disaggregates the viable technical pathways (fuel-switching, electrification pilots, carbon capture readiness, and efficiency-led debottlenecking) and assesses them against three practical criteria: implementation lead time, capital intensity, and sensitivity to power and carbon prices.
- Electrification pilots (e.g., Holcim’s April 2026 demonstration) show technical feasibility at laboratory and demo scale but leave open questions around grid capacity, electricity sourcing premiums, and plant-level retrofit costs.
- Operational optimization (debottlenecking, kiln efficiency, alternative fuels) remains the highest-confidence route to near-term emissions and cost improvements, and is often the fastest to value-capture.
- CCS and other end-state solutions are included in longer-range scenarios where the report quantifies implied carbon price thresholds for economic viability.
What the Full Report Provides — Practical, Actionable Content
PW Consulting’s full report is purpose-built for executive teams and transaction advisors. Key deliverables include:
- Comprehensive base-year market sizing and historical trend analysis (2020–2025) and a granular forecast (2026–2032) with scenario sensitivity.
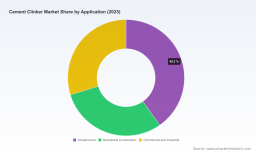
- Segment-level demand drivers by region, by application, and by clinker type — presented with actionable unit-economics and transport-cost overlays (note: detailed segment tables are available in the full report).
- Competitive benchmarking and profile dossiers for incumbent and emerging players, including strategic initiatives, capex plans, and M&A pipelines.
- Regulatory impact assessment, trade-flow modeling, and a compliance-cost playbook for jurisdictions with tightening kiln standards.
- Decarbonization technology roadmap with investment case templates, payback matrices, and supplier ecosystem mapping.
- Transaction support tools: valuation comparables, synergies calculator for M&A, and diligence checklists tailored to clinker assets.
Decision Checklist for 2026
As you finalize budgets and strategic priorities for 2026, consider this compact checklist drawn from the report’s recommendations:
- Re-run capital-allocation models incorporating at least two carbon-price scenarios and a power-price sensitivity for electrification projects.
- Identify short-list assets for low-cost debottlenecking or efficiency retrofits that deliver rapid margin uplift before committing to larger-scale modernization.
- Map near-term trade exposure by plant and customer cluster to prepare contingent logistics and pricing strategies against tariff and export shifts.
- Prioritize M&A targets that add scale in strategically important corridors or that accelerate low-carbon capability.
Final Note — Why Access the Full Study
This preview underscores why 2026 is an inflection point for clinker producers, traders, and downstream cement manufacturers. The market’s steady top-line growth (from USD 357.5 Billion in 2025 to an estimated USD 462.5 Billion by 2032 at a 3.8% CAGR) creates room for investment, but the real value will be captured by actors who integrate regulatory foresight, technology transition planning, and disciplined footprint optimization into their strategic planning.
PW Consulting’s full Cement Clinker Market report provides the detailed segmentations, tables, and proprietary models that corporate strategists and investment teams need to act with confidence. For confidential briefings, bespoke scenario runs, or to access the complete dataset and segmentation tables, PW Consulting’s industry team is available to assist with tailored deliverables aligned to your 2026 decision calendar.
For detailed analysis of this topic, please visit the official page: Cement Clinker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


