



PW Consulting: Non-Ferrous Scrap Market at USD 663.96B in 2025; 3.6% CAGR to 2032

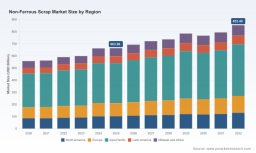
Non‑Ferrous Scrap Metal Market — Strategic Preview for 2026 Decision‑Making
Executive snapshot
As corporations and investors set strategy for 2026, the non‑ferrous scrap metal market presents a mix of structural growth, regulatory inflection points, and concentrated technological competition. Our latest PW Consulting study (base year 2025) traces the market through a five‑year historical window (2020–2025) and projects behavior across 2026–2032. The market expands from a mid‑hundreds‑billion USD base in 2020 to roughly USD 664 Billion in 2025, with a compound annual growth rate of 3.6% embedded across the forecast window. By 2032 the market is modeled to reach approximately USD 853 Billion, albeit with non‑linear year‑to‑year dynamics that require strategic flexibility rather than static plans.
Non Ferrous Scrap Metal Market
Why this matters for 2026
-
Timing of capital allocation: The trajectory and volatility we model—including short troughs and recoveries during the 2026–2032 forecast—mean that mid‑cycle capital commitments (plant upgrades, sorting automation, logistics hubs) should be phased and optioned rather than fully front‑loaded.
Non Ferrous Scrap Metal Market -
Competitive positioning: The market exhibits moderate consolidation (CR3 ~32.5%, CR5 ~38.0%), indicating national and regional leaders can shape feedstock flows and service standards, but there remains material room for agile regional specialists and technology disruptors to capture share.
Non Ferrous Scrap Metal Market -
Regulatory arbitrage and policy risk: Recent measures and anticipated rules in key jurisdictions will alter cross‑border flows and merchant economics—creating both constraints and protected domestic demand pockets that savvy value‑chain participants can monetize.
Market trajectory and the signal lines to watch in 2026
Beyond headline growth, our model highlights three structural drivers that will govern outcomes for companies and investors next year:
-
Feedstock quality and sorting yields. Improvements in automated sorting and sensor recovery raise the realized yield from mixed non‑ferrous streams, compressing unit processing costs and improving downstream metallurgy outcomes. Strategic buyers must evaluate technology ROI against incremental margin capture—our models quantify break‑even timelines under multiple volatility scenarios.
-
Downstream processing capacity. Capacity additions, retrofits, and localized policies are reshaping where processed scrap is converted back into intermediate and primary‑grade material. The capital cycle that accelerated in 2024–2026 creates pockets of incremental throughput—timing market entry to coincide with these capacity ramps materially affects realized prices and contract leverage.
-
Commodity price cycles and substitution. Macro forecasts from major institutions project upward pressure on aluminum and copper through at least 2027 due to primary supply constraints. Our scenario analyses layer these inputs with demand elasticity estimates to show when recycled feedstock becomes decisively more economical than primary metal for specific downstream uses.
Regulation, capital flows and geopolitical friction — what to expect
Regulatory actions and public financing in late 2025/early 2026 are not peripheral—they alter whole market architectures. Notable moves include tightened export policies in Europe for aluminum scrap beginning in 2026 and new state‑level licensing regimes in markets such as California for copper scrap transactions. Public capital is also mobilizing: a major European financial institution sanctioned multi‑hundred‑million USD support for recycling capacity and process optimization in 2025, signaling that public debt and grant instruments will be available to accelerate decarbonization and local processing agendas.
For 2026 strategy this means:
-
Short‑term logistics and contract design must anticipate shifts in cross‑border flows—sourcing strategies that worked in 2024 may require re‑routing or price adjustment clauses to remain effective.
-
Investment decisions should factor in conditional public financing—projects that align with circular economy objectives have a higher probability of securing concessional funding and permits.
Competitive landscape — who will move the market in 2026
The competitive set is a mix of vertically integrated processors, large commodity recyclers, regional specialists, and national traders. Each archetype pursues different levers—capex intensity, feedstock control, technological differentiation, or network breadth.
-
Sims Metal Management Inc. — A global processor and trader with investments in advanced recovery and AI‑enabled sorting. Sims has publicly announced capacity expansions in the U.S. and U.K. during early 2026, strengthening its ability to process complex streams and e‑waste. For peers, the lesson is clear: analytics‑driven sorting plus scale materially compresses delivered costs and increases high‑purity yield capture.
-
OmniSource Corporation — An integrated North American operator with broad processing capabilities. Its playbook emphasizes regional vertical integration and stable offtake relationships with downstream fabricators and smelters—an attractive strategy where export frictions emerge.
-
European Metal Recycling (EMR) — A U.K.‑headquartered trader/processor leaning into copper and aluminum grades with extensive pan‑European procurement. EMR is an example of the regional champion leveraging logistics scale and supplier contracts to offset rising primary metal costs.
-
Aurubis AG — An integrated non‑ferrous producer that combines recycling with smelting, and recently commissioned a substantial copper recycling facility in North America in 2025. Integration into primary metal production grants Aurubis preferred economics on complex scrap streams and resilience against feedstock volatility.
-
Shapiro Metals , American Iron & Metal , Manaksia Aluminium , and Hayes Metals — Regional leaders and specialists who compete on responsiveness, feedstock relationships, and local market knowledge. Their strengths become especially pronounced where regulatory shifts re‑regionalize supply chains.
Strategic playbook for 2026 — recommended actions
Based on our integrated modeling and company benchmarking, PW Consulting advises firms to pursue a three‑track strategy in 2026:
-
Defensive operational moves: Lock in flexible logistics contracts; accelerate sensor‑based sorting pilots; and implement dynamic pricing clauses in supplier and offtake agreements to handle commodity swings.
-
Selective growth: Prioritize brownfield expansions and retrofit projects supported by public financing or off‑take prepayments. Avoid greenfield projects unless paired with firm feedstock contracts or concessional funding that improve IRR under downside price scenarios.
-
M&A and partnership scouting: Target bolt‑on recyclers with local feedstock control, technology providers for sorting/AI, and smelters seeking to secure high‑quality recycled input. Use staged earn‑outs and performance‑linked consideration to price in near‑term commodity risk.
What the full PW Consulting report delivers
This preview intentionally highlights the strategic contours without revealing the fine‑grained analytics that underpin investment decisions. The full research package (base year 2025; historical 2020–2025; forecast 2026–2032) contains the operational tools and data tables that corporate strategists and deal teams use, including but not limited to:
-
Proprietary demand and supply model with yearly market sizing, price‑sensitivity scenarios, and a probabilistic view of the 2026–2032 trajectory (CAGR 3.6% central case).
-
Granular regional and application split sheets, interactive segment dashboards and elasticity matrices (note: segment‑level figures are excluded from this preview to preserve commercial value).
-
Capex and ROI templates for sorting technologies, shredding and hydrometallurgical upgrades, with payback curves under multiple commodity scenarios.
-
Negotiation playbooks for long‑term supply contracts, sample contract clauses to mitigate policy and price developments, and compliance checklists for emerging licensing regimes.
-
Competitive scorecards evaluating operational footprint, technology adoption, and balance sheet capacity for the core set of global and regional players mentioned above.
How to use these insights in 2026 planning cycles
Senior leaders should integrate the report into three planning activities this year: budget refresh, capital allocation committee reviews, and M&A screening. Use the dataset to stress‑test budgets against a downside price scenario and to identify high‑leverage, low‑cost interventions (process automation, procurement contract redesign, and targeted retrofits) that improve margin without requiring large new greenfield capital.
Closing: the signal for investors and operators
The non‑ferrous scrap market in 2026 is not merely a commodity play; it is the interface where circular economy policy, advanced recovery technology, and capital allocation converge. With a modeled market size rising from the mid‑hundreds of billions in 2020 to the high‑hundreds by 2032 and a steady 3.6% CAGR across our forecast, the arithmetic favors participants who combine operational discipline with strategic optionality. The full PW Consulting report supplies the granular inputs, contract templates, and decision‑ready models that will turn this arithmetic into value. For companies that need to convert scenario outputs into deployment timelines and deal pipelines, this is the toolkit to use.
To access the complete dataset, regional and application splits, and executable playbooks referenced in this preview, please visit the PW Consulting report page for the Non‑Ferrous Scrap Metal Market — the detailed intelligence that powers decisive 2026 strategy.
For detailed analysis of this topic, please visit the official page: Non Ferrous Scrap Metal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


