



PW Consulting: Cleanroom Consumables to reach USD 7.36B by 2032 at 6.5% CAGR

Cleanroom Consumables Market — Strategic Outlook for 2026 Decision-Making
As cleanroom-dependent industries recalibrate for accelerated semiconductor cycles, stricter sterile-manufacturing norms, and heightened sustainability expectations, the market for cleanroom consumables is entering a strategic inflection point. PW Consulting’s latest Cleanroom Consumables Market study (base year 2025, forecast 2026–2032) synthesizes five years of historical performance with scenario-driven forecasting to give procurement, operations, and corporate strategy teams the actionable intelligence they need for high-stakes 2026 decisions.
Cleanroom Consumables Market
Macro snapshot: why this moment matters
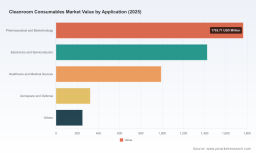
By conventional metrics the market is sizable and resilient: our model shows continued compound annual growth through the forecast window, underpinned by rising demand across life sciences, semiconductors, and advanced manufacturing. Specifically, the market reached USD 4,750 Million in 2025 and is projected to grow at a 6.5% CAGR, reaching roughly USD 7,362 Million by 2032. Concentration remains relatively low at scale — the top three and top five players account for only single-digit shares beyond the mid‑teens and low‑twenties respectively — indicating a fragmented vendor landscape that rewards supply differentiation, certification depth, and logistical excellence.
Cleanroom Consumables Market
What the report delivers — practical, transaction-ready insights
- Forward-looking demand models calibrated to end‑market adoption curves and regulatory milestones (2026–2032). These models are built to be integrated into procurement S&OP and capital planning workflows.
- Price and cost‑to-serve analytics that quantify the impact of raw-material volatility and transportation dynamics on consumable spend.
- Supplier benchmarking and playbooks for vendor selection, qualification, and dual-sourcing strategies, including a pragmatic framework for balancing single‑use validation needs with sustainability targets.
- Regulatory impact maps that translate recent policy shifts into operational checklists for sterile manufacturing, glove procurement, and device‑grade consumables.
- Scenario analyses (baseline, supply‑stress, high‑demand) with recommended action triggers — ideal for risk committees, procurement war-rooms, and M&A diligence.
- Strategic initiatives and ROI estimates for adoption of digital monitoring (IoT-enabled consumable tracking), circularity pilots, and automation in cleanroom logistics.
Key dynamics reshaping supply, price and compliance
- Raw-material and cost pressure: Polyester and polymer feedstock volatility are no longer episodic risks. Polyester futures surged in early 2026, lifting upstream input costs and squeezing margins for wiper and garment manufacturers. Our analysis quantifies how a mid‑teens input cost shock propagates through wholesaler pricing and can erode lean inventory advantages if unhedged.
- Regulatory tightening: The revised EU GMP Annex 1 (effective since 2025) and recent FDA device- and glove-related guidance have increased validation overheads and certification requirements for sterile-production consumables. This drives higher total cost of ownership for low‑cost suppliers and elevates the comparative value of certified partners with documented sterile-process controls.
- Supply fragility for single-use categories: Nitrile and other glove supply disruptions persisted into late 2025, forcing procurement waivers and spot buying that materially increased per‑unit costs in crisis windows. Buyers that structured multi-year validated supply agreements or developed in-market buffer strategies demonstrated better continuity and lower effective cost.
- Digital and service differentiation: IoT and analytics for consumable monitoring are moving from pilot to procurement criterion. Platformized solutions that combine inventory telemetry with quality traceability create stickier supplier relationships and measurable reductions in overstock and contamination incidents.
Competitive landscape — what to look for in a vendor
The competitive field mixes global chemical and industrial groups, specialist manufacturers, and regional system integrators. Leaders differentiate across three vectors: validated quality systems, breadth of sterile offerings, and supply-chain resilience.
Cleanroom Consumables Market
- Large diversified suppliers — firms such as DuPont and Kimberly‑Clark bring scale, certification depth, and broad distribution networks. They offer rapid qualification for complex programs but can command pricing premia tied to brand and validated processes.
- Specialist manufacturers — companies like Texwipe, Contec, and Valutek focus on low‑lint materials, high‑precision wipes, and packaging for ISO‑sensitive environments. These players often lead in niche performance innovations (e.g., sub‑micron particle control) and provide flexible OEM arrangements.
- Regional and technical innovators — Micronclean, Berkshire, Nitritex, and Micronova combine local manufacturing with technical garments and ESD capabilities, useful for multi-site rollouts that require fast lead times and regional compliance mastery.
Recent corporate moves underscore strategic themes: Contec’s 2025 EcoShield sustainability program signals product-level decarbonization and recycled-material pathways; ABN’s SmartCleanroom 4.0 platform launch reflects rapid convergence between consumables and operational monitoring; and Berkshire’s 2026 capacity expansion in Texas highlights continued investment to serve semiconductor and life-sciences demand. For buyers, these actions translate into differentiated value propositions — sustainability-labeled SKUs, telemetry-enabled replenishment, and improved local availability — which should factor into 2026 sourcing decisions.
How to convert insights into 2026 actions — a decision checklist
- Stress-test suppliers against three scenarios: normal demand, sudden surge (e.g., fab ramp or vaccine campaign), and prolonged raw-material inflation. Ensure contracts include price-collar and capacity‑reservation clauses that align incentives without disabling flexibility.
- Prioritize validated sterile capability: for critical sterile-drug and device lines, prefer suppliers with documented Annex 1/FDA alignment and end‑to‑end traceability. Validation costs may be higher upfront but reduce lot‑release failures and recall exposure.
- Layer sustainability with risk mitigation: pilots for recycled‑content wipes or washing-and-reuse programs should be evaluated alongside contamination risk — not as a pure cost center but as a phased program with defined quality gates.
- Adopt telemetry in consumable logistics: IoT-enabled replenishment reduces stockouts and ties procurement to usage-based contracting. Embed consumable data into quality‑management systems to accelerate root‑cause analysis in contamination events.
- Hedge raw-material exposure: use a mix of forward contracts, dual-sourcing, and localized inventory buffers calibrated by SKU criticality. Our report provides a practical hedging matrix that maps material exposure to contract levers.
- Use procurement to shape product design: combine early supplier involvement with specification flexibility (e.g., alternative polymer blends or coating choices) to open low-risk substitution paths when supply tightens.
Scenario playbooks and KPIs we recommend
For executive teams, the report includes three playbooks tailored to strategic positioning:
- Continuity-first (risk-averse manufacturers): emphasizes validated multi-sourcing, increased safety stock for key disposable items, and long-term supplier partnerships with contractual service levels.
- Cost-leadership (large high-volume buyers): focuses on volume-based agreements, specification harmonization, and capital investment in in-house sterilization or finishing capabilities where TCO justifies.
- Innovation-driven (OEMs and niche fabs): prioritizes co-development with specialist suppliers, early adoption of smart monitoring, and sustainability pilots that create market differentiation.
Each playbook is accompanied by a small set of KPIs (days of cover for critical SKUs, validated supplier ratio, telemetry-enabled inventory percentage, cost‑per‑lot impact of raw-material inflation) so teams can translate strategy into measurable outcomes rapidly.
Research methodology and validation
Our baseline combines primary interviews with procurement officers, quality leads, and supplier operations managers, triangulated against manufacturer financials and proprietary shipment data. The forecasting approach blends bottom‑up SKU-level demand curves for major end markets with top‑down macro drivers. Importantly, we provide sensitivity bounds rather than single-point estimates — enabling users to re-run assumptions for their specific exposure.
Why PW Consulting’s study should be in your 2026 toolkit
Decision-makers face simultaneous pressures: tighter sterile regulations, episodic raw-material shocks, and a fast-evolving vendor ecosystem that now includes digital and sustainability levers. Our Cleanroom Consumables Market study is designed as a decision accelerator — not a raw-data dump. It packages operational playbooks, vetted supplier assessment criteria, and risk-triggered actions that can be embedded into procurement RFx, quality-validation plans, and capex prioritization discussions.
To preserve the tactical value for users preparing procurement negotiations and competitive responses, this overview intentionally holds back granular segment-level allocations and SKU-by-SKU projections. The full report includes executable annexes — supplier scorecards, SKU criticality matrices, and downloadable models — that will enable teams to operationalize the insights presented here.
Next steps
- Use this overview to align stakeholders on priority risks for 2026 (raw-material exposure, certification needs, and inventory telemetry).
- Request the full report for SKU‑level forecasts, supplier scorecards, and customizable scenario models to support RFPs, validation programs, and capital allocation.
- Engage PW Consulting for a targeted workshop to translate the playbook most applicable to your enterprise (continuity, cost leadership, or innovation) into a 90‑day action plan.
PW Consulting’s Cleanroom Consumables Market study equips leaders with both the strategic lens and the operational toolset necessary to make confident, measurable decisions in 2026. For procurement teams, quality leaders, and corporate strategists, the stakes are immediate: decisions made this year will determine continuity, cost, and compliance outcomes through the next industry cycle.
For detailed analysis of this topic, please visit the official page: Cleanroom Consumables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


