



Music Distribution Services Market: PW Consulting Forecasts 9.81% CAGR to USD 5.94B by 2032

Music Distribution Services Market — Strategic Preview for 2026 Decisions
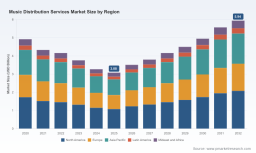
As PW Consulting’s lead industry analyst, I present a strategic preview of our Music Distribution Services Market research — a focused briefing designed to orient executive decision‑making in 2026. The study’s base year is 2025 and it models market behavior across a 2026–2032 forecast window. After a contraction through the first half of the decade, the market is modeled to return to growth from 2026 onward, tracking a compound annual growth rate (CAGR) of approximately 9.81% and moving from roughly USD 3.08 Billion in 2025 toward an expected market size near USD 5.94 Billion by 2032. This preview surfaces the strategic implications without disclosing the granular segment tables and regional splits reserved for subscribers to the full report.
Music Distribution Services Market
Why this study matters for 2026 strategic choices
- Market inflection: 2026 represents a tactical hinge — macro pressures and product innovations converge to create opening windows for incumbents and new entrants alike. Our forecast captures that inflection and models the sensitivity of outcomes to policy and platform shifts.
- Decision-use focus: The research is built to support four primary use cases—M&A and investment diligence, product and roadmap prioritization, commercial negotiations and partnership structuring, and operational re‑engineering for distribution cost and latency.
- Regulatory and platform risk is core: Recent industry developments (notably shifts in platform remedies and data‑sharing obligations as well as continuing debate over broadband regulation) materially affect distribution economics, pricing leverage, and data access models. These changes are integrated into our scenarios.
Market trajectory — interpretation beyond the headline numbers
The market contracted in the 2020–2025 window as legacy revenue streams adjusted to new consumption patterns, platform consolidation, and pricing pressures. From a low base near the 2025 level, our models project a sustained recovery driven by three structural forces: (1) monetization expansion in paid streaming and ancillary formats (including music video distribution and short‑form integrations), (2) the rapid maturation of creator‑focused services and AI‑enabled tooling that reduce marginal costs of release and promotion, and (3) infrastructure improvements that lower delivery friction and improve global reach.
Music Distribution Services Market
Despite the optimistic trajectory, the recovery is neither uniform nor guaranteed. Our sensitivity testing highlights five key risks that could slow or reverse growth: intensified fee compression from price‑led competitors, tighter platform gatekeeping or unilateral policy enforcement, regulatory constraints on data flows and revenue sharing, CDN and bandwidth cost volatility, and macroeconomic shocks that depress discretionary music spending.
Music Distribution Services Market
Practical strategic implications for 2026
- Product and commercial positioning: Prioritize modular service stacks that allow clients to mix basic distribution with premium add‑ons (video distribution, playlist pitching, sync licensing facilitation, advanced analytics). Flexibility reduces churn and increases lifetime value.
- Data and rights infrastructure: Invest in a rights database, automated metadata hygiene, and cross‑platform reporting. The firms that can prove transparent, auditable royalty flows will win institutional partners and higher‑value label contracts.
- Platform partnerships and API plays: Negotiate API access and co‑marketing agreements early. The value of native integrations (DSPs, social platforms, and video hosts) compounds as discoverability and promotional mechanics evolve.
- Delivery and performance engineering: Treat CDN and edge delivery as a strategic sourcing decision. Latency improvements and regional caching materially improve user experience for high‑consumption markets and reduce streaming costs.
- Monetization experiments: Test hybrid pricing—subscription, per‑release fees, revenue shares for premium services—to find elasticities in different artist and label cohorts. Embed marketplace functions (plugins, masters services) to diversify revenue.
- Regulatory preparedness: Build scenario playbooks for data‑sharing mandates, content moderation rules, and potential platform unbundling. Legal and policy monitoring should feed product roadmaps weekly, not quarterly.
What’s inside the full PW Consulting report (practical, executional content)
- Market model and transparent assumptions — base, upside, and downside scenarios for 2026–2032, including sensitivity to pricing and platform access.
- Commercial playbooks — go‑to‑market templates for white‑label distribution, direct‑to‑artist marketplaces, and label service offerings.
- Technology and operations audit checklist — CDN selection, metadata pipelines, content ID stacks, and rights ledger best practices.
- Vendor selection framework and RFP templates — standardized scoring for technical, commercial, and regulatory fit.
- Competitive benchmarking and positioning maps — capability heatmaps, service‑level comparisons, and M&A targets by capability gap.
- M&A playbook and valuation framework — revenue / margin bridges, integration checklists, and three‑year synergies modeling.
- Regulatory risk matrix and mitigation tactics — playbooks for data‑sharing mandates, platform remedies, and market access constraints.
- Case studies and financial templates — real‑world examples of successful bundling strategies and downloadable models for scenario testing.
Competitive landscape — strategic profiles and implications
The market structure is moderately concentrated: the top three providers capture a majority share of commercial distribution flows, reflecting scale economics in platform access, catalog management, and payment clearing. That concentration shapes how entrants design their value propositions and where incumbents can exert pricing leverage.
- TuneCore — positioned as an independent‑artist staple with broad platform coverage and artist‑first messaging. Strengths: deep platform relationships and straightforward rights retention claims. Strategic challenge: differentiating beyond scale in an environment where many competitors offer similar economics.
- DistroKid — a low‑friction, price‑led model targeting high‑volume independent creators. Strengths: product simplicity and network effects among creators. Strategic challenge: sustaining margins while expanding premium services and analytics.
- CD Baby — long reputation with one‑time fee structures and strong fulfillment for indie catalogs. Strengths: trusted brand and label services. Strategic challenge: modernizing tech stack and replicating subscription economics favored by newer entrants.
- Beatport Music Distribution — specialist orientation toward electronic/dance communities with label and artist management tools. Strengths: niche curation and storefront partnerships. Strategic challenge: scaling beyond genre niches without diluting brand.
- LANDR — leverages AI tools (mastering and workflow automation) to extend distribution into creative tooling. Strengths: vertical integration of creative and distribution services. Strategic challenge: converting AI‑led engagement into sustainable distribution revenue.
- Amuse — emerging as a hybrid platform with artist services and label support; in March 2026 the firm expanded into music video distribution to Spotify and Vevo as a one‑time purchase option for DIY artists, signaling a push into video monetization and differentiated offerings. Strengths: fast product iteration and artist acquisition; Strategic challenge: balancing free or low‑cost service tiers with unit economics.
Across competitors, strategic differentiation is increasingly found in ancillary services (analytics, video, sync, AI mastering) rather than base distribution alone. Expect continued pressure on base fees and a race to capture higher‑margin adjacent services.
Regulatory and infrastructure factors to watch
Several contextual elements materially influence strategic choices in 2026:
- Recorded‑music revenue dynamics — paid streaming remains the dominant revenue engine for recorded music globally and is a primary driver of downstream distribution demand and economics.
- Platform and data regulation — remedies that require service sharing or constrain how search and recommendation data are used will change bargaining power between platforms, distributors, and rights holders.
- Net neutrality uncertainty and broadband classification debates — fluctuations in policy can alter the cost and quality of content delivery, particularly for high‑bandwidth formats like video.
- CDN and edge infrastructure — performance improvements materially reduce buffering and improve listener retention, making delivery partners strategic suppliers rather than commodities.
How to use this research in 90 days — an operational checklist
- Run the report’s scenario models against your pricing and customer acquisition assumptions to estimate break‑even and upside thresholds.
- Audit metadata and rights flows using the included checklist to eliminate common royalty leakage points.
- Negotiate at least one strategic API or co‑marketing agreement informed by the vendor‑map recommendations.
- Test a bundled premium offer (e.g., video distribution + playlist pitching + analytics) with a controlled cohort to validate elasticity assumptions.
- Establish a regulatory watch cell to surface platform or policy changes that would trigger contract renegotiation or roadmap pivots.
Conclusion — This preview lays out the strategic contours executives must weigh in 2026: a market recovering from a mid‑decade contraction, concentrated competitive dynamics, accelerating monetization vectors (notably video and creator services), and an operating environment reshaped by platform and policy shifts. The full PW Consulting Music Distribution Services Market report contains the detailed segment tables, regional and application splits, financial models, and vendor scores that operational teams and investment committees need to convert these insights into executable plans. For the proprietary datasets, scenario workbooks, and the granular playbooks referenced above, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Music Distribution Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


