



PW Consulting: Small Hydropower to reach USD 2.97B by 2032 at 4% CAGR

Small Hydropower Market 2026 Preview: Strategic Imperatives for Energy Executives
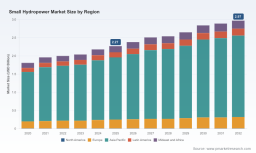
As demand for distributed, resilient, and low-carbon generation intensifies, small hydropower is re-emerging as a pragmatic complement to wind, solar, and storage in many power portfolios. PW Consulting’s upcoming Small Hydropower Market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—translates that macro momentum into decision-grade insight. At the aggregate level the market has grown from roughly USD 1.8 Billion in 2020 to an estimated USD 2.27 Billion in 2025, and our mid-range projection points to a continuation of expansion at a roughly 4.0% CAGR over 2026–2032, reaching just under USD 3.0 Billion by 2032. These headline metrics matter: they reframe small hydro from a niche engineering pursuit to a repeatable commercial opportunity that merits attention from project developers, equipment OEMs, financiers, and policymakers.
Small Hydropower Market
Why this study matters for 2026 corporate strategy
-
From opportunistic projects to portfolio allocation: The reported growth trajectory makes small hydropower a credible option for firms seeking long-duration, baseload-capable renewable assets that can complement intermittent generation sources and provide ancillary services.
Small Hydropower Market -
Capital deployment timing: With the market showing steady growth into 2032, 2026 is a critical inflection point for locking in EPC and supply-chain arrangements, pre-qualifying manufacturers, and securing favorable offtake terms before competition intensifies.
Small Hydropower Market -
Risk-managed expansion: The aggregated market dynamics conceal meaningful heterogeneity across sites, technology types, and permitting regimes. Executives who act on high-level growth signals without granular project-level intelligence expose their organizations to execution and regulatory risk.
What the headline numbers conceal — and why granular intelligence is essential
Aggregate growth and a mid-single-digit CAGR are useful shorthand, but value lies in the underlying distribution: site quality, hydrology seasonality, head and flow characteristics, civil works complexity, and policy incentives differ markedly from basin to basin. Our full analysis disaggregates the market across capacity bands, plant types and regional demand drivers to translate the macro trend into executable project pipelines and vendor selection strategies. This preview intentionally refrains from publishing the report’s detailed segmentation tables—our objective is to signal the shape of opportunity while directing readers to the full deliverable for the operative data that underpins bids, valuations and capex plans.
Industry dynamics shaping 2026 decisions
-
Policy and programmatic catalysts: Several national renewable frameworks launched in the immediate past and early 2026 have elevated small hydropower within public procurement and investment pipelines, particularly for run-of-river and pumped applications tied to grid balancing. These programs create a window for pipeline acceleration but also raise the bar on compliance and documentation for developers.
-
Pumped-storage momentum: Large EPC wins announced in 2025–2026 for pumped-storage electro-mechanical packages illustrate that OEM capability in both generating and pumping modes is a differentiator. Strategic alignment with experienced suppliers can materially shorten project delivery timelines.
-
Capacity and technology mix: Conventional turbine technologies (Francis, Kaplan, Pelton) remain foundational, but low-head and compact designs are gaining traction where environmental constraints or civil limitations prevail. Components and runner geometry trends feed directly into procurement, O&M planning and refurbishment strategies.
-
Consolidation and concentration: Market concentration is meaningful but not extreme—the top three and top five suppliers together account for a material share of supply without creating a closed oligopoly. This creates room for specialist entrants to capture niche value through refurbishment, digital-enhanced O&M, or site-specific engineering.
Competitive landscape — what top vendors reveal about where margins are
Our competitive profiling focuses on firms that combine turbine engineering with systems-level capability. A few representative players illustrate how value is being captured across the stack:
-
GUGLER Water Turbines GmbH — A specialist with deep breadth across Francis, Kaplan and Pelton designs, GUGLER emphasizes scalable water-to-wire solutions that span micro to medium hydropower. Their strength is in modular turbine offerings and adaptability to constrained civil conditions.
-
Gilbert Gilkes & Gordon Ltd — A legacy manufacturer focused on compact turbine designs and aftermarket services. They have built a market position around refurbishment, optimization and rapid-delivery units for projects where schedule and fit-to-site matter more than scale.
-
Voith Hydro — Voith couples product breadth with system engineering, bringing low-head technologies and turnkey river/canal solutions. Their recent contract awards for pumped-storage electro-mechanical packages demonstrate the premium placed on end-to-end capability.
-
ANDRITZ Hydro — With a compact-hydro division and a full electromechanical offering, ANDRITZ competes on integrated solutions and has been active on major balance-of-plant contracts. Their wins on pumped-storage projects underscore the rising importance of multi-mode functionality.
Collectively these vendors show why procurement strategies that prioritize integrated EM packages, service agreements, and digital O&M tools can capture superior lifecycle margins. The full report contains a vendor heatmap, supplier scorecards and M&A watchlist to help executives target partnership or acquisition candidates in 2026.
Recent project and policy highlights that shift near-term tactics
-
Contract awards for pumped-storage electro-mechanical packages in 2025–2026 have re-calibrated expectations for delivery timelines and integration complexity. These wins point to a two-track market: baseload and run-of-river projects on one side, and pumped-storage projects that prioritize reversible units and grid services on the other.
-
Publicly announced national development schemes and government-supported project commissioning in Asia during 2025–2026 have de-risked a tranche of projects, expanding the investable pipeline for development firms and attracting international suppliers.
Practical takeaways for 2026 planning
-
Prioritize pipeline quality over headline GW: Move from exploratory site lists to a short list of shovel-ready opportunities supported by hydrological data, environmental clearances and grid connection prospects. Our scoring matrix in the full report shows which attributes compress cost of capital most effectively.
-
Lock in supplier collaboration early: Long lead items and site-specific civil work can dominate schedules. Executives should pursue conditional supply agreements with clauses that address price indexation and delivery risk, and align performance incentives around availability and ancillary services.
-
Differentiate through operations: Aftermarket services, digital monitoring and turbine retrofits represent high-margin, lower-capex plays. For asset owners, investments in predictive maintenance and remote performance optimization can raise availability while tamping down lifecycle cost.
-
Design for financing: Lenders will favor projects with demonstrated revenue stacking (energy, ancillary services, capacity payments) and transparent environmental permitting. Structuring offtake and partial guarantees—often provided in national schemes—will be decisive for bid competitiveness.
-
Monitor regulatory windows: Several national programs are phasing allocations and incentives; developers should synchronize bid timelines to policy disbursement schedules and bankability requirements.
What PW Consulting’s full study delivers
The complete Small Hydropower Market report is designed as an operational toolkit for 2026 planning and includes:
-
Granular market sizing and forecast tables by capacity band, plant type and region (2020–2032), with scenario sensitivity to hydrology and price assumptions.
-
Project-level pipeline intelligence and a prioritized shortlist of investable opportunities with risk-adjusted return estimates.
-
Supplier heatmaps and vendor scorecards, including technical capability, delivery performance and aftermarket strength.
-
Procurement and contract templates, plus negotiation playbooks for electro-mechanical packages and long-term service agreements.
-
Regulatory tracker and policy heatmap that align incentive windows with financing and execution timelines.
This preview purposely shares high-level market trajectories and strategic implications while withholding the granular segmentation tables, regional shares and project-level valuations that underpin transactional decisions. If your team is preparing capital allocation, M&A screening, or a new bid pipeline for 2026, the full report provides the data models, vendor intelligence and executable checklists required to move from strategy to signed contracts.
Next steps
PW Consulting can brief executive teams on the study’s scenario models and run a rapid 48–72 hour diagnostic on your portfolio to identify priority actions for 2026. Our approach combines the published market baseline—which shows growth from about USD 1.8 Billion in 2020 to roughly USD 2.27 Billion in 2025 and a forecast of near USD 3.0 Billion by 2032 at a ~4.0% CAGR—with project-level intelligence to set operational priorities. Contact us to schedule a tailored briefing and obtain the full dataset, vendor heatmaps, and the project pipeline required to turn the market’s macro momentum into board-ready investment plans.
For detailed analysis of this topic, please visit the official page: Small Hydropower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


