



PW Consulting: Mindfulness Apps Market to Grow at 12.6% CAGR — Key Insights

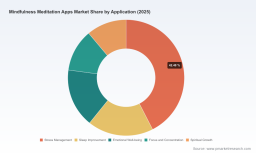
Mindfulness Meditation Apps Market: Strategic Briefing for 2026 Decision‑Makers
As organizations and investors reassess digital wellbeing priorities for 2026, this briefing synthesizes the strategic implications of PW Consulting’s latest Mindfulness Meditation Apps Market study (base year 2025, forecast 2026–2032). The market has moved from an early-stage wellness play into a commercially significant digital vertical: after growing from under USD 1 billion in 2020, the industry reached roughly USD 1.5 billion in 2025 and is forecast to exceed USD 3.5 billion by 2032, expanding at a compound annual growth rate of approximately 12.6%. This trajectory creates both opportunity and risk — and requires different choices from product, regulatory, partnership and M&A leaders than were necessary even three years ago.
Mindfulness Meditation Apps Market
Why this study matters for 2026 decisions
-
Timing: The market is entering a higher‑growth phase where early investments in AI personalization, immersive experiences, and strategic partnerships can compound value quickly. Decisions made in 2026 will determine whether a company is a category leader or a fast follower by 2028–2030.
Mindfulness Meditation Apps Market -
Complexity: The convergence of consumer wellness expectations, regulatory scrutiny of AI, and new delivery modes (XR and wearables) means simple product pivots are no longer sufficient. Execution requires cross‑functional programs spanning clinical quality, privacy engineering, and device integration.
Mindfulness Meditation Apps Market -
Capital allocation: With predictable, repeatable subscription economics emerging across premium offerings, boards must decide whether to prioritize CAPEX for IP and R&D, M&A to consolidate market share, or partnerships that accelerate distribution.
Data‑driven market picture (high level)
Our market model shows a clear and accelerating revenue curve. Between 2020 and 2025 the market more than doubled, and at a sustained CAGR of ~12.6% the total addressable revenue base is projected to grow substantially through 2032. The inflection points in our forecast correspond to three structural drivers: (1) premiumization and monetization of sleep and therapy-adjacent features; (2) platform extensions into XR and wearables that increase engagement and willingness to pay; and (3) enterprise and clinical channel expansion (employee wellbeing contracts, clinical pilots) that add higher‑ACV revenue streams. These drivers are quantified and stress‑tested across multiple scenarios in the full report.
Competitive landscape — who matters and why
-
Headspace — comprehensive consumer platform with guided sessions, sleep programs, and expanding AI and mixed‑reality experiments. Recent product initiatives include an XR app rollout for immersive meditation on mainstream headsets.
-
Calm — consumer leader known for sleep content, calming soundscapes and a strong brand position for stress reduction and bedtime experiences.
-
Insight Timer — community-driven, freemium model with an extensive library and social features that drive retention without heavy paid conversion spending.
-
Waking Up — niche, teacher‑led approach that emphasizes depth and pedagogy; appealing to users seeking long‑form learning and a subscription willing to pay for thought leadership.
-
Smiling Mind , Medito , and non‑profit/teacher apps — these entrants exert pricing pressure and broaden market reach through entirely free models and community distribution.
-
Isha Foundation — large institutional reach and recent viral uptake for short guided programs through its Miracle of Mind app, demonstrating the power of faith‑and‑teacher‑led networks to scale rapidly.
Collectively, the competitive set reveals two viable strategic archetypes going forward: (a) premium, product‑led platforms that monetize deep personalization and clinical adjacencies; and (b) scale‑and‑engagement players that dominate reach using free or community monetization models. Both archetypes face the same regulatory headwinds and technology opportunities — but they require different operating models, talent mixes and capital plans.
Recent developments that change the playbook
-
Mass adoption signals: Specialist and teacher‑backed apps have demonstrated rapid consumer uptake in 2025, underscoring how content provenance and network effects can drive viral growth.
-
XR and wearables: Major vendors have moved beyond concept demos — immersive meditation apps and consumer wearables with meditation modes are now commercially available, shifting parts of engagement from mobile UI to spatial and biosignal experiences.
-
Device‑adjacent innovation: New consumer wearables promise deeper relaxation states and present opportunities (and risks) for apps to bundle hardware + subscription offerings.
Regulatory and operational dynamics to factor into 2026 plans
-
EU AI Act — personalization engines and conversational agents embedded in meditation apps will become subject to transparency obligations as bulk applicability increases in 2026. Some mental‑health oriented AI features could be classified as higher‑risk and require conformity assessments; companies must map feature-level risk now to avoid slowdowns.
-
Data privacy frameworks — GDPR and CCPA remain front‑and‑center: consent flows, data minimization, and secure processing are table stakes for customer trust and B2B contracts. These are not optional compliance items for market leaders.
-
Healthcare boundary — mindfulness apps remain primarily classified as wellness offerings and therefore outside the strictures of healthcare privacy regimes domestically; however, moving into therapist‑integrated or diagnostic features changes the regulatory posture materially.
-
Talent and operating cost — AI personalization requires sustained investment in ML engineering, ethical review boards and clinical oversight, creating a higher ongoing labor component in cost structure versus a pure content app.
Actionable strategic recommendations for 2026
-
Prioritize compliance‑first product roadmaps: Conduct feature‑level AI risk mapping and privacy impact assessments in Q1–Q2 2026. For any conversational or recommendation engine that touches mental health, build conformity plans early to avoid market access delays in the EU.
-
Define a clear monetization archetype: Decide whether to compete as a premium platform, scaled freemium community, or hybrid. Each requires different investment multipliers — premium platforms must invest more in clinical validation and device integrations; community models must optimize for engagement velocity and alternate monetization (partnerships, donations, ancillary services).
-
Invest selectively in XR and wearables: Run controlled pilots with headset and wearable partners to understand engagement lift and CAC/retention impacts before committing to hardware bundling.
-
Build an enterprise arm as a margin lever: Employee wellbeing contracts and clinical pilots can increase ARPU and reduce churn volatility. Establish a small, cross‑functional enterprise team to pilot two to three employer or clinical partnerships within 12–18 months.
-
Use M&A to accelerate capability gaps: Identify tuck‑ins for AI personalization, clinical assessment, or XR content libraries rather than performing multi‑year internal builds — the report provides a calibrated M&A screen of targets that meet these criteria.
-
Plan for resilient privacy and data engineering: Budget for a privacy‑by‑design stack and third‑party audits; these investments materially reduce deal friction for global enterprise contracts and EU distribution.
What the PW Consulting report delivers (practical contents)
-
Proprietary revenue model with 2020–2025 historicals and scenario forecasts through 2032, including sensitivity runs on pricing, retention and new channel adoption.
-
Competitive playbooks and feature benchmarking for the leading global apps, with differentiated GTM options for premium and freemium strategies.
-
Regulatory thermostat: a feature‑level EU AI Act and privacy impact checklist, plus a regulatory remediation matrix and estimated time‑to‑conformity for high‑risk features.
-
M&A and partnership shortlists with valuation priors, integration risk profiles and example term sheets for strategic and financial buyers.
-
Operational toolkits: consumer research templates, UX/clinical validation protocols, implementation roadmaps for XR and wearable pilots, and an enterprise sales playbook.
-
90/180/365‑day execution plans tailored to investor, incumbent platform, and start‑up use cases to make the strategy operational immediately.
How clients are using this intelligence in 2026
-
CEOs and boards: to set three‑year capital allocation and inorganic growth targets aligned with projected market expansion.
-
Chief Product Officers: to prioritize roadmap items that increase monetization, reduce regulatory risk and improve retention.
-
Investors and corporate development: to identify acquisition targets that close capability gaps (AI, XR, clinical validation) and to model post‑deal synergies.
-
Legal and privacy teams: to operationalize compliance frameworks that enable rapid scaling into EU and enterprise markets.
Closing — what to do next
The mindfulness meditation apps market is no longer an emerging curiosity — it is a tangible commercial category with predictable growth and clear strategic levers. PW Consulting’s full report delivers the granular models, competitive intelligence and operational playbooks required to convert that growth into market‑leading outcomes.
Note: this briefing highlights the study’s strategic value while intentionally omitting granular segmentation tables and proprietary split metrics. Those detailed breakdowns (including regional, type and application splits, and the complete concentration analysis) are available in the full report and are designed to support transaction‑level and operational decisions in 2026.
For boards, investors and product leaders ready to move from insight to implementation, PW Consulting’s market study is designed as a working toolkit — not merely a narrative. Access the full analysis to obtain the data tables, scenario models and executable templates that underpin the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Mindfulness Meditation Apps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


