



PW Consulting: Potting Compound Market to hit USD 4,444.96M by 2032 at 3.4% CAGR

Potting Compound Market — Strategic Preview for 2026 Decision-Making (PW Consulting)
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, decision-oriented preview of our latest Potting Compound Market study. This briefing synthesizes the market trajectory, competitive positioning and regulatory dynamics that will determine winners and laggards in 2026 — while intentionally withholding the granular segment tables contained in the full report to preserve strategic value and prompt direct engagement for the underlying data.
Potting Compound Market
Market snapshot and trajectory
Using 2025 as our base year, the global potting compound market has shown steady expansion through the last half-decade and remains on a moderate-growth path through our forecast window. Key macro numbers from the study that should shape capital allocation and product strategy in 2026:
Potting Compound Market
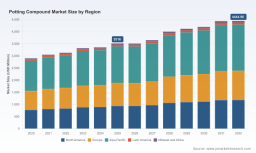
- The market grew from approximately USD 2,902.6 Million in 2020 to USD 3,516.0 Million in 2025 (base year).
- Our forecast period spans 2026–2032, during which the market is projected to grow at a compound annual growth rate (CAGR) of about 3.4%.
- By the end of the forecast horizon the global market is modeled to approach USD 4,444.96 Million (2032).
- Market concentration is moderate: the top 3 players account for roughly 38% of industry revenues; the top 5 for about 45% — a structure that enables both scale advantages and opportunities for nimble specialists.
Two subtle but important notes for 2026 planning: our baseline shows a near-term normalization in 2026 versus 2025 (a small adjustment reflecting supply-chain and pricing normalization), followed by steady expansion through the late 2020s. This pattern favors timely, selective investments rather than indiscriminate capacity build-outs.
Potting Compound Market
Why this study matters for 2026 corporate decisions
- Portfolio prioritization: the report quantifies where incremental volume and margin pools are likely to appear and which material types and performance attributes will command premium pricing.
- R&D and product roadmaps: it maps regulatory and application-driven specifications (e.g., flame retardancy, thermal conductivity, low-VOC, UV-curability) to commercial opportunity windows.
- Sourcing and procurement: it offers a cost-sensitivity model calibrated to recent feedstock volatility to inform hedging, supplier diversification and contract structuring.
- M&A and partnership screening: a focused set of acquisition targets and partnership archetypes is identified, with high-level valuation assumptions and integration risks.
- Go-to-market and pricing: the study provides commercial playbooks for OEM engagement, certification strategies and value-based pricing in high-performance niches.
Report contents — practical, action-ready deliverables
- Market sizing and 2020–2032 forecasts (total market and full segmentation — note: detailed split tables are accessible in the paid report).
- Demand-driver analysis across electronics, automotive, aerospace, industrial and adjacent verticals, including scenario-based demand ladders.
- Material technology canvas assessing epoxy, silicone, polyurethane and alternative chemistries against performance and cost vectors.
- Supply-chain heatmap with input-price sensitivity (we quantify the impact of epoxy resin feedstock volatility observed in early 2025).
- Regulatory compliance matrix covering UL 94, IEC family standards, RoHS and REACH, plus VOC restrictions and their commercialization implications.
- Competitive landscape with executive summaries and strategic positioning for leading suppliers.
- Commercial playbooks: channel segmentation, certification roadmaps, OEM sourcing requirements and country-level go-to-market considerations.
- Scenario analysis and three executable strategic playbooks for incumbents, challengers and private-equity-backed roll-ups.
- Practical appendices: technical test protocols, sample procurement contracts, and an interview-log of primary discussions with formulators, OEM engineers and procurement leaders.
Strategic implications and recommended actions for 2026
1) Investment timing & capacity decisions
With a mid-single-digit industry CAGR and a modest near-term flattening, 2026 is not the year for blanket greenfield buildouts unless tied to secured contracts. Recommended actions:
- Pursue modular, flexible capacity expansions (skid-mounted mixing lines, contract manufacturing partnerships) to capture upside without heavy fixed-cost commitments.
- Prioritize investments in finishing/dispensing capabilities (precision metering, vacuum-degassing, thermal management additives) that increase yield and margin on existing volumes.
2) R&D and product roadmap prioritization
Regulatory pressure (low-VOC and heavy-metal restrictions), safety standards (UL 94, IEC), and demanding thermal/flame requirements from electronics and power applications are creating a premium for performance chemistries. Recommended focus areas:
- Low-VOC, low-odor formulations and alternatives to restricted substances to meet RoHS/REACH trends.
- Thermally conductive yet electrically insulative blends; flame-retardant systems that meet UL94 V-0 and equivalent IEC tests.
- UV- and light-curable chemistries for rapid process cycles where application permits — an area of clear differentiation for formulators investing in curing technologies.
3) Procurement strategy and raw-material risk management
Epoxy and other resin feedstock price volatility in early 2025 materially affect margins. For 2026 we recommend:
- Implement multi-tier supplier agreements with indexed pricing bands and minimum-offtake protections.
- Develop strategic inventory buffers for critical monomers while avoiding long-term overexposure to spot pricing.
- Assess backward-integration options for specialty additives where scale and capex profiles make sense.
4) Commercial and channel playbook
Given the industry’s moderate concentration (CR3 ~38%, CR5 ~45%), scale and relationships matter — but there is also room for specialty players. For 2026:
- Win with technical services: invest in application labs and OEM co-development to shift the procurement conversation from price to total cost of ownership.
- Segment pricing by performance attributes (thermal, flame-retardance, cure-profile) and certify technologies to shorten sales cycles in regulated verticals.
- Leverage regional contract manufacturers for faster time-to-market in pockets where high-volume OEM demand is emerging.
5) M&A and partnership themes
Opportunistic M&A remains a key pathway to scale and capability access. Targets that consistently surface in our diligence include specialty formulators, additives providers and regional converters with strong OEM relationships. Due-diligence priorities should emphasize regulatory compliance histories, formulation IP, and customer concentration.
Competitive landscape — who you’ll be competing and collaborating with
The study profiles a set of incumbent and specialized competitors that collectively shape strategic options for suppliers and buyers. Representative players covered in the report include:
- Henkel AG & Co. KGaA (Düsseldorf) — established leader with recognized Loctite STYCAST and Loctite potting portfolios; notable for introducing next-generation polyurethane systems focused on industrial and power-electronics reliability (notably a product launch in January 2026 targeting harsh-environment applications).
- ELANTAS GmbH (Hanau) — specialist supplier of electrically focused potting and casting resins with deep traction in demanding protection applications.
- MG Chemicals (Vancouver) — nimble player recognized for flame retardant, thermally conductive and optically clear formulations.
- 3M Company (St. Paul) — global brand with mature Scotchcast family and strong channel reach into electrical infrastructure and service segments.
- Dymax Corporation (Torrington) — niche leader in UV- and light-curable encapsulants for high-throughput applications.
- Dow Inc. and Momentive Performance Materials — major raw-material and specialty-silicone suppliers whose formulations serve large industrial and electronics use-cases.
- Parker Hannifin / LORD, Electrolube, Aremco, Epic Resins — specialized formulators and performance-material providers that act as both competitors and potential acquisition targets depending on strategic fit.
The competitive map in the full report highlights capability clusters (e.g., UV-curing, high thermal conductivity, flame-retardant epoxies) and identifies white spaces where new entrants can realistically pursue premium positions.
Regulatory and materials dynamics to watch
- Standards and safety: UL 94 and IEC testing continue to be gating factors for adoption in electronics and appliance segments; meeting these standards shortens procurement cycles.
- Environmental compliance: RoHS/REACH and global VOC restrictions are pushing formulators toward lower-VOC systems and substitution of restricted additives.
- Input-price volatility: episodic swings in key resin feedstocks materially alter unit economics for formulators that lack hedging or flexible sourcing approaches.
How to use the full PW Consulting report (and what’s intentionally reserved)
This preview is designed to equip senior leaders with the strategic framing needed for 2026 decisions. The full report contains the granular intelligence that operational teams, M&A advisors and procurement should directly use — including:
- Detailed segmentation tables (by region, type and application) and quarterly demand curves.
- Company-level revenue estimates, product-level share assumptions and pricing curves.
- Raw-material cost models and sensitivity analyses down to specific monomer inputs.
- Supplier scorecards, validated interview transcripts and downloadable technical appendices.
To preserve the commercial value of those deliverables (and to enable confidential briefings), we have intentionally withheld the granular split values in this public preview. PW Consulting offers tailored briefings and bespoke workshops that walk buyers and sellers through the full dataset and its implications for specific strategic options.
Concluding guidance — a short playbook for 2026
In 2026, firms that combine nimble capacity strategies, targeted R&D in compliance-driven performance attributes, and disciplined procurement will outperform peers. The market’s moderate growth and concentration profile reward technical differentiation and smart commercial execution more than scale-alone gambits. Use the data in this preview to set priorities — then engage PW Consulting for the complete dataset and an execution roadmap customized to your risk profile and growth ambitions.
Contact PW Consulting to schedule a confidential briefing or to license the full Potting Compound Market report and its underlying datasets.
For detailed analysis of this topic, please visit the official page: Potting Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


