



PW Consulting: Coated Abrasive Market Poised for 5.97% CAGR Through 2032

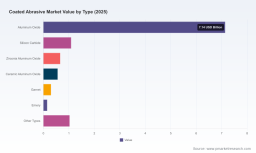
Coated Abrasive Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As organizations prepare 2026 budgets and strategic roadmaps, the coated abrasive market presents a mix of steady expansion, tectonic shifts in product expectations, and pockets of consolidation that demand targeted responses. Our benchmarking shows the global market expanded from roughly USD 8.1 Billion in 2020 to approximately USD 10.93 Billion in 2025, and is projected to continue expanding to about USD 16.44 Billion by 2032 — an underlying compound annual growth rate of 5.97% across the 2026–2032 forecast window. Market concentration is meaningful but not prohibitive: the top three suppliers account for around 38.5% of the market, and the top five for roughly 50.2% — a structure that rewards scale while leaving room for focused innovators and regional challengers.
Coated Abrasive Market
Why this matters for 2026 planning
-
Investment prioritization. Predictable mid-single-digit CAGR supports continued investment in capacity, but success will hinge on capital allocation toward product innovation, sustainability adaptation, and digital customer channels rather than undifferentiated volume expansion.
Coated Abrasive Market -
Supply-chain resilience becomes strategic. Recent and ongoing disruptions to key bonding chemicals and specialty inputs have shortened planning horizons and elevated the value of alternative sourcing, upstream partnerships, and on-shore buffer strategies.
Coated Abrasive Market -
Regulatory and procurement risk. Sustainability mandates and tightening product-compliance requirements are accelerating adoption of bio-based and certifiable product options. Firms that can combine performance with verifiable environmental credentials will unlock premium segments and preferred-supplier status with OEMs.
-
Automation-led demand shifts. Labor shortages and expanded robotic finishing lines are changing product specifications (durability under robotic cycles, dust control, integration with automated tooling). Suppliers who co-develop solutions with systems integrators capture higher-margin, recurring-revenue streams.
Market dynamics — from raw materials to end-use
The coated abrasive value chain is being reconfigured along several vectors simultaneously. On the supply side, intermittent shortages in specialty chemicals and adhesives have increased lead-time volatility and input-cost pass-through complexity. On the demand side, adoption patterns are diverging by end-use: traditional industrial metalworking continues to provide a volume foundation, while newer growth pockets are driven by automation, precision finishing in electronics and semiconductors, and sustainability-led replacement cycles in aftermarket and construction segments.
Regulation and certification are no longer peripheral considerations. Product launches in 2025 that emphasize biodegradability and life-cycle performance reflect an emerging baseline expectation among institutional buyers. Meanwhile, digital procurement and traceability features — exemplified by recent platform rollouts — are migrating from nice-to-have to procurement criteria tied to compliance and supplier rationalization programs.
Competitive landscape — what leading firms are doing
-
Saint‑Gobain Abrasives / Norton brand — A broad portfolio and recent inorganic expansion have reinforced global coverage, particularly in growth geographies. Their strategy appears focused on marrying range breadth with local manufacturing to protect margins against freight and input shocks. For incumbents, the lesson is clear: combine product depth with distribution proximity to remain relevant to industrial OEMs and large distributors.
-
3M — The company has sharpened its sustainability messaging with product innovation (e.g., biodegradable coated abrasives launched in August 2025). 3M’s playbook is to translate material science into brand-differentiated products, then leverage broad channel reach to scale adoption. Competitive response should evaluate where material innovation can create defensible features rather than commodity parity.
-
Norton Abrasives — While Norton remains a major brand within larger groups, recent investments in digital customer experience (new platform launched October 2025) demonstrate a shift to procurement-led value capture. The platform also aligns supplier capabilities with ISO-compliance requirements — a blueprint for suppliers seeking deeper integration into customer procurement workflows.
-
Klingspor — High-quality, application-focused product lines and strong woodworking-industrial finishing credentials make Klingspor a resilient player in premium niches. Their model underlines the commercial advantage of tightly aligned product-development with specific industrial workflows.
-
Mirka — A recognized leader in precision surface finishing, Mirka’s emphasis on systems (abrasives + tools + consumables) highlights how bundling raises switching costs and creates stickier customer relationships — particularly in OEM and high-precision subcontractor segments.
-
sia Abrasives — High output capacity and strong automotive and building-sector focus enable sia to compete on scale for contract manufacturing and large-scale projects. Their capability profile is instructive for firms evaluating contract manufacturing vs. in-house production decisions.
-
Carborundum Universal Limited (CUMI) — A leading regional player with a broad product catalog and strong presence in construction and industrial channels. Recent catalog updates and product portfolio refreshes keep the brand relevant for distribution-led growth in emerging markets.
Recent corporate moves with strategic implications
-
Product launches emphasizing biodegradability and sustainability (notably from a major global player in 2025) signal that product life-cycle attributes will be a point of competitive differentiation in procurement dialogues during 2026.
-
Acquisition activity in Asia by a leading European incumbent underscores the importance of strategic M&A to secure local capacity and reduce exposure to freight and input-price inflation.
-
Digital platform rollouts that embed compliance and procurement workflows are becoming a competitive moat. Expect an acceleration of supplier digitization projects as buyers demand traceability and easier re-ordering.
Strategic playbook for 2026
-
Prioritize product portfolios into three buckets: (1) high-performance systems for automation and precision finishing, (2) sustainability-certified offerings for regulated channels and green procurement, and (3) cost-optimized ranges for high-volume industrial applications. Allocate R&D and capex according to downstream margin potential, not historical volume alone.
-
Invest in supplier diversification and chemical-substitute R&D. A dual approach — securing alternative suppliers for key inputs while developing formulations that reduce dependency on constrained chemistries — materially reduces service-risk in 12–18 month planning horizons.
-
Embed digital procurement and compliance features into customer-facing platforms. Platforms that simplify ISO certification, batch traceability, and automated re-ordering convert technical product advantages into commercial stickiness.
-
Assess M&A and JV targets with an “access-to-technology” and “access-to-market” lens. Regional producers with strong channel relationships or unique material know-how offer faster paths to capability expansion than greenfield investments.
-
Develop partnerships with systems integrators and robotic suppliers. Co-engineering abrasive consumables for robotic finishing lines will be a significant value driver as automation adoption grows.
What the full PW Consulting report delivers (practical, actionable)
-
Transparent market-sizing and growth scenarios with sensitivity analysis that connects macro trends to unit economics and margin outcomes — enabling finance teams to stress-test 2026 capex proposals.
-
Commercial playbooks for supply chain resilience, including a prioritized list of alternative suppliers, suggested inventory buffers by risk-profile, and supplier scorecards tailored to abrasive-specific inputs.
-
Competitive benchmarking across product, price, channel, and service dimensions with go-to-market tactics for defending share or entering adjacent segments.
-
Innovation radar and R&D roadmaps that map material science advances to potential premium features and regulatory-ready product variants.
-
M&A heatmaps that prioritize targets by strategic fit (technology, geography, channel) and modeled synergy ranges to support deal conversations in 2026.
-
Operational playbooks for digitizing the customer interface, including procurement integrations, traceability workflows, and KPIs to measure commercial impact.
How to use this intelligence in boardrooms and procurement meetings
For CEOs and CFOs: use the market trajectory and scenario outputs to stress-test capital allocation between capacity, R&D, and digital transformation. For commercial leaders: adopt the segment-specific playbooks to prioritize sales coverage and channel investments in 2026. For procurement and operations: implement the supply-chain resilience checklist immediately to mitigate near-term input risks and ensure continuity for high-value contracts.
Closing — the strategic choice in 2026
The coated abrasive market offers a predictable growth backdrop combined with disruptive inflection points around sustainability, automation, and digital procurement. Success in 2026 will not be decided by scale alone; it will hinge on the ability to convert material science and digital capabilities into procured value — measurable through reduced total cost of ownership and improved compliance footprints for buyers. PW Consulting’s full Coated Abrasive Market report delivers the granular segmentation, country-level analytics, and downloadable models required to operationalize the strategies outlined here.
For the complete dataset, in-depth segment economics, and executable playbooks referenced in this preview — including the withheld granular splits and customer-level insights — visit our report page to access the full intelligence suite and downloadable decision-support tools.
For detailed analysis of this topic, please visit the official page: Coated Abrasive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


