



UGC Software Market to Hit USD 10.99B by 2032 with 10.6% CAGR — PW Consulting

User Generated Content (UGC) Software Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Industry Analyst, I present an executive preview of our new market research on the User Generated Content (UGC) Software market. This briefing is designed as a strategic “trailer”: it surfaces the essential macro trends, competitive positions, and actionable levers that should inform enterprise decisions in 2026, while intentionally withholding certain proprietary segment tables and vendor scorecards reserved for the full report.
User Generated Content (UGC) Software Market
Why this research matters for 2026
UGC software is no longer a niche marketing tool — it has become a foundational layer of contemporary commerce, customer experience, and brand trust architecture. Organizations making platform, vendor, and data governance decisions in 2026 must reconcile three concurrent shifts: accelerating AI-driven content collection and personalization, increasing regulatory scrutiny on AI/curated content, and the rising commercial value of shoppable, permissioned visual media.
User Generated Content (UGC) Software Market
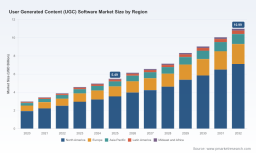
Our modeled market trajectory captures these dynamics. From a clearly observable expansion across 2020–2025, the market reached a material inflection point in 2025 (base year) and is forecast to grow at a 10.6% compound annual growth rate over the 2026–2032 horizon. The outcome is a near-doubling of market scale through the forecast period, underscoring both intensifying vendor activity and expanding buyer demand for integrated UGC capabilities.
User Generated Content (UGC) Software Market
High-level market picture (what leaders need to know)
- Growth profile: The market has expanded steadily through 2020–2025 and transitions into a mature acceleration phase in 2026, driven by enterprise adoption of UGC as a conversion and retention tool.
- Concentration: Market concentration is meaningful but not prohibitive — three vendors account collectively for a majority share of commercial activity, with the top five increasing that footprint. This creates a dual environment of stable incumbency and targeted opportunity for challengers with differentiated capabilities.
- Value drivers: The principal ROI levers for buyers are content authenticity and rights management, shoppable integrations that shorten commerce funnels, and AI-assisted moderation and tagging that reduce operational cost.
Dynamics shaping vendor selection and implementation
- AI as paradox: AI both unlocks scale (automated tagging, sentiment, visual recognition) and introduces new risks (hallucinations, synthetic content). Buyers must evaluate vendor approaches to provenance, explainability, and human-in-the-loop workflows.
- Regulatory noise and compliance priorities: Recent regulatory moves — for example, new rules requiring rapid removal of demonstrably harmful AI-generated content and explicit labeling of AI-curated media in some jurisdictions — elevate compliance from checklist to core capability. Vendors’ content governance, audit trails, and localization support will be decisive.
- Integration tax: UGC value accrues only when tightly integrated with commerce stacks, CDPs, and CX platforms. Procurement assessments should weight API quality, latency SLAs, and headless/rendering options equally with feature lists.
- Rights & moderation economics: Clear, auditable rights acquisition and automated moderation workflows materially affect total cost of ownership and legal exposure—features that have moved from “nice-to-have” to “must-have.”
Competitive landscape — strategic snapshots
The competitive set is diverse: from legacy e-commerce review platforms to AI-first personalization vendors and visual-content specialists. Below are targeted assessments of the primary vendors covered in our study. These snapshots synthesize public positioning, product focus, and strategic implications for enterprise buyers.
- Bazaarvoice (Austin, Texas) — Bazaarvoice is positioned as a robust e-commerce UGC collection and syndication platform. Its strengths are mature review workflows, retailer integrations, and an extensive syndication network. Strategic fit: organizations prioritizing scale of review distribution and cross-retailer consistency. Considerations: evaluate roadmap for AI curation and visual UGC expansion.
- Yotpo (New York, New York) — Yotpo presents an AI-augmented UGC stack covering reviews, social, and visual commerce. Strengths include tight e-commerce UX integrations and marketing automation. Strategic fit: DTC brands seeking embedded loyalty and conversion optimization. Considerations: probe for provenance controls and moderation latency under peak loads.
- Taggbox (Covina, California) — Taggbox emphasizes social feed widgets, reviews, and shoppable content aggregation across platforms. Strengths are flexibility in display formats and channel-agnostic aggregation. Strategic fit: event-driven, campaign-centric use cases and experiential marketing. Considerations: assess enterprise-grade governance and platform SLAs for high-traffic deployments.
- Emplifi (Columbus, Ohio) — Emplifi integrates UGC with social analytics, commerce, and broader CX capabilities. Strengths include an analytics-centric approach and cross-channel orchestration. Strategic fit: enterprises that require UGC insight to feed loyalty, CX, and service functions. Considerations: clarify data ownership models and cross-module interoperability.
- Nosto (Helsinki, Finland) — Nosto is recognized for AI-powered commerce experience and visual UGC personalization. Strengths include recommendation engines and visual merchandising tied to UGC. Strategic fit: retailers investing heavily in personalization at scale. Considerations: request transparency on model training data and regional regulatory compliance readiness.
- PowerReviews (Chicago, Illinois) — PowerReviews focuses on ratings and reviews with conversion optimization and syndication capabilities. Strengths lie in review authenticity features and conversion analytics. Strategic fit: brands focused on review-led conversion strategies with large SKU catalogs. Considerations: understand how visual UGC and influencer-driven content are supported.
- Crowdriff (Toronto, Ontario) — Crowdriff specializes in visual content discovery, management, and publishing, with particular traction in travel, hospitality, and retail. Strengths include visual search and rights-cleared publishing. Strategic fit: destination marketing and retail brands that rely on aspirational imagery. Considerations: evaluate commerce linkage maturity for direct shoppability.
Recent events and regulatory signals to watch in 2026
- Platform innovation: New entrants and product launches continue to change the competitive calculus. For example, early-2026 product introductions aimed at capturing text-based experience data are expanding the types of consumer narratives that can be monetized or moderated.
- Regulatory accelerants: Jurisdictions are moving quickly to impose obligations around AI-generated content — including removal timeframes for harmful content and mandatory labeling of AI-curated media. These measures shift vendor evaluations toward demonstrable auditability and localization features.
- Operational implications: The combined effect of product innovation and regulation increases the premium on vendors that can demonstrate low-latency moderation, strong provenance, and clear rights management across country boundaries.
What the full report delivers (practical, actionable components)
Our full market study is built for practitioners and C-suite decision-makers who need to turn insight into execution in 2026. Deliverables include:
- Comprehensive market sizing and forecast (2020–2032) with sensitivity scenarios and CAGR decomposition by driver.
- Competitive landscaping that pairs vendor capabilities with use-case fit, implementation complexity, and buying signals.
- Go-to-market and procurement playbooks: RFP templates, vendor scorecards, and negotiation levers tailored to enterprise priorities.
- Technical integration blueprints and API evaluation checklists for commerce, CDP, CMS, and moderation pipelines.
- Actionable ROI and TCO models with benchmarked assumptions for content moderation, rights clearance, and shoppable conversion uplift.
- Regulatory compliance annex with jurisdictional heatmaps, sample contractual clauses, and audit trail templates aligned to 2026 regulations.
- Deployment roadmaps and pilot designs to validate value quickly while managing legal and operational risk.
- Curated executive briefs and one-page decision frameworks for board and procurement committees.
How to use this briefing to act in 2026
- Prioritize a rights-first evaluation: Require vendors to demonstrate rights acquisition, verifiable provenance, and chain-of-custody for visual assets as a gating criterion.
- Make AI governance concrete: Insist on explainability, human-in-the-loop review thresholds, and remediation SLAs tied to regulatory timeframes in your contracts.
- Prize integration over point features: Choose vendors that reduce integration lift and offer clear pathways into your commerce and CX ecosystems.
- Pilot for legal and commercial outcomes: Structure initial engagements as limited-scope pilots with measurable conversion and compliance KPIs before rolling out wholesale.
Closing — a strategic prompt
The UGC software market in 2026 sits at an inflection of opportunity and obligation. Growth is robust — reflecting sustained enterprise investment — but the competitive and regulatory environments are evolving rapidly. This briefing surfaces the strategic signposts leaders must use to select vendors, design pilots, and scale responsibly.
For the complete segmentation tables, provider scorecards, and the proprietary appendices that translate these insights into executable procurement and integration artifacts, access the full PW Consulting report. Our research includes the granular data and templates required to turn the market’s projected 10.6% CAGR and the full 2020–2032 sizing into a concrete 12–18 month action plan for your organization.
For detailed analysis of this topic, please visit the official page: User Generated Content (UGC) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


