



PW Consulting: V2G Market to Reach USD 344.8 Million by 2032

Vehicle-to-Grid (V2G) Market 2026: Strategic Imperatives for Corporates — A PW Consulting Preview
As the energy transition accelerates, Vehicle-to-Grid (V2G) has moved from niche pilots to the threshold of commercial scale. Our PW Consulting Vehicle-to-Grid Market study (base year 2025) synthesizes quantitative forecasting, policy overlays, commercial pilots and supplier due diligence into a decision-grade guide for corporate leaders planning capital allocation, product roadmaps, and market entry in 2026. This preview explains why V2G should be on every energy, mobility and asset-management executive’s 2026 agenda — and how our full study equips organizations to act with confidence.
Vehicle-to-Grid (V2G) Market
Why 2026 is the Inflection Year
Two converging forces create a unique window for V2G value capture in 2026: regulatory standardization and improving economics. Binding technical requirements that mandate bidirectional communication in new/renovated charging infrastructure are scheduled to take effect across major jurisdictions, effectively turning “nice to have” bidirectionality into a compliance and market-access requirement. Separately, recent policy moves — for example the removal of double grid fees in key markets — materially improve the commercial case for exporting vehicle-stored energy back to the network.
Vehicle-to-Grid (V2G) Market
Price signals are supportive. Global residential electricity rates and wholesale futures in 2026 have produced realistic revenue pathways for aggregate V2G fleets to monetize arbitrage and ancillary services. These conditions convert theoretical V2G value into executable business cases for utilities, aggregators, OEMs and large fleet owners.
Vehicle-to-Grid (V2G) Market
Market Momentum — The Macro Picture
Our bottom-up model traces the V2G market from early commercial traction in 2020 through the 2025 base year, and projects forward across a 2026–2032 forecast horizon. The market expanded from the low hundreds of millions (USD, revenue unit: Million) in 2020 to roughly USD 215.0 Million by the 2025 base year; projected growth accelerates thereafter, reaching an estimated USD 344.8 Million by 2032. The forecast is driven by a compound annual growth rate (CAGR) of approximately 6.98% over the modeled forecast period — a pace signaling steady, platform-enabled adoption rather than exponential consumer-led uptake.
Two implications follow: first, V2G is not a rapid, consumer-driven gold rush; it is a multi-stakeholder systems play that rewards strategic positioning and partnerships. Second, early movers who secure grid access, aggregation capacity, and regulatory alignment will capture durable, higher-margin revenue streams as the market matures.
Competitive Landscape — Who Matters and Why
The V2G ecosystem today is characterized by meaningful technical differentiation and a fragmented supplier base. Market concentration metrics confirm a low consolidation state: the top-three and top-five providers hold modest combined shares, reflecting room for partnership, consolidation and regional champions. For corporates this means the competitive battlefield will be defined less by price alone and more by integration capability, regulatory footprint, and data/aggregation competence.
- Technology providers and aggregators: Players such as Nuvve (GIVe platform) and Virta emphasize fleet aggregation, bidirectional control stacks and virtual power plant services — capabilities essential for monetizing grid services. Recent organizational moves (e.g., Nuvve’s deployments and local leadership appointments in Japan in 2026) underscore a push into critical new geographies.
- Hardware and industrial integrators: ABB and The Mobility House specialize in bidirectional charging hardware and integrated systems — from chargers to V2G control software — enabling scale deployments for commercial, industrial and fleet customers. Standalone hardware competence without software and aggregation partnerships will limit addressable value.
- OEMs and ecosystem partners: Vehicle manufacturers and utilities (e.g., Nissan launching affordable bidirectional charging solutions, and energy groups such as E.ON and Enel) are closing the loop between vehicles, tariffs and customer propositions. Examples in early 2026 show OEMs and energy companies bringing market-ready bundles to residential and commercial customers.
- Retail energy innovators: New tariff and platform experiments by energy retailers (e.g., Octopus Energy’s Powerloop) illustrate the consumer-facing business model evolution: V2G as a differentiated retail product combining hardware incentives, smart tariffs and customer engagement.
These firms are all active in the field through product launches, deployments and commercial pilots — but none alone dominates the space today. That presents an opening for thoughtful strategic engagement, whether through JV models, white-label partnerships, or targeted M&A focused on aggregation, software IP and market access.
What the PW Consulting Report Contains — Practical Deliverables
Our full study is designed as an executable toolkit for 2026 decision-making. Highlights include:
- Forecast model with scenario branches (baseline, accelerated policy adoption, and slow consumer uptake) and sensitivity levers for energy prices, vehicle-to-charger adoption rates, and tariff structures.
- End-to-end value chain analysis mapping revenue pools by use case (e.g., residential arbitrage, ancillary services, demand-side management), supplier roles, and margin profiles.
- Commercial playbooks: go-to-market options for OEMs, utilities, fleet operators and retailers including pricing templates, partner scorecards, pilot-to-scale transition checklists, and B2B contract clauses for aggregation and energy settlement.
- Regulatory and compliance matrix tied to product design — including implementation pathways for ISO 15118-20 and jurisdictional fee structures — to accelerate product certification and tariff approval processes.
- Technology assessment and interoperability map: charger and vehicle compatibility matrices, cyber-security best practices, and data governance frameworks required for grid services participation.
- Vendor diligence annex: comparative profiles, recent developments, patent and IP snapshots, and M&A heatmaps identifying likely consolidation targets.
- Financial tools: TCO calculators for fleet and residential deployments, capital expenditure planning templates, and investment cases capturing bidirectional hardware costs, software-as-a-service revenue, and O&M assumptions.
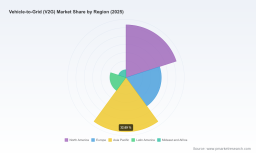
The full report contains granular regional and application splits, vendor scorecards and downloadable models. In this preview we intentionally withhold those segmented figures to preserve the value of the detailed datasets and proprietary scoring methods included in the subscription edition.
Practical Strategic Recommendations for 2026 Decision-Makers
- Utilities and system operators: Prioritize partnership pilots with aggregators that can demonstrate real-time dispatch and settlement capability. Use 2026 commercial pilots to validate revenue stacking (ancillary + arbitrage + capacity) and to influence tariff design that supports bidirectional participation.
- OEMs: Embed V2G capability into product roadmaps where it aligns to customer value and regional regulation. Consider white-label charging partnerships and enable flexible warranty/maintenance models for bidirectional hardware to lower customer adoption friction.
- Fleet operators and large energy buyers: Test aggregation contracts that offer predictable revenue streams; use short-term procurement to build operational experience and refine fleet management practices before committing to large-scale capital expenditure.
- Charge-point operators and hardware vendors: Invest in software layers and open APIs for marketplace participation. Hardware-only strategies are increasingly fragile: the monetizable economics of V2G come from orchestration, settlement and QoS guarantees.
- Investors and corporate development: Focus M&A on companies that combine aggregation software with documented grid revenue performance and regulatory footprints in priority markets. Early-stage investments should prioritize IP around bidirectional control algorithms, cyber-resilient communications, and settlement engines.
Risk & Mitigation — What to Watch in 2026
- Regulatory timing and implementation risk: Mandates and technical standards are evolving; companies should build flexible architectures that can adapt to ISO 15118-20 implementations and AFIR timelines without costly hardware retrofits.
- Revenue stacking dependence on price signals: V2G returns are sensitive to electricity price volatility and ancillary market design. Mitigation: secure pre-commercial agreements with grid operators and explore revenue guarantee structures during pilot stages.
- Interoperability and cybersecurity: As multiple vendors and vehicle platforms interact, interoperability failures or breaches could stall deployments. Recommended mitigation includes vendor certification requirements, layered security designs, and third-party interoperability testing.
- Customer acceptance and behavioral risk: Residential adoption depends on perceived battery degradation risk and simplicity of proposition. Transparent warranty terms and intuitive tariffing are essential.
Signals from the Field — 2026 Developments Worth Noting
- OEM-led consumer product launches (e.g., Nissan’s affordable bidirectional chargers in early 2026) are shifting V2G from research labs into retail channels.
- Energy-utility collaborations (e.g., BMW/E.ON residential V2G commercial offers launched in Germany) demonstrate how tariff innovation can accelerate customer take-up when paired with OEM hardware commitments.
- Localized deployments (for example, bidirectional charger installations using Quasar 2 technology) show real-world interoperability tests between hardware vendors and vehicle models — useful early lessons for scale rollouts.
- Corporate moves into key markets (e.g., Nuvve’s organizational expansion in Japan) reveal where operator confidence in local market structures is rising.
Conclusion — What PW Consulting Recommends for 2026
V2G in 2026 is a strategic opportunity best pursued with a systems view. The macro trajectory — reflected in our forecasted growth to the end of the decade and a near-7% CAGR — favors orchestrators who can align vehicle OEMs, charge-point vendors, energy retailers, and grid operators. For executives deciding budgets and partnerships this year, PW Consulting recommends a three-track approach: (1) secure pilot-level technical and commercial proof points in priority markets; (2) build or partner for aggregation and settlement capabilities; and (3) embed regulatory foresight into product design to avoid costly rework when standards take effect.
Our full report provides the actionable segmentation, vendor scorecards, and financial models necessary to translate these strategic imperatives into procurement decisions and investment theses. For teams preparing 2026 capital plans, the report functions as both roadmap and risk register — designed to shorten time-to-value while preserving optionality as the market consolidates.
Next Steps
Contact PW Consulting to access the complete V2G Market study, including the downloadable forecast model, regional and application splits, detailed vendor profiles and custom advisory options tailored for executives preparing 2026 strategies. The market is at an inflection point — firms that prepare now will be best positioned to convert nascent grid services into recurring, defensible revenue streams.
For detailed analysis of this topic, please visit the official page: Vehicle-to-Grid (V2G) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


