



PW Consulting: AWG Market to Reach USD 300 Million by 2032 at 8.5% CAGR

Arrayed Waveguide Grating (AWG) Market: Strategic Outlook for 2026 Decision‑Makers
As AWG-enabled photonics moves from niche telecom applications into mainstream data‑center interconnects, coherent optics, and integrated photonic platforms, 2026 will be a pivotal year for corporate strategy. This briefing — drawn from PW Consulting’s latest AWG Market research (base year 2025; historical 2020–2025; forecast 2026–2032) — synthesizes the practical intelligence executives need to convert technical signals into commercial advantage.
Arrayed Waveguide Grating (AWG) Market
Data‑driven snapshot you can act on
-
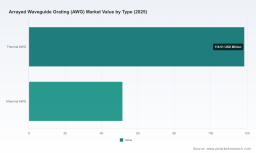
Measured in USD (Million), the AWG market expanded materially through the early 2020s, growing from the low‑hundreds of millions to a base‑year size of USD 170 Million in 2025.
Arrayed Waveguide Grating (AWG) Market -
Our forecast horizon (2026–2032) assumes a compound annual growth rate (CAGR) of 8.5%, with the market tracking toward an approximate USD 300 Million size by 2032 under the base scenario.
Arrayed Waveguide Grating (AWG) Market -
Market concentration remains moderate: the top three suppliers account for roughly 30% of global share, while the top five reach about 45% — a structure that favors nimble specialists and opportunistic consolidation alike.
These headline metrics are intended to inform capital allocation, product roadmaps, and M&A screening in 2026. The full report contains the granular segmentation, pricing bands, and channel economics required to convert these directional numbers into executable plans.
Why this research matters for 2026 decisions
-
Standards and regulation are converging on AWG performance thresholds. Recent standards work (e.g., channel grids and spacing) and operator specifications for insertion loss and crosstalk are establishing pass/fail gates that will determine which modules scale in hyperscale deployments.
-
Thermal management is a commercial battleground. Athermal AWG solutions remove active temperature control from the bill of materials and operations, creating a durable OPEX advantage for outdoor and uncontrolled environments. The implications span product engineering, procurement, and field operations.
-
Manufacturing complexity and labor intensity remain high. Wafer‑scale AWG fabrication requires cleanroom capacity, specialized photonic engineers, and strict process control — a barrier that constrains rapid commoditization and shapes supplier selection.
-
Growth is uneven across end‑use drivers. Internet backbone upgrades, data center interconnects, and enterprise optical fabric programs are each on different adoption curves. Strategic planners must align product features (e.g., channel spacing, athermal behavior, uniformity) with the precise requirements of target use cases.
Key dynamics shaping 2026–2032
-
Standards alignment: ITU‑T grids and Ethernet developments (e.g., large‑bandwidth datacenter optics) are driving demand for specified channel spacings and filter performance. Suppliers that pre‑qualify products to these standards shorten buying cycles and reduce qualification risk.
-
Regulatory and procurement requirements: Data center interconnect specifications increasingly mandate low insertion‑loss uniformity and stringent crosstalk limits for cascaded AWG chains. These technical barometers are now commercial gates for hyperscalers and telecom operators.
-
Technology tradeoffs: Substrate choice (silica, PLC, polymer, silicon photonics) defines the trade space: cost, thermal behavior, channel density, and integration potential. Different substrates appeal to different buyers — and companies that can span more than one technology stack have new cross‑selling opportunities.
-
Manufacturing and supply risk: High precision fabrication concentrates value around foundries with appropriate tooling and skills. Outsourcing strategies, IP protection, and dual‑sourcing are critical levers for manufacturing‑heavy players.
Competitive landscape — what to watch in 2026
The AWG supplier ecosystem is composed of distinct archetypes: silicon‑photonics integrators, PLC and silica module specialists, polymer/SoS athermal vendors, and niche optics houses. Below we summarize strategic postures for key players featured in our global coverage.
-
Aloe Semiconductor (Middletown, NJ, USA) — Focused on silicon photonic integrated circuits that embed AWG functions alongside active components. Strengths: integration density, roadmap alignment with coherent optics and transceiver OEMs. Strategic risks: foundry dependences and thermal sensitivity at scale.
-
Bright Photonics (Eindhoven, Netherlands) — IP and prototyping specialist offering AWG cores and modules for custom foundry runs. Strengths: rapid prototyping, access to European photonic ecosystems, and IP flexibility. Strategic play: act as an innovation bridge between universities/foundries and systems OEMs.
-
Agilechip Photonics (Zhongshan, China) — Manufactures PLC‑based AWGs, including athermal variants for DWDM, CWDM, and data‑center optics. Strengths: manufacturing scale and cost competitiveness in high‑volume segments. Watch: globalization efforts and customer qualification timelines outside local markets.
-
SENKO Advanced Components (Japan) — Producer of polymer and SoS athermal AWG modules with a focus on DWDM mux/demux uniformity. Strengths: field‑proven athermal designs and strong OEM relationships in Asia. Opportunity: lead in outdoor/uncontrolled deployments where OPEX matters most.
-
AC Photonics (United States) — Silica‑on‑silicon athermal AWG specialist targeting 100/150 GHz DWDM coherent markets. Strengths: high channel uniformity and alignment to coherent telecom requirements. Strategic runway: move up the value chain into subsystem integration for coherent transceivers.
-
engionic Fiber Optics (Germany) — Niche high‑performance photonic component specialist. Strengths: deep engineering capabilities and tailored solutions for demanding optical subsystems. Strategic fit: attractive partner for customized, high‑margin applications.
Collectively, these players demonstrate the sector’s heterogeneity: technology specialization, geography, and business model diversity. For buyers and investors in 2026, supplier selection will hinge on technology fit, qualification velocity, and the supplier’s ability to manage manufacturing and supply risk.
What PW Consulting’s full report contains (practical deliverables)
-
Market sizing and forward forecasts (2026–2032) with scenario sensitivity analyses that stress test CAGR assumptions against supply disruptions, standard shifts, and hyperscaler adoption — enabling realistic upside/downside planning.
-
Segmented demand drivers by use case, with a procurement playbook for qualifying AWG modules against operational KPIs (including insertion loss uniformity and crosstalk thresholds mandated by data center specifications).
-
Technology maps that compare substrate tradeoffs (silicon photonics, silica, PLC, polymer/SoS), product roadmaps, and cost drivers to inform product‑level decisions and make/buy debates.
-
Supplier scorecards, benchmarking, and a prioritized M&A target list — with commercial due diligence templates and red‑flag indicators for intellectual property, foundry access, and qualification backlog.
-
Operational guidance: sample RFP language, test‑plan checklists tethered to IEEE/ITU‑T norms, and capex/OPEX models that quantify the lifetime savings of athermal modules in uncontrolled environments.
-
Scenario playbooks for 2026 procurement cycles: supplier negotiation levers, dual‑sourcing roadmaps, and pilot program designs to de‑risk deployment at scale.
Actionable recommendations for 2026
-
For OEMs and subsystem integrators: prioritize athermal solutions where the lifetime energy and thermal management cost outweigh incremental BOM savings. Pre‑qualify at least two substrate technologies to avoid single‑technology risk.
-
For hyperscalers and carriers: insist on supplier compliance to industry performance gates and include staged acceptance tied to field metrics (insertion loss, crosstalk) to accelerate vendor accountability.
-
For investors and private equity: target consolidation candidates that own differentiated IP or exclusive foundry access. The market’s CR3/CR5 profile indicates room for bolt‑on value creation without competing on low‑margin commoditized products.
-
For foundries and contract manufacturers: invest in wafer‑scale process control and workforce development — these are persistent supply constraints that will command premium contracting terms with OEMs.
Intentional withholding — why you should read the full study
In keeping with our “trailer” approach, this article deliberately highlights strategy, dynamics, and actionable themes while withholding granular subsegment tables, regional breakdowns, and unit‑price banding that are essential for procurement negotiation and precise financial modeling. The full PW Consulting AWG Market report supplies those confidential line items, detailed supplier cost models, and buyer‑specific scenario outputs to convert strategic intent into executable plans.
Next steps
-
Use the high‑level intelligence here to set internal priorities for 2026 (standards alignment, athermal pilots, supplier due diligence).
-
Engage PW Consulting for a tailored briefing that maps the report’s granular data to your product roadmap, procurement calendar, and M&A thesis.
AWG technology is no longer a peripheral component — it is a gating factor for future optical architectures. In 2026, the right combination of standards readiness, manufacturing resilience, and product differentiation will separate leaders from followers. PW Consulting’s full study provides the segmented facts and decision tools you need to act with conviction.
For detailed analysis of this topic, please visit the official page: Arrayed Waveguide Grating (AWG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


