



PW Consulting: Native Starches Market Reaches USD 24.71 Billion in 2025

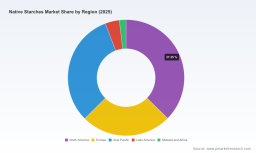
Native Starches Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As companies prepare strategy roadmaps for 2026, native starches sit at the intersection of food innovation, industrial reformulation, and sustainability-driven supply chain transformation. PW Consulting’s forthcoming Native Starches Market study (base year 2025; forecast 2026–2032) synthesizes market dynamics, competitor moves, and risk vectors into an actionable framework for C-suite and corporate development teams. This preview outlines the strategic value of the full study, highlights the high-level market trajectory, and summarizes competitive and operational flashpoints that will determine winners in the next planning cycle — while preserving the granular segment intelligence available in the full report.
Native Starches Market
Why this study matters for 2026 decision-making
-
Clear market momentum: Between the historical window and the forecast horizon, the native starches market exhibits steady expansion underpinned by demand in food and adjacent industrial applications. The study’s baseline shows multi-year growth culminating in a robust outlook through 2032, driven by product reformulation, label-friendly ingredient demand, and selective industrial uptake.
Native Starches Market -
Actionable foresight for capital allocation: With a compounded annual growth rate of approximately 5.05% across the forecast window, the market is neither commodity-tame nor hyper-volatile — a profile that favors disciplined capacity investments, targeted R&D, and partnership-led expansion over indiscriminate greenfield buildouts.
Native Starches Market -
Competitive and regulatory inflection points: Fragmented market structures, certification trends, and raw-material cost variability create pockets of premium opportunity (e.g., label-friendly, non-GMO, sustainably certified starches) and downside risk (emissions, compliance, input-price shocks). The report prioritizes these themes for 2026 planning cycles.
Market trajectory at a glance
PW Consulting’s consolidated market model charts a recovery-and-growth arc. The market expanded through the early 2020s, accelerating toward the 2025 baseline. From that base, our forecast anticipates steady growth through 2032, driven by incremental gains across food, industrial, and specialty use-cases. The model is built from bottom-up demand drivers, price and volume scenarios, and supply-side capacity adjustments — producing a mid-case consistent with the ~5% CAGR noted above. Readers should treat this preview as directional; the full report contains the underlying sensitivity analyses and scenario permutations used to derive the headline projection.
What’s in the full report — practical content for executives
-
Executive dashboard: concise KPIs, market sizing and growth drivers, and three investment-case archetypes for roll-up decisions in 2026 (capacity-led, specialty-led, or channel-led).
-
Methodology and data appendix: transparent sourcing, modeling assumptions, and reconciliation of global trade versus domestic consumption flows for robust valuation work.
-
Segment playbooks: go-to-market playbooks for core product types and end-use clusters, with recommended pricing strategies, technical dossier checklists, and customer segmentation matrices.
-
Supply chain deep dives: supplier maps, procurement levers and hedging templates, cold-chain and processing bottleneck analysis, and a procurement playbook tailored to agricultural-commodity input risk.
-
Regulatory & sustainability toolkit: certification pathways (including renewable-carbon and mass-balance schemes), emissions compliance checklists, and cost-benefit analysis for sustainability investments.
-
Competitive intelligence: company profiles, recent developments, an M&A radar, and a 12–24 month action calendar you can apply directly to business development and investor outreach.
-
Scenario & sensitivity analyses: upside and downside market scenarios tied to raw-material price shocks, substitution trends, and rapid adoption of label-friendly alternatives.
Competitive landscape — what incumbents and challengers are doing
The native starch arena is characterized by a mix of global ingredient houses, regionally strong cooperatives, and specialized processors. Overall market concentration remains modest; leading groups do not fully dominate the space, leaving room for agile competitors and niche specialists to capture premium segments. The CR3 and CR5 metrics we track underscore a marketplace where scale matters for raw-material access and cost-efficiency, but where differentiation and technical capabilities deliver outsized margins.
-
Cargill, Incorporated — A large-scale integrator with broad native-starch capabilities across multiple botanical sources. Cargill’s strength lies in its upstream raw-material footprint and its ability to integrate starch offerings into broader food-ingredient platforms for texturizing and thickening.
-
Roquette Frères — A major product innovator with a wide native starch portfolio and a strategic tilt toward label-friendly and plant-based credentials. Recent product introductions and certification achievements evidence Roquette’s push into differentiated native starch formats tailored to confectionery and coating applications.
-
AGRANA Beteiligungs AG — A producer focused on potato, corn, and wheat pathways, recently active on capacity expansion through partnership models. AGRANA’s joint-venture approach illustrates how mid-sized processors can scale selectively to serve European and export markets.
-
Emsland Group, Royal Avebe, KMC Ingredients, and MGP Ingredients — Collectively, these companies represent the cooperative and specialist cohort, leveraging botanical expertise and regional supply chains to serve both food and industrial needs with focused portfolios.
These profiles demonstrate three broad competitor archetypes: integrated multinationals that prioritize scale and cross-product bundling; specialty processors that win on botanical or process expertise; and cooperative models that secure raw-material reliability. Each archetype implies distinct strategic levers for 2026 — from vertical integration and long-term supply contracts to premium product development and co-investment with growers.
Recent developments that shape 2026 tactics
-
Product innovation is accelerating. A notable example is the launch of thermally soluble, label-friendly starches designed for confectionery and coatings — a category that opens reformulation opportunities for FMCG manufacturers seeking cleaner labels without sacrificing functionality.
-
Certification and sustainability credentials are becoming table stakes. Leading producers are securing renewable-carbon and mass-balance certifications to access sustainability-driven procurement programs and to mitigate buyer-level ESG risk.
-
Capacity expansion via partnerships: joint ventures and capacity-sharing agreements indicate a preference for capital-light scaling when demand is uncertain. Such structures are efficient ways to increase throughput while preserving financial flexibility.
-
Compliance and legacy environmental liabilities remain an operational risk. Historical regulatory actions in related processing segments serve as reminders that emissions and permitting exposures can carry balance-sheet and reputational costs if not proactively managed.
Operational levers for 2026 — what we recommend
-
Prioritize product differentiation over scale-first plays. Invest in label-friendly formulations and specialty botanical formats where margin expansion is demonstrable.
-
Lock in raw-material security with hybrid sourcing: combine long-term contracts, local cooperative partnerships, and strategic inventory buffers to reduce exposure to agricultural volatility.
-
Make certification a commercial enabler. ISCC-style and similar certifications are increasingly embedded in buyer specs; the incremental cost of certification often pays back through access to higher-margin customers.
-
Evaluate partnerships for capacity flexibility. JVs and tolling arrangements offer a lower-risk path to expand capacity into new geographies or product formats.
-
Embed emissions and compliance due diligence into M&A and capex approvals to avoid legacy liabilities that erode ROI.
-
Run a price–volume sensitivity analysis for product portfolios to understand margin resilience under input-price spikes — and design pass-through mechanisms for key customers.
How PW Consulting supports execution
Our full Native Starches Market study is designed as an execution tool, not just an analytical document. Clients receive modular deliverables that can be deployed directly into investment committees, procurement negotiations, or R&D prioritization workshops. Deliverables include a one-page investment memo, a 12-month commercialization sprint plan, supplier scorecards, and a tailored risk-heatmap aligned with corporate risk tolerances.
This preview intentionally omits the granular regional and application-level split tables, price-by-origin matrices, and the full company-level financial comparatives that our subscribers rely on for transaction and operational work. Those elements are available within the full report package to preserve the commercial value of proprietary modeling.
Next steps — using the preview to inform 2026 plans
-
Use the headline CAGR and trajectory to update medium-term demand assumptions in your strategic planning cycle, replacing ad-hoc estimates with a scenario-based approach.
-
Leverage competitor archetypes to stress-test your capability gaps: where do you compete on scale, where do you compete on specialty, and where should you consider partnerships?
-
Institute a short-term tactical plan (90–180 days) to shore up raw-material sourcing and to scope certification projects that can be operational by late 2026.
-
Contact PW Consulting for an executive briefing and a customized extraction of the report’s playbooks — including the confidential segmentation tables and price-sensitivity models that will be decisive for M&A and capex decisions.
In sectors where small formulation benefits compound across thousands of SKUs, having the right market intelligence is the difference between margin recovery and margin erosion. PW Consulting’s Native Starches Market study gives you that intelligence packaged for decision-making in 2026 — rigorous, operational, and calibrated to the realities of agricultural sourcing and ingredient innovation.
For detailed analysis of this topic, please visit the official page: Native Starches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


