



PW Consulting: Animal Feed Ingredients to hit USD 52.9B by 2032 at a 3.6% CAGR

Animal Feed Ingredients Market 2026: Strategic Briefing for Executive Decision-Making
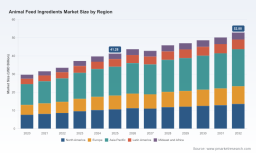
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, forward-looking briefing designed to equip C-suite and business-unit leaders with the strategic context they need to make high-confidence decisions in 2026. Our full Animal Feed Ingredients Market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — synthesizes hard market sizing, competitive dynamics, regulatory shifts, and raw-material risk to convert market intelligence into executable options. The market we track expanded from roughly USD 29.7 billion in 2020 to about USD 41.3 billion in the 2025 base year, and it is forecast to grow at a compound annual growth rate of 3.6% toward the 2032 horizon (reaching an estimated USD 52.9 billion). This macro trajectory frames the near-term choices executives must confront in 2026.
Animal Feed Ingredients Market
Why this briefing matters for 2026 decisions
-
Timing and resource allocation: With the market in a mid-cycle growth phase, managers face trade-offs between volume-led expansion and margin-protection investments (e.g., precision additives, quality assurance, logistics). Our study clarifies the return profiles of those alternatives under multiple price and regulation scenarios.
Animal Feed Ingredients Market -
Innovation window: Recent regulatory acceleration in several jurisdictions has shortened approval timelines for microbiome- and emissions-related additives, compressing the window for first-mover advantage. Companies that strategically align R&D, regulatory affairs, and commercialization will capture disproportionate value from premium additives and differentiated formulations.
Animal Feed Ingredients Market -
Supply-chain choreography: Volatility in grains and oilseed markets, coupled with evolving trade policy in priority export markets, means procurement strategy is now a competitive lever rather than a back-office function. Executives must decide whether to double down on vertical integration, secure offtakes, or diversify supplier bases in 2026.
Topline market dynamics
The animal feed ingredients market shows resilient, steady growth: from roughly USD 29.7 billion in 2020 to USD 41.3 billion in our 2025 base year and continuing upward to an estimated USD 52.9 billion by 2032 under our central-case projection (CAGR ~3.6%). This is not a hyper-growth theme, but it is large, strategic, and increasingly sophisticated — where incremental improvements in feed conversion, animal health, and regulatory compliance translate directly into meat, dairy, and aquaculture producers’ margins.
Three structural forces shape outcomes in 2026:
-
Cost pass-through pressure and raw-material cycles: Grain and oilseed price dynamics remain the primary determinant of short-run margin swings for conventional ingredient classes. Commodity prices moderated in 2025, and 2026 projections show continued stability in certain grains — an opportunity for processors and integrated suppliers to optimize mix and capture margin.
-
Shift from commodity to specialty: Growth in value-added feed additives, enzymes, amino acids, and targeted premixes is outpacing commodity volumes in many channels as producers seek productivity and sustainability gains. Regulatory facilitation of microbiome-focused solutions further accelerates adoption.
-
Regional policy inflections: Trade and fiscal policy moves in key import and export markets are re-shaping logistics economics — creating new export corridors while compressing margins in previously protected niches.
Regulation and raw-material signals you cannot ignore in 2026
-
Shortened approval timelines for gut- and emissions-focused inputs: A recent regulatory initiative has materially reduced time-to-market for products that meaningfully alter the gut microbiome or reduce enteric emissions. For strategy teams, this changes pipeline prioritization — invest in categories with accelerated approval and first-to-market potential.
-
Grain and oilseed pricing context: Stable-to-moderate grain prices observed in 2025 and similar 2026 projections create a favorable backdrop for demand recovery in sensitive livestock segments. However, soybean meal price volatility remains a persistent input risk; hedging and diversified sourcing should be part of any procurement playbook.
-
Trade policy shifts: Fiscal and tariff policy changes in selective emerging markets are opening up export opportunities and altering landed cost calculations. Firms with nimble commercial teams can exploit these short-term arbitrage windows to secure new customers and long-term contracts.
What the full report delivers (practical, executable content)
PW Consulting’s comprehensive report is designed to be immediately operational for strategy, commercial, and procurement teams. Highlights include:
-
Top-down and bottoms-up market sizing with historical validation and scenario-based forecasts to 2032 — enabling capital planning and revenue targets aligned to market trajectories.
-
Product and channel playbooks that translate technical ingredient trends (from commodity to specialty) into commercial tactics for pricing, bundling, and field support.
-
Regulatory impact matrix and go/no-go decision trees for product registration and market entry, reflecting shortened approval timelines for microbiome and emissions innovations.
-
Raw-material sensitivity models and procurement options analysis (hedging, vertical integration, strategic offtake), calibrated to recent grain and oilseed price paths.
-
Competitive heatmaps, capability benchmarking, and M&A candidate screens to inform inorganic growth strategies and partnership prioritization.
-
Client-ready slide decks and an executive dashboard for ongoing monitoring of price, policy, and demand indicators.
Competitive landscape — what to watch in 2026
The market displays moderate concentration: the top three players account for a little over half of global revenue, while the top five capture roughly two-thirds. This structure creates a balance — large incumbents retain scale economics and distribution reach, while mid-sized and specialty players lead on innovation and niche solutions. For 2026, the following competitive moves merit attention:
-
Scale players (global traders and processors): Firms with upstream origination and processing capabilities continue to leverage logistics and distribution networks to secure volume contracts and stabilize supply. Investments in regional production assets remain a key defensive and offensive lever.
-
Specialty ingredient and additive firms: Companies focused on enzymes, amino acids, probiotics, and mycotoxin solutions are the primary innovation engines. Their agility in registrational pathways and formulation expertise positions them to capture premium value as producers shift toward productivity-enhancing inputs.
-
Integrated animal nutrition divisions: Vertically integrated feed companies and divisions of larger agri-business players are experimenting with bundled offers (ingredients + premixes + advisory services), seeking to lock in lifetime customer value.
Notable corporate developments in the recent 12–18 months illustrate these dynamics. Strategic acquisitions in specialty additives have consolidated capabilities in gut health and mycotoxin mitigation, while partnerships and capital infusions into animal nutrition businesses reinforce the focus on scale plus innovation. Investments in regional manufacturing assets — exemplified by new, high-capacity feed plants — demonstrate that global players continue to optimize local supply footprints to serve fast-growing consumption corridors.
Operational and M&A implications for 2026
-
Prioritize capability fills over broadscale M&A: In a market where regulation accelerates category adoption, acquiring specific formulation, regulatory, or application expertise is often higher-return than chasing topline expansion via commodity bets.
-
Optimize go-to-market by livestock segment: Different livestock classes react to price and productivity levers in distinct ways. Tailored commercial models — from performance-based contracts to bundled advisory services — will prove decisive.
-
Secure supply: Use a mix of long-term contracts, strategic stocks, and selective integration to manage commodity cycles. For 2026, locking favorable offtakes in regions where fiscal changes remove import frictions presents an immediate arbitrage opportunity.
-
Pivot R&D roadmaps: Re-allocate a portion of R&D budgets toward microbiome and emissions-reducing solutions that now face shortened regulatory pathways. Fast-follower strategies can work where first-mover clinical data is scarce but registration is expedited.
Three actionable recommendations for 2026
-
Implement a short-cycle product commercialization track: Create a fast-track path that coordinates regulatory, manufacturing scale-up, and field trial teams to exploit accelerated approval windows for targeted additives.
-
Undertake a targeted supplier diversification program: Identify two to three strategic suppliers per major input category and negotiate mixed hedging/profiled contracts to reduce P&L volatility without sacrificing flexibility.
-
Build partnership and bolt-on acquisition pipelines: Focus on specialty players with differentiated science and registrational momentum; these assets are both defensive (protecting margin) and offensive (driving premium product sales).
Conclusion — how to use this intelligence in 2026
The animal feed ingredients market in 2026 is a large, steady-growth arena where marginal improvements in product performance, regulatory agility, and supply resilience compound into sizable commercial advantage. Executives who combine disciplined procurement, targeted innovation investment, and selective inorganic moves will secure outsized returns. PW Consulting’s full report provides the granular, proprietary segmentation, supplier profiles, and scenario tools necessary to operationalize the strategies summarized here — including the region- and ingredient-level detail and financial models that we intentionally reserve for the full product.
For teams preparing budgets, evaluating acquisition targets, or refreshing product roadmaps this year, the report is designed to be a decision-ready playbook: not just what’s happening, but what to do next. Visit our report page to access the complete dataset, interactive dashboards, and bespoke advisory options that will convert insight into 2026 outcomes.
For detailed analysis of this topic, please visit the official page: Animal Feed Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


