



PW Consulting: Semiconductor Chip Handler Market — USD 680M in 2025, 4.7% CAGR (2026–2032)

Semiconductor Chip Handler Market — Strategic Briefing for 2026 Decisions
Executive snapshot
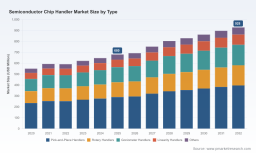
The semiconductor chip handler market is maturing into a mission-critical enabler of advanced packaging and high-throughput test flows. From a base of USD 550 Million in 2020 the market expanded to USD 680 Million by the 2025 base year and is forecast to reach approximately USD 928 Million by 2032. The medium-term trajectory implies a compound annual growth rate of 4.7% across the 2026–2032 forecast window. Market concentration is material: the top three firms capture roughly two-thirds of revenue (CR3 ≈ 65%), while the five largest firms approach three quarters (CR5 ≈ 75%).
Semiconductor Chip Handler Market
Why this matters for 2026 corporate decision-making
- Capital planning: a modest, steady expansion at ~4.7% CAGR signals predictable capacity needs rather than explosive replacement cycles—useful for capex phasing and leasing strategies.
- Supplier strategy: high concentration creates both dependency risks and supplier-bargaining asymmetries; buyers should prioritize supplier resilience and flexible contracts.
- Technology roadmap alignment: handler innovation (automation, thermal control, vision systems, AI-driven maintenance) is tightly coupled with packaging trends and test flow automation—decisions on internal development vs. third-party integration will materially affect time-to-volume for new products.
- Regulatory & geopolitical risk: export controls and incentive programs change the calculus for regional sourcing and capacity expansion—2026 is a pivot year for aligning commercial plans with policy constraints and funding opportunities.
What PW Consulting’s Semiconductor Chip Handler Study delivers (practical, decision-ready content)
This research is structured as a working toolkit for 2026 strategy execution rather than a purely descriptive market paper. Core deliverables include:
Semiconductor Chip Handler Market
- Robust market-sizing and trend narrative from 2020–2025 (historical) and a seven-year forecast (2026–2032) with scenario analysis (base, upside, downside) to stress-test capex plans.
- Buy-side decision frameworks: a supplier selection scorecard, total cost of ownership (TCO) template, and retrofit vs. greenfield decision trees for handler investments.
- Vendor diagnostics and competitive playbooks: strategic profiles, capability maps, and partner-fit matrices that translate vendor capabilities into procurement requirements by test-type and packaging architecture.
- Supply-chain mapping: critical upstream inputs, single-point-of-failure analysis, and mitigations for raw-material and labor constraints relevant to handler OEMs and subsystem suppliers.
- Operational KPIs and deployment playbooks: throughput modeling, thermal-management validation steps, and an AI-enabled predictive-maintenance pilot plan that can be executed in 90–180 days.
- M&A and partnership roadmaps: valuation heuristics, capability-acquisition checkpoints, and integration milestones for buyers seeking rapid access to advanced handler technologies or regional service networks.
- Primary intelligence: interviews with OEMs, OSATs, IDMs, and service providers; field-validated case studies showing real-world TCO outcomes and yield impacts post-handler upgrades.
Note: the full report contains gated, granular segmentation tables (by handler type, function, application, and region) and proprietary quantitative splits—these are intentionally withheld here to direct readers to the full dataset and vendor scorecards.
Semiconductor Chip Handler Market
Competitive landscape — how to read vendor behavior in 2026
The handler market is dominated by a small set of specialists and systems integrators. Understanding each player’s strategic vectors is essential when shaping supplier portfolios or evaluating partner investments.
- Advantest Corporation (Tokyo) — Strengths: high-throughput platforms and a clear focus on AI/HPC test stacks. Strategic implications: best partner for buyers prioritizing scale and front-line test automation for logic and memory at advanced nodes. Recent visibility at SEMICON events underscores continued product and ecosystem investments.
- Cohu, Inc. (San Diego) — Strengths: modular handler architectures and thermal-control subsystems. Strategic implications: candidates for integration when thermal management and flexible reconfiguration across device families are priority objectives.
- ASMPT (Singapore) — Strengths: breadth across assembly and test automation; tight fit to advanced packaging flows. Strategic implications: attractive for OSATs and IDMs seeking turnkey assembly-to-test solutions and tighter interface engineering across process stages.
- TESEC Corporation (Tokyo) — Strengths: niche capabilities in discrete, MEMS, and power IC handlers. Strategic implications: strong fit for specialized high-reliability device lines where test mechanics differ from commodity ICs.
- Boston Semi Equipment (USA) — Strengths: agile product development in pick-and-place and SLT lines; recent product-line expansions broaden the addressable final-test portfolio. Strategic implications: potential supplier for mid-volume lines and custom automation projects.
- SRM Integration (Penang) — Strengths: high-speed IC handlers and custom automation for final test. Strategic implications: regional advantage in Southeast Asia for buyers co-locating with back-end assembly clusters.
- HON. PRECISION (Taichung) — Strengths: Taiwan-based engineering depth for flash/memory and MEMS test handlers. Strategic implications: logical partner for memory-oriented test lines and nearshore support to Taiwanese fabs and OSATs.
- Pentamaster (Penang) — Strengths: integration of vision systems and pick-and-place automation for final test and power modules. Strategic implications: good fit where vision-enabled inspection and automation yield are prioritized.
- NS Technologies (Kanematsu Group, Japan) — Strengths: throughput-oriented handlers supporting logic, memory, and automotive chips. Strategic implications: a viable partner for scale-out initiatives where global service and high throughput are required.
Recent vendor moves—exhibitions, product launches, and demo roadmaps—confirm the market’s focus on AI-enabled optimization, thermal precision, and modular architectures suitable for mixed-technology lines. These tactical shifts are summarized in the full report alongside vendor scorecards and risk matrices.
Industry dynamics and risk factors shaping 2026 outcomes
- Regulatory overlays: U.S. export controls on advanced compute chips and related equipment introduce conditionality for some sales channels and OEMs. Buyers and suppliers must embed compliance checkpoints into procurement and partnership agreements.
- Policy tailwinds: CHIPS Act funding and allied programs materially influence capital availability for domestic expansion in the U.S.—this creates windows for co-investment and subsidy-aligned capacity planning in 2026.
- Raw-material dependencies: substrates and mechanical components rely on epoxy resins, metal alloys, and ceramics; volatility or quality constraints in these inputs directly affect handler lead times and retrofit feasibility.
- Labor and automation: handler adoption continues to accelerate as firms mitigate labor scarcity and raise throughput. Investments in semi- and fully-automatic handlers should be benchmarked against labor cost curves and expected yield improvements.
- Energy and operational efficiency: leading handlers are embedding AI-driven predictive maintenance and software-defined optimization to reduce energy consumption and operating expense—key for sustainability targets and OPEX reduction in 2026.
Recommended 90–180 day actions for decision-makers
- Execute a supplier resilience stress test: map single-source dependencies, validate alternate vendors, and negotiate short-term capacity options tied to clear service-level metrics.
- Initiate a pilot for AI-enabled predictive maintenance: select one high-volume line, instrument key handler assets, and run a 90–day trial to quantify downtime reduction and energy savings.
- Align CAPEX with scenario outputs: reserve growth-capex tranches tied to the forecast scenarios in this report so that expansion is triggered by measurable demand or incentive milestones.
- Embed export-control and subsidy compliance into contracts: add clauses that account for licensing regimes and CHIPS program commitments to de-risk cross-border procurement and co-investments.
- Prioritize retrofitability in specs: when issuing RFPs, score vendors not only on throughput but on modular retrofit capability, software APIs, and spare-parts logistics to reduce TCO over a 7–10 year horizon.
- Explore targeted partnerships or tuck-ins: use M&A heuristics in the full report to evaluate small-cap acquisitions that accelerate advanced-packaging handler capabilities or regional service footprints.
Conclusion — the strategic value of this intelligence
For executives drawing 2026 capital and sourcing roadmaps, the handler market offers predictable growth with concentrated supplier power and meaningful technological differentiation. The strategic choices made this year—vendor selection, automation pilots, subsidy-aligned expansions, and compliance embedding—will determine whether companies capture yield and throughput gains or suffer extended ramp cycles. PW Consulting’s full Semiconductor Chip Handler Market study transforms the macro narrative above into executable roadmaps, procurement tools, and vendor playbooks designed for immediate use by strategy, operations, and procurement teams.
Access the full report to retrieve the gated segment-level forecasts, vendor scorecards, and the operational playbooks necessary to convert insight into 2026 action.
For detailed analysis of this topic, please visit the official page: Semiconductor Chip Handler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


