



PW Consulting: Remote Control Market to Reach USD 344.8 Million by 2032 at a 4.8% CAGR

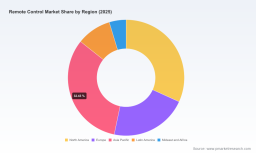
Remote Control Market — Strategic Preview for 2026: Positioning, Risks, and Opportunity Playbooks
As PW Consulting’s Senior Strategy Consultant and Chief Industry Analyst, I present this strategic preview of our new Remote Control Market research. This introduction synthesizes the report’s most consequential insights for executive decision-making in 2026, highlighting market momentum, competitive dynamics, regulatory inflection points, and the practical levers leaders should pull to convert uncertainty into advantage. The full dataset, segmented forecasts, and granular vendor benchmarking are available in the complete report; this piece deliberately omits proprietary subsegment tables to preserve the value of the primary research and to direct readers to the source for transaction-grade detail.
Remote Control Market
Market trajectory in one view
The remote control market is no longer a mature, static appliance market — it is an adjacent infrastructure that bridges consumer devices, industrial teleoperation, and connected ecosystems. Our model (base year 2025, historical window 2020–2025, forecast 2026–2032) shows steady expansion driven by converging trends in connectivity, industrial automation, and human-machine interface (HMI) innovation. The market rose from the early‑2020s baseline and reached approximately USD 215.0 Million in 2025. Under our central scenario the market expands at a compound annual growth rate of 4.8% through 2032, reaching roughly USD 344.8 Million by the end of the forecast horizon.
Remote Control Market
These headline figures reflect an evolution in demand: traditional consumer remotes remain a significant base, while higher‑value nodes such as industrial radio controls, AI‑enhanced automation interfaces, and long‑distance teleoperation platforms are increasing average selling prices and total addressable spend per deployment. For decision makers, this means the growth opportunity is less about volume alone and more about mix and monetization of advanced control capabilities.
Remote Control Market
Why this research matters for 2026 strategy
- Investment prioritization: The report translates headline growth into investment buckets (product R&D, software platforms, certification and spectrum access), enabling CFOs to size near‑term capital needs against forecasted revenue uplift.
- Commercial go‑to‑market: We map the sales motions that win — direct OEM partnerships for embedded controls, channel plays for retrofit consumer devices, and managed services models for industrial teleoperation.
- Risk calibration: Our scenario analyses quantify exposure to regulatory swings, spectrum availability, and broadband infrastructure constraints so executives can hedge technology bets and contractual commitments.
- M&A and partnership scouting: The research surfaces capability gaps and attractive target archetypes — everything from niche industrial radio specialists to software platform firms enabling voice, AI agents, and telemetry integration.
What the report delivers — practical, transaction‑grade outputs
- Integrated market model (historical performance + seven‑year forecast) with sensitivity levers for pricing, adoption rate, and technology substitution.
- Scenarios and playbooks that translate regulatory and infrastructure permutations into concrete strategic actions (e.g., defer, double down, or pivot).
- Competitive intelligence dossiers and supplier scorecards built from primary interviews, patent landscaping, and product roadmaps.
- Commercial frameworks: value propositions, channel economics, and partner fit matrices tailored to consumer, industrial, and emerging teleoperation customers.
- M&A screening toolkit that overlays strategic fit, integration complexity, and short‑term ROI to prioritize targets.
Competitive landscape: capabilities, moves, and what they imply
The market structure remains fragmented by capability and use case rather than dominated by a single business model. Measured concentration is modest (CR3 and CR5 indices indicate a market with space for scale and specialization), signaling opportunities for disciplined consolidation and vertical integration where justified.
- Universal Electronics Inc. (UEI) — UEI’s strengths are platform integration and consumer HMI: voice-enabled universals, RF capable remotes, and embedded control stacks for TVs, set‑top boxes, and smart home devices. Strategically, UEI is positioned to monetize software and cloud‑enabled features layered on top of hardware footprints. For incumbents and new entrants, UEI’s playbook underscores the commercial premium available when device control is coupled with cloud services and extended warranty or subscription revenue.
- URC (Universal Remote Control) — URC’s Total Control® and Complete Control® ecosystems and recent expansion of Automation Engine with AI Agents signal an aggressive push into software‑defined automation and intelligent HMI. Their integration of environmental sensing plugins and voice ecosystems exemplifies the trajectory from remote as a physical input to remote as an orchestration node for home and commercial environments. Partnerships and platform licensing will be the critical battleground here.
- Cattron — With a focused industrial product portfolio and recent launches (notably new radio remote packages and advanced systems for hoists and cranes), Cattron illustrates the premium of domain expertise in safety‑critical, ruggedized control. For industrial customers, reliability, certification, and lifecycle support trump unit price. Cattron’s moves suggest consolidation opportunities in the industrial segment, and highlight the ROI of investing in interoperable control protocols and service agreements.
- Liebherr — Liebherr’s LiReCon teleoperation demonstrations show the frontier potential of long‑distance, low‑latency remote control for heavy machinery. Teleoperation shifts value from single‑device control to systems engineering — integrating connectivity, edge compute, and operator interfaces. Large OEMs demonstrating teleoperation capabilities create new partnership and platform opportunities for software providers and systems integrators.
Together, these players exemplify three strategic axes: consumer HMI/platform monetization, niche industrial reliability and certification, and emergent teleoperation systems. Each axis requires different commercial, regulatory, and engineering playbooks.
Regulation, spectrum, and infrastructure: tailwinds and headwinds
Decision makers must navigate mixed signals in the policy landscape. Recent regulatory moves and court rulings create a complex backdrop: one strand of policy has reclassified broadband services in ways that reinforce open access principles, while other legal developments have shifted regulatory control toward legislative and state implementations, creating patchwork outcomes for access and pricing. Data sovereignty concerns—especially around independent satellite communications and remote region operations—add compliance burdens for cross‑border deployments.
Practically, two infrastructure realities matter for 2026 planning. First, achieving ubiquitous, low‑latency connectivity requires significant fiber and last‑mile investment; national programs and private capex will influence where high‑value teleoperation use cases are feasible. Second, spectrum policy and sharing frameworks will determine how reliably remote control applications (particularly those needing real‑time, high‑bandwidth links) can scale. Our scenarios explicitly model spectrum access constraints and the economic tradeoffs of licensed vs. shared bandwidth strategies.
Technology evolution and product strategy considerations
- Software‑led differentiation: Voice, AI agents, telemetry dashboards, and subscription services are increasingly where margin resides. Hardware remains necessary but commoditizable.
- Interoperability and standards: Vendors that invest in open APIs, common protocols, and modular hardware to enable third‑party integrations will find larger ecosystem opportunities and higher exit multiples.
- Safety, certification, and lifecycle services: Especially in industrial and teleoperation contexts, compliance and guaranteed service levels drive procurement. Product warranties, remote diagnostics, and preventative maintenance offerings become strong differentiators.
Actionable decision framework for 2026
- Map scenarios: Build three investment scenarios (Constrained Connectivity, Platform Consolidation, Teleoperation Acceleration) and stress‑test product roadmaps and cash flows against each.
- Prioritize bets: Allocate R&D across software capabilities, ruggedized industrial products, and teloperation piloting, based on margin profiles and go‑to‑market speed.
- Secure spectrum and connectivity partners: Negotiate early with carriers and satellite providers where long‑distance or low‑latency links are strategic; consider spectrum leasing and sharing strategies.
- Design flexible commercial models: Mix up‑front hardware sales with SaaS subscriptions, managed service fees, and outcome‑based contracts to align incentives with customers.
- Use M&A selectively: Acquire capabilities (software platforms, industrial radio specialists, or teleoperation system integrators) to accelerate time to market; use our M&A screening toolkit to assess integration complexity and payback.
How to use the full PW Consulting report
This preview outlines the strategic contours that matter for 2026. The full Remote Control Market report provides the transaction‑grade inputs you need to operationalize these actions: downloadable forecast models (with scenario toggles), granular regional and application splits, device‑level ASP trends, detailed vendor revenue benchmarks, primary interview excerpts, and a prioritized M&A target list. For boards, corporate strategy teams, and business unit leaders, the report turns the macro outlook and competitive analysis into executable milestones and financial commitments.
PW Consulting’s research deliberately balances openness and exclusivity: we provide the analytical scaffolding and strategic playbooks publicly, while the granular segmentation tables and vendor scorecards — the pieces your commercial and M&A teams will use in negotiations — are accessible in the full report.
For 2026, leaders who treat remote control not as a peripheral accessory but as a strategic interface — one that connects software, networks, and operational outcomes — will capture disproportionate value. This research is designed to get you from insight to action.
For detailed analysis of this topic, please visit the official page: Remote Control Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


