



PW Consulting: Extended Warranty Market to Reach USD 295M by 2032 at 9.0% CAGR

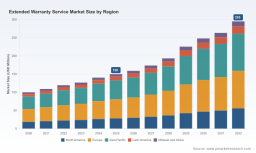
Extended Warranty Service Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a forward-looking, decision-focused preview of our Extended Warranty Service Market study. Between 2020 and 2025 the market expanded from USD 100 Million to USD 150 Million (base year 2025), driven by rising product complexity, digital distribution, and evolving consumer expectations. Our forecast (2026–2032) projects a continued compound annual growth of 9.0%, taking the market toward roughly USD 295 Million by 2032. This briefing explains why those macro dynamics matter for corporate strategy in 2026 while deliberately withholding granular subsegment tables and exact regional or application shares — a curated invitation to the full report for tactical execution details.
Extended Warranty Service Market
Why the Extended Warranty Market Demands Executive Attention in 2026
-
Structural revenue resilience: Extended warranty services are shifting from a seasonal upsell to a predictable, recurring-revenue line for manufacturers, retailers, and specialist providers. The market’s steady climb from 2020 through 2025 and the forecasted double‑digit tailwinds in several quarters signal a durable monetization path for product lifecycles that were previously revenue-neutral after sale.
Extended Warranty Service Market -
Technology-driven differentiation: Advanced vehicle electronics, connected appliances, and smart devices have increased both failure modes and service complexity. This is attracting insurers and fintech players who can underwrite, price, and manage claims using telematics, diagnostics, and predictive analytics — converting service liability into a managed profit center.
Extended Warranty Service Market -
Distribution evolution: Digital marketplaces, retailer-integrated protection plans, and OEM-embedded offerings are redistributing margin and control across the value chain. Companies that understand channel economics in 2026 will extract higher lifetime value from customers and avoid margin erosion from commoditized third-party resellers.
-
Regulatory and reimbursement pressure: Recent state-level statutes and evolving agency guidance create compliance obligations that affect product design, disclosure, and reimbursement mechanics. Prepared organizations can turn compliance into competitive advantage; unprepared ones face distribution bottlenecks and elevated dispute rates.
Market Dynamics: Drivers, Headwinds, and Strategic Implications
-
Key growth drivers: Increasing product complexity, proliferation of subscription-style ownership, extension of protection to new product categories, and consumer acceptance of paid protection are driving the market’s expansion. Our historical-to-projection trajectory highlights how these drivers compound over time.
-
Operational headwinds: Claims inflation, parts scarcity, and repair labor shortages add pressure to margins. Additionally, reimbursement frameworks and consumer protection rules are introducing greater transparency and potential cost pass-throughs for servicers.
-
Channel and product innovation: The most effective players in 2026 will combine modular coverage design, dynamic pricing linked to telematics or usage, and frictionless claims via digital-first repair ecosystems. This is not hypothetical — product roadmaps and recent launches show incumbents shifting in this direction.
-
Regulatory watchlist: New statutory requirements around plan forms and insurer involvement, coupled with federal guidance on reimbursement limits, mean companies must revalidate contractual terms and claims processes. Regulatory readiness should be a board-level priority for firms with cross-jurisdictional operations.
Competitive Landscape — Positioning and Strategic Moves
The competitive field comprises global insurers, specialist vehicle providers, retailer-aligned digital protectors, and marketplace platforms. The market remains relatively fragmented; leading firms have meaningful scale but do not dominate the market entirely, leaving room for targeted consolidation and new entrants with differentiated capabilities.
-
Assurant, Inc.: A specialist in protection services that is doubling down on integrated product bundles. Recent product launches combining vehicle protection with device repair illustrate how Assurant is packaging vertical expertise with cross-category benefits — a model that raises switching costs and improves retention.
-
Asurion: Strong in retail and carrier channels with deep repair-network capabilities. Asurion’s playbook focuses on rapid claims fulfillment and B2C distribution scale, which is essential for high-volume, low-ticket warranties.
-
Vehicle specialists (Endurance Warranty Services, CarShield, CARCHEX): These providers compete on tailored mechanical coverage, flexible underwriting, and customer financing. Their strength is brand affinity in the automotive aftercare segment and agility in pricing niche risks.
-
Global insurers (AIG, AXA, Allianz Partners, AmTrust): These incumbents leverage balance sheet scale, reinsurance access, and broad distribution to offer white-label programs to OEMs and retailers. Their advantage is capital efficiency for large warranty portfolios and regulatory know‑how for cross-border programs.
-
Digital-first players (SquareTrade under Allstate): They exemplify integration of ecommerce, streamlined claims, and retailer partnerships. Their model highlights the economics of embedding warranty at point-of-sale and servicing via standardized repair channels.
Recent developments underscore these strategic shifts. In 2025, a major consumer electronics OEM expanded its in-country protection program to include broader home appliance coverage — a move that signals OEMs are integrating extended protection into core customer propositions. Also in 2025, a leading protection specialist launched a bundled vehicle and device protection product for advanced vehicle technologies; this hybrid approach is emblematic of product convergence across categories.
What Our Full Report Delivers (Operational Value You Can Act On)
The complete PW Consulting Extended Warranty Service Market report is built for teams that need to move from insight to implementation. Highlights include:
-
Validated market sizing and scenario forecasts (base year 2025; historical window 2020–2025; forecast 2026–2032) with sensitivity tables that let you stress-test pricing, claims inflation, and channel mix assumptions.
-
Actionable go-to-market frameworks for OEMs, insurers, and retailer partners — including distribution economics, partner revenue shares, and GTM playbooks tailored to different ownership and channel models.
-
A competitive playbook covering product design, digital claims orchestration, vendor selection criteria for repair networks, and technology architecture required to scale usage-based and connected warranties.
-
M&A and partnership screeners: a prioritized list of capability adjacencies, criteria for tuck-in versus transformational deals, and financial models that quantify synergies for sample transactions.
-
Regulatory and compliance matrix: jurisdictional obligations, required contract disclosures, and practical remediation steps to align sales, legal, and claims operations with emerging standards.
-
Implementation roadmap with 90/180/360-day milestones, capability sprints (data, underwriting, claims automation), and KPI dashboards to monitor revenue per contract, retention, and claims loss ratio.
Strategic Recommendations: Priorities for 2026
-
Embed product differentiation at the point of sale. Use modular coverage constructs and optionality (e.g., higher-tier tech support, remote diagnosis) to reduce price-driven churn and raise average revenue per user.
-
Invest in claims automation and predictive maintenance. Shortened cycle times and lower service costs materially affect loss ratios; invest now to capture the compounding returns over the forecast horizon.
-
Mobilize regulatory readiness. Conduct a rapid compliance audit focused on contract forms, disclosure requirements, and reimbursement policies. Align legal, underwriting, and product teams on remediations ahead of new enforcement timelines.
-
Diversify distribution and consider white-label offerings. Retailer and OEM partnerships accelerate scale and capture customer lifecycle economics — but require tight SLAs and integrated data flows.
-
Explore targeted M&A to secure repair networks, telematics capabilities, or digital claims platforms. The market’s fragmentation creates attractive tuck-in opportunities to buy capabilities instead of building them.
Conclusion — How to Use This Preview
The Extended Warranty Service Market is moving from an accessory line item to a strategic revenue engine. By 2026, executives must decide whether to lead (invest in product, data, and distribution), follow (partner with best-in-class providers), or exit (de-risk by divesting warranty portfolios). Our research shows that early investments in digital claims, regulatory preparedness, and channel integration pay back across retention and margin metrics as the market grows at a mid‑high single-digit CAGR through 2032.
This preview intentionally omits detailed regional and application splits and other granular tables to preserve the strategic integrity of the research. For the full dataset, detailed segmentation analysis, vendor scorecards, and implementation templates — which translate these strategic implications into executable 90–360 day plans — please consult the complete PW Consulting Extended Warranty Service Market report on our website.
For detailed analysis of this topic, please visit the official page: Extended Warranty Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


