



PW Consulting: Hydrogen Market to Hit USD 228.06B by 2032 — 7.52% CAGR (2026–2032)

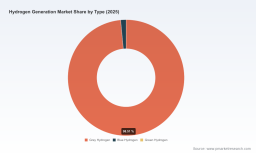
Hydrogen Generation Market — Strategic Outlook for 2026 Decision-Makers
As energy transition agendas accelerate and industrial decarbonization moves from ambition to execution, hydrogen generation has emerged as a strategic battleground for investment, technology selection and policy engagement. PW Consulting’s latest market study (base year 2025) synthesizes historical performance (2020–2025), near-term signals and a seven-year forecast (2026–2032) to equip executives with the decision-grade intelligence needed in 2026. The global hydrogen generation market expands from roughly USD 89 billion in 2020 to USD 137.8 billion in 2025, with our forecast pathway reaching about USD 228.1 billion by 2032 at a compound annual growth rate of 7.52% (2026–2032). This analysis explains why those headline numbers matter for capital allocation, technology sourcing, and policy-driven project economics — while preserving the detailed segmentation and project-level data in the full report to protect client value and encourage direct engagement.
Hydrogen Generation Market
Why 2026 Decisions Will Define Competitive Positioning
Three dynamics converge in 2026 to create a narrow window for decisive action. First, policy clarity in critical markets has materially shortened the timeline for projects to qualify for incentives and tax credits — a condition that alters returns on investment and the attractiveness of different production routes. Second, cost declines in electrolyzer equipment and modular manufacturing are beginning to translate into real options for end-users and utilities choosing between on-site versus merchant supply models. Third, incumbent industrial players and specialized electrolyzer manufacturers are simultaneously scaling, creating both partnership opportunities and competitive threats.
Hydrogen Generation Market
- Policy timing: Recent rulemaking and legislative timelines (notably U.S. 45V Clean Hydrogen Production Tax Credit clarifications and accelerated eligibility milestones) make project start dates and construction milestones strategic variables for 2026 planners.
- Technology economics: Public domain estimates and industry scenarios point to converging cost trajectories for electrolyzer capital expenditure and operating assumptions; these inform breakeven analyses against legacy steam-methane pathways.
- Market structure: Market concentration is moderate: the top three suppliers account for a meaningful but non-dominant share of the market, while the top five widen competitive leverage — an environment suitable for both scale plays and niche specialization.
Market Trajectory at a Glance
Understanding the total market evolution is the starting point for strategy. The hydrogen generation market demonstrated steady growth through 2020–2025 and enters a phase of accelerated investment in the late 2020s. Our forecast shows the market expanding from USD 137.8 billion in 2025 to approximately USD 228.1 billion by 2032, reflecting a 7.52% CAGR over the 2026–2032 forecast window. These aggregate figures capture simultaneous expansion of traditional production routes, merchant supply infrastructure, and a fast-growing pipeline of electrolysis-based projects — driven by industrial demand for low-carbon feedstock, emerging mobility use cases, and power/energy storage experiments.
Hydrogen Generation Market
For corporate strategists, the macro numbers imply two practical conclusions: capital deployment should be phased to capture technology cost declines while preserving optionality for off-ramps enabled by merchant market development; and commercial teams must prioritize offtake and storage strategies that convert capacity into contracted revenue streams during early-market uncertainty.
Key Value Drivers and Material Risks
- Policy and incentives: Tax credits that tier by lifecycle emissions and deadlines for commencement of construction materially influence project IRR and choice of carbon mitigation pathways. Executives should explicitly model incentive sensitivity in 2026 to determine project timing.
- Electrolyzer capital cost trajectory: Independent forecasts project a wide span of electrolyzer capex under high-deployment scenarios. This range is a primary determinant of green-hydrogen competitiveness by the end of this decade; strategic procurement and supplier partnerships can capture manufacturer learning curves.
- Operating costs and LCOH drivers: Recent public estimates for fixed operating costs (for example, PEM electrolyzer operating assumptions) provide a defensible starting point for operational budgeting. Electricity sourcing and utilization profiles remain the single largest determinant of delivered cost for electrolytic hydrogen.
- Feedstock and integration risk: For fossil-based routes, natural gas feedstock price variability and decarbonization commitments require parallel capex for CCS/backstop technologies, altering long-term economics versus electrolytic pathways.
- Infrastructure and storage: Emerging projects (including large-scale electrolysis installations and salt-cavern storage pilots) underscore the need for integrated supply-chain planning across production, liquefaction, storage and transportation.
Competitive Landscape — Who Matters and Why
Our assessment reviews technology vendors, industrial gas majors, and integrated systems providers. The market is populated by specialty electrolyzer manufacturers, legacy industrial-gas companies, and diversified equipment suppliers — each with distinct strategic advantages and limitations.
- Electrolyzer specialists: Companies focused on PEM, alkaline and novel AEM stacks have moved from demonstration to commercial scale. These firms are competing on stack performance, modularity, and manufacturing scale. Strategic partnerships and long-term procurement agreements will be decisive for project developers seeking deployment certainty.
- Integrated suppliers: Industrial gas majors and diversified energy companies bring breadth across production, distribution and merchant markets. Their competitive edge is an integrated value chain and established customer base in industrial offtake sectors.
- Project developers & system integrators: A third cohort combines electrolysis supply with project development capabilities, enabling turnkey solutions and accelerating time-to-market for corporate offtakers and utilities.
Notable market movements through 2024–2025 illustrate these dynamics: commissioning of utility-scale electrolysis capacity in China and demonstration green-ammonia facilities in Europe signal a maturing project pipeline; salt-cavern and liquefaction pilots in North America showcase storage and distribution innovation. For 2026 strategy, watch three company archetypes — pure-play electrolyzer firms scaling manufacturing, industrial gas incumbents extending into green-product markets, and integrators bundling offtake, storage and logistics into turnkey offers.
Recent Industry Signals That Matter in 2026
- Large-scale electrolysis projects and green-ammonia demonstrations indicate the practical operability of high-capacity renewable-electrolysis supply chains.
- Commercial-scale storage and liquefaction pilots validate merchant and long-haul distribution options that can unlock new regional arbitrage opportunities.
- Regulatory clarifications and tax-credit timelines have compressed the calendar for projects seeking incentives, requiring earlier commitment to construction starts for qualification.
What the PW Consulting Study Delivers — Practical Tools, Not Just Charts
Beyond market totals and high-level narratives, the report is designed as a playbook for corporate action. Core deliverables include:
- Scenario-based financial models that project levelized cost of hydrogen under multiple electricity, capex and incentive pathways — model templates are provided so teams can plug in corporate assumptions.
- Technology roadmap with TRL-adjusted timelines and procurement guidance for PEM, alkaline, AEM and legacy reforming routes — focused on commercial readiness and supply-chain risk mitigation.
- Competitive supplier profiles and an actionable short-listing methodology to assess partner fit by scale, geography and delivery capability.
- Policy impact matrix that quantifies the sensitivity of project IRR to prevailing incentive structures, permitting timelines and emissions thresholds — including step-change scenarios driven by tax-credit tiering.
- Go-to-market playbooks for offtake models (merchant, captive, and hybrid), with sample term-sheet language and contractual levers to allocate long-term price and volume risk between producers and buyers.
- Implementation roadmap and checklists for site selection, grid connection, permitting, and community/stakeholder engagement to accelerate “shovel-ready” conversion.
To preserve the strategic value of the report, granular dataset exports and element-level segmentation (by region, technology, application and hydrogen color classifications) are retained exclusively in the full publication and data pack. Those datasets power detailed project-level assessments, procurement auctions and regulatory-compliance scenarios — and are intentionally not reproduced in public summaries.
How Executives Should Use this Intelligence in 2026 — Five Practical Moves
- Lock in optionality: Use staged contracts and conditional EPC milestones that preserve access to tax credits and incentive windows while limiting stranded-capacity risk.
- Secure offtake alignment: Prioritize offtake agreements with flexible volumes and indexing that reflect evolving electrolyzer utilization and merchant market development.
- Negotiate supplier roadmaps: Embed manufacturer performance milestones and price-collar provisions into long-lead equipment contracts to capture technology learning curves.
- Stress-test scenarios: Run downside cases that combine slower-than-expected electrolyzer cost declines with delayed permitting and tighter incentive eligibility to calibrate capital buffers.
- Engage policy levers: Proactively align project timelines and GHG-lifecycle reporting to maximize eligibility for tiered incentives and to shape local permitting outcomes.
Conclusion — Where This Study Adds Value in 2026
PW Consulting’s Hydrogen Generation Market study translates a complex confluence of policy, technology and market dynamics into operational guidance for decision-makers. By combining a transparent market forecast (2020–2025 history, 2026–2032 forward view with a 7.52% CAGR) with scenario-ready financial models, supplier analysis, and policy-impact tools, the study equips C-suite and investment teams to make evidence-based commitment decisions in 2026. The report purposely reserves detailed segmentation and project-level datasets for the full publication — because those are the inputs that convert strategic intent into executable programs.
For access to the complete dataset, interactive models and the supplier short lists referenced here, please consult the PW Consulting publication page and data portal — where the full intelligence package, including exportable spreadsheets and playbooks, is available for corporate subscribers and project partners.
For detailed analysis of this topic, please visit the official page: Hydrogen Generation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


