



PW Consulting: MBE Market to Reach USD 131M by 2032 at 4.9% CAGR

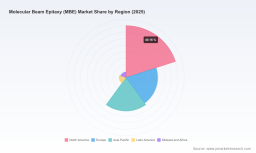
Molecular Beam Epitaxy (MBE) Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
The Molecular Beam Epitaxy (MBE) market is at an inflection point. After steady recovery and consolidation through the early 2020s, the market reached a material scale by the 2025 base year and is projected to grow at a mid-single-digit compound annual growth rate (CAGR) through the early 2030s. This report frames that growth pathway, the structural drivers behind it, and the practical options executives must weigh in 2026 to convert structural trends into competitive advantage.
Molecular Beam Epitaxy (MBE) Market
Why this matters for 2026 strategy
- MBE remains the enabling deposition technology for advanced III‑V semiconductors, optoelectronics, and emerging quantum devices — areas where product roadmaps are advancing from laboratory demonstration to pilot and production scale.
- The market’s projected steady expansion underscores opportunity, but timing and go‑to‑market choices will determine whether firms capture high-margin system sales, recurring services, or downstream device revenue.
- Procurement and policy shifts in key markets are changing how large research and production customers source capital equipment; these shifts alter contract sizes, channel tactics, and service models that vendors must adopt in 2026 and beyond.
Market trajectory and sizing (high level)
Using 2025 as the base year, the MBE market exhibits a predictable, technology‑led growth profile. The market’s baseline scale provides a focused addressable opportunity for suppliers, while the projected mid‑single‑digit CAGR through the forecast period reflects the compound effect of incremental volume growth in production applications, sustained R&D demand, and selective replacement cycles for high‑value systems. For leaders, the strategic implication is clear: growth is real and durable, but concentrated in technologically advanced niches where suppliers that pair equipment innovation with applied services will capture the lion’s share of profitable expansion.
Molecular Beam Epitaxy (MBE) Market
Key demand drivers
- Quantum device commercialization: As quantum photonics and single‑photon emitter programs move from faculty labs into scale pilots, demand for precision MBE platforms optimized for nanostructure repeatability has risen. Research deployments in 2024–2025 underscore the migration from exploratory research to applied device engineering.
- Compound semiconductor and infrared technologies: Advanced detectors and optoelectronic devices—particularly those relying on III‑V materials—continue to anchor MBE demand because of the technique’s atomic‑level control over layer composition and interfaces.
- Dual‑track market dynamics: R&D activity remains a durable revenue base, but production use cases are expanding. The most successful suppliers will demonstrate pathways for customers to transition processes from research platforms to production‑grade systems without compromising yields or wafer throughput.
Supply chain, raw‑material and regulatory considerations
MBE systems are sensitive to components and precursor supply chains. Gallium‑based substrates and arsenide precursors continue to be strategic inputs; their availability and cost volatility materially affect total cost of ownership for users. Separately, procurement policy changes in major buyer jurisdictions are reshaping contract negotiation dynamics—raising thresholds for formal cost disclosures and altering how larger system deals are structured. Vendors should explicitly model these procurement shifts when sizing deals and designing sales incentives in 2026.
Molecular Beam Epitaxy (MBE) Market
Competitive landscape — who matters and why
The MBE supplier ecosystem is a mix of global platform vendors and specialized component or systems houses. Market concentration metrics indicate a market where a small number of tier‑one suppliers capture a sizeable share of the higher end, but a diverse set of regional and niche vendors compete on customization, service and price. For strategic planning, this means incumbents must defend installed base advantages while challengers can win by tightly coupling equipment with application‑specific services.
- Riber S.A. — A European platform vendor with a deep installed base and production‑oriented systems. Recent multi‑system orders and a broad installed fleet emphasize Riber’s strength in production and service continuity. For partners and competitors, Riber’s model underscores the value of combining robust hardware with lifecycle services to lock in production customers.
- Veeco Instruments Inc. — A technology leader with modular R&D and production platforms that has maintained strong engagement with university and research centers. Recent deployments for compound semiconductor and quantum programs illustrate Veeco’s success in securing early‑stage R&D relationships that can translate into production wins over time.
- DCA Instruments, SVT Associates, Dr. Eberl, Eiko Engineering, Omicron Electronics, SKY Technology — These vendors represent the spectrum of specialization: III‑V epitaxy platforms, component suppliers, UHV and tooling specialists, and regional manufacturers. Their strategies vary from focused product differentiation to regionally tuned go‑to‑market models, enabling them to capture niche demand and retrofit opportunities in installed fleets.
Recent market signals to watch
- Academic and spin‑out wins are accelerating: Notable university purchases and commercial deployments in 2024–2025 show that applied research funding is translating into upgraded equipment investments.
- Large production orders remain selectively awarded: There are confirmed instances of multi‑system orders for production platforms—an indicator that certain end markets are moving from pilot to scaled manufacturing.
- Procurement thresholds and contract structures are changing: Updated acquisition rules in some jurisdictions have reduced administrative burdens for mid‑sized procurements, shifting where opportunities lie for both domestic and international vendors.
What the PW Consulting MBE report provides (practical contents)
The full study integrates proprietary demand modeling, supplier inventories, scenario analysis and an action‑oriented playbook for 2026 decision‑makers. Notable deliverables include:
- Top‑down market sizing and a bottom‑up demand model that reconciles installed base dynamics with new system deployments across R&D and production use cases.
- Segment‑level forecasts and sensitivity scenarios (technology shock, raw‑material stress, rapid commercialization) that translate into revenue and margin implications for suppliers and OEMs.
- Supply‑chain mapping and vendor risk scoring, with mitigation actions for critical inputs and long‑lead items.
- Detailed competitive profiles and capability matrices covering system architectures, platform modularity, service offerings and installed‑base monetization strategies.
- An M&A and partnership playbook: valuation heuristics, integration risks, and target archetypes for buyers seeking technology or regional expansion.
- Commercial playbooks for vendors and buyers: pricing frameworks, contract structuring templates that reflect evolving procurement rules, and aftermarket/service revenue accelerators.
Strategic implications and recommended actions for 2026
Executives facing 2026 choices should prioritize clarity on two dimensions: where their core advantage lies (equipment innovation vs. services vs. integration) and how they will manage the transition of customers from R&D to production. The following high‑level recommendations provide a starting point:
- Prioritize platform modularity. Build or acquire modular subsystems that reduce conversion costs when customers scale from research to production; this reduces buyer switching costs and strengthens lifetime revenue.
- Design procurement‑aware commercial models. Given changing procurement thresholds and contract behaviors, create flexible contracting options (lease + service, staged purchases, performance guarantees) tailored to research institutions and production fabs.
- De‑risk critical material supply. Implement diversified sourcing and hedging strategies for gallium and other strategic precursors; where feasible, verticalize or secure long‑term supply agreements to protect uptime for production customers.
- Monetize installed base. Invest in remote diagnostics, upgrade modules and certified refurbishment programs to generate recurring revenue and deepen customer relationships.
- Targeted M&A and partnerships. For suppliers seeking scale, prioritize bolt‑on acquisitions that extend service footprints or add complementary component expertise rather than horizontal hardware duplication.
- Invest in applied R&D partnerships. Secure early access to device roadmaps by partnering with academic centers and corporate research labs; these relationships often convert into multi‑year system and service contracts.
Risks and watchlist for the next 18 months
- Raw‑material shocks that increase operating costs and slow customer purchase cycles.
- Geopolitical and trade policy shifts that alter where customers prefer to source capital equipment.
- Rapid technological substitution in niche applications—if alternative deposition or integration approaches gain parity, the addressable market for certain MBE applications could narrow.
Conclusion — how to use this intelligence in 2026
For leaders making 2026 investment and go‑to‑market decisions, the choice is not whether the MBE market grows—the data indicate a steady, commercially meaningful expansion—but how to position to capture the most valuable portions of that growth. Whether the objective is to win production contracts, expand regional presence, or transition from equipment to lifecycle service models, the playbook must combine technical differentiation with contractual flexibility and supply‑chain resilience. Our full report provides the granular segmentation, company benchmarking and scenario dashboards necessary to convert these strategic priorities into executable 12‑ and 36‑month plans.
Next step
PW Consulting’s full MBE market study contains the detailed datasets, interactive forecasts and vendor scorecards that operational teams require to execute on the recommendations above. Access to the full model and custom briefings will enable tailored scenario runs for procurement, product and M&A teams — contact our research desk to request the complete report and a guided walkthrough of the decision tools referenced here.
For detailed analysis of this topic, please visit the official page: Molecular Beam Epitaxy (MBE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


