



PW Consulting: Ship-to-Shore (STS) Container Cranes Market USD 3,000M in 2025; 5.2% CAGR (2026–32)

Ship-to-Shore (STS) Container Cranes Market: Strategic Outlook for 2026 Decision-Making
Executive preview
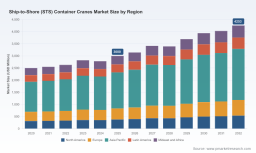
The global Ship-to-Shore (STS) container cranes market has demonstrated steady expansion through the early 2020s and enters 2026 from a position of structural growth and renewed capital intensity. In our base-year assessment (2025) the market reached approximately USD 3,000 Million (revenue, Million USD), up from roughly USD 2,500 Million in 2020. Our model projects a compound annual growth rate (CAGR) of about 5.2% across the 2026–2032 forecast window, driving the market toward an anticipated USD 4,253 Million by 2032 under the baseline scenario.
Ship-to-Shore (STS) Container Cranes Market
This briefing is intended as a strategic “preview”: it captures the data-driven trends, competitive dynamics, and procurement levers that will matter for boardroom decisions in 2026, while intentionally withholding the granular regional and application split tables reserved for the full PW Consulting report and interactive datasheet.
Ship-to-Shore (STS) Container Cranes Market
Why this matters for 2026 purchasers and investors
- Capital allocation and timing: Port terminals, marine investors and OEMs must align crane procurement and retrofit cycles with longer lead-times and rising capital costs. The combination of steady underlying demand and protracted delivery schedules creates windows where early commitment improves access and price certainty.
- Contract design and risk transfer: With stretch in delivery timelines and tariff volatility, contract terms that clearly allocate escalation, delay penalty and scope-change risk are now differentiators in tender outcomes.
- Service and lifetime value: As fleets grow and vessel dimensions increase, lifecycle costs — not only purchase price — determine terminal productivity. Maintenance contracts, digital diagnostics, and spare-parts logistics are elevated priorities.
Key market dynamics shaping 2026 strategies
Three macro dynamics dominate the STS market heading into 2026:
Ship-to-Shore (STS) Container Cranes Market
- Vessel upscaling and operational productivity — The push toward larger vessels and denser yard operations continues to favor higher-capacity cranes, dual-trolley concepts and feature-rich control systems that compress vessel turnaround.
- Supply-chain and manufacturing pressure — Producers and buyers alike grapple with longer manufacturing cycles. Average global delivery schedules extended materially between 2022 and 2024, driven by steel-price and PLC-cost inflation as well as capacity constraints in fabrication and electrical subsystems.
- Regulatory and trade friction — Trade measures and tariff actions introduced noise into sourcing strategies, increasing the premium on diversified procurement footprints and local-assembly options.
Operational evidence underlines these dynamics. Industry surveys reported continued deliveries in the low hundreds of STS units globally in recent years, and trends in lift-class selection and boom outreach reflect how terminal planners are trading capacity for reach. These market signals translate directly into vendor selection criteria: uptime guarantees, anti-sway and automation features, electric-drive options and modularity now outrank simple upfront price in many tenders.
Price and delivery realities: what procurement teams must know
Purchase price ranges remain wide, reflecting model complexity and optionality. STS crane prices typically span from lower-cost Panamax-class units to premium super post-Panamax builds — the variability largely reflects lift capacity, outreach, electrification and automation packages. Importantly, manufacturing lead-times lengthened in the mid-2020s: our analysis cites an extension from roughly 11 months to 15 months on average during 2022–2024, a function of a near-term spike in steel and PLC costs and constrained workshop capacity.
Trade policy can materially change landed cost. Recent Section 301 measures and related import tariffs on certain origins have added a non-trivial incremental cost to some major U.S. terminal projects, forcing re-evaluation of sourcing, value-engineering and potential capital reallocation.
Competitive landscape — who matters and why
The STS market demonstrates concentrated leadership by established OEMs with deep installed bases and broad global service networks. Market concentration metrics indicate that the industry’s top three vendors control a majority share of new-build activity, with the top five extending that dominance further. For procurement teams, this creates a specific dynamic: while a shortlist of incumbents offers scale and predictable delivery, emerging and regional suppliers compete aggressively on price, customization and local support.
- Konecranes (Helsinki, Finland) — Focused on high-reliability STS designs; differentiators include proprietary electric motors, gearing and control systems and a large installed base supporting fast ship turnaround. ( https://www.konecranes.com)
- Liebherr (Bulle, Switzerland) — Premium STS cranes with advanced anti-sway, fully electric variants and dual-trolley options; long-standing manufacturing footprint and recent high-profile deliveries to major European terminals. ( https://www.liebherr.com)
- ZPMC (Shanghai, China) — Global reach with flagship STS deployments across six continents; recognized domestically for manufacturing excellence and sizeable production capacity. ( https://www.zpmc.com)
- SANY Group (Changsha, China) — Competitive pricing and strong Asia-Pacific relationships with increasing emphasis on customization and local support. ( https://www.sanyglobal.com)
- Paceco Corp. (Cypress, California, USA) — Focus on large PORTAINER® STS gantry cranes, emphasizing trolley speed and bespoke designs for North American and select global terminals. ( https://pacecocorp.com)
- Hyundai Samho (South Korea) — Integrated heavy-industry portfolio with STS offerings tied into broader port-equipment supply chains. ( https://www.hyundai-heavy.com)
- Mitsui Engineering & Shipbuilding / PACECO (Tokyo, Japan) — Known for robust PORTAINER® designs with a focus on productivity and lifecycle reliability. ( https://www.mes.co.jp)
- Henan Weihua (Henan Province, China) — Experienced regional manufacturer with multi-decade design and production capability for STS units. ( https://www.henanweihua.com)
- Anupam Industries (India) — Targeting global terminals with competitive, regionally tailored STS solutions. ( https://www.anupamindustries.com)
Recent deal-flow and deliveries illustrate competitive positioning: premium OEMs secured new supply contracts and key deliveries in late 2025 for strategic terminals; flagship projects in emerging markets continue to attract Chinese and regional suppliers. Industry associations’ surveys in 2024 captured unit deliveries and shifting lift-class preferences, reinforcing that the product mix is moving toward higher-capacity, longer-reach equipment.
Practical report takeaways — what PW Consulting delivers
For executives preparing 2026 procurement cycles, the full PW Consulting Ship-to-Shore market study provides five practical outputs designed to inform decisions and accelerate execution:
- Forward-looking demand model: Scenario-based forecasting (2026–2032) with sensitivity to vessel-size trajectories, terminal throughput growth and capex pacing. The model is delivered in an interactive spreadsheet so teams can stress-test assumptions.
- Supplier scorecards and procurement playbooks: Comparative supplier assessment across technical capability, on-time delivery history, service network quality and total cost of ownership (TCO) implications; negotiation templates and contract clauses tailored to mitigate lead-time and tariff risk.
- Unit economics and TCO frameworks: End-to-end cost modelling that captures purchase price, import duty exposures, spare-parts logistics, energy consumption (electric vs diesel/electric hybrid options) and typical maintenance profiles.
- Supply-chain and risk maps: Factory-capacity overlays, single-point-of-failure analysis for critical subsystems, and contingency playbooks for accelerated delivery or local-assembly strategies.
- M&A and Capex screening tools: Valuation benchmarks, integration-risk flags and a shortlist of strategic targets where vertical integration or aftermarket capability could change competitive dynamics.
Note: this preview intentionally omits the full segmentation tables and unit-level pricing ladders (regional splits, application-by-type breakdowns and supplier-by-model price matrices), which are accessible in the full report and accompanying data workbook.
How to apply these insights in 2026 — a short action checklist
- Align procurement windows with current average lead-times; place orders with realistic acceptance dates and incentivize early delivery where needed.
- Build tariff and escalation clauses into contracts; evaluate local assembly or phased delivery if duties materially increase landed cost.
- Prioritize lifecycle uptime through longer service agreements and digital-monitoring add-ons; quantify TCO rather than chasing headline discounts.
- Maintain multi-supplier shot lists for major tenders; use PW Consulting’s supplier scorecards to validate technical claims against historical delivery performance.
- Stress-test capex scenarios against vessel size evolution and terminal throughput; stagger investments to retain flexibility for retrofits and automation upgrades.
Next steps and where to get the full intelligence
This executive preview synthesizes the strategic and operational signals that will shape STS procurement and investment decisions in 2026. The full PW Consulting Ship-to-Shore (STS) Container Cranes Market report includes the complete regional and application segmentation, model assumptions, unit-price ladders, supplier scorecards and an interactive forecast workbook designed for CFOs, procurement leads and terminal operators. To access the comprehensive analysis, data tables and proprietary scenario tools, please follow the link on our report page or contact a PW Consulting advisor for a guided walk-through of the dataset and model outputs.
For detailed analysis of this topic, please visit the official page: Ship-to-Shore (STS) Container Cranes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


