



PW Consulting: Military Communications to hit USD 56,800M by 2032 (6.8% CAGR)

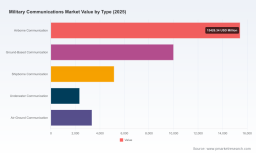
Military Communications Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest Military Communications Market study (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) offers an actionable synthesis designed to guide executive decisions in 2026. Anchored in robust bottom‑up modeling, the study traces the market through a period of structural transition and projects continued expansion at a compound annual growth rate (CAGR) of 6.8%. In aggregate terms the market sits comfortably in the multi‑tens of billions (USD, revenue unit: Million) in 2025 and — based on scenario-validated drivers — is forecast to grow materially by 2032. This briefing explains why that trajectory matters, what levers will shape supplier and buyer outcomes over the next 18 months, and how to extract operational advantage from the full report.
Military Communications Market
Why this study matters now
2026 is a decision‑heavy year for stakeholders across defense primes, tiered suppliers, satellite operators, and government procurement offices. Investment cycles are accelerating around three intersecting inflections: the shift toward proliferated and protected small‑satellite architectures; the industry adoption of high‑throughput optical interconnections and anti‑jam technologies; and the tightening nexus between spectrum policy and procurement funding. Our research quantifies the economic implications of these inflections (base year metrics, historical growth patterns, and forecast trajectories are embedded in the report’s models) and translates them into near‑term commercial and programmatic actions.
Military Communications Market
- Macro posture: The market’s mid‑single digit CAGR signals steady demand and encourages capacity investments, but it also requires disciplined portfolio prioritization to avoid misallocated capital.
- Competitive structure: Concentration metrics show the top three firms control a significant portion of market revenue while the top five expand that share further, creating a market where scale matters but niches remain accessible to specialized innovators.
- Program timing: Multiple government programs and IDIQ frameworks initiated in 2024–2026 create procurement windows that favor early movers with validated demonstration assets and partner ecosystems.
Core market dynamics and technology inflection points
Our analysis synthesizes procurement announcements, corporate moves, and regulatory shifts to explain demand and supply evolution.
Military Communications Market
- Proliferation of protected small‑satellite constellations: Program awards and IDIQ pools created in 2025–2026 reinforce a system architecture that prizes distributed resilience and anti‑jamming capabilities. This drives demand across satellite manufacturing, hosted payload services, ground segment anti‑spoofing, and RF hardening.
- Optical and hybrid networking: Progress on optical inter‑satellite links and the acquisition of key optical terminal vendors by launch and integrator players is creating a value chain where photonics expertise materially changes cost and performance equations for long‑haul military comms.
- Hybridization of commercial and dedicated military networks: Operators are increasingly pitching hybrid service models combining commercial constellations with DoD overlays. This trend alters contracting approaches and supports alternative revenue models for satellite operators and service integrators.
- Spectrum policy as a strategic variable: Recent congressional and federal actions are reshaping the spectrum pipeline and reimbursement mechanics; procurement teams must now reconcile auction dynamics, relocation cost recovery frameworks, and the absence of fully documented interagency spectrum‑sharing plans in their risk models.
Competitive landscape — what matters to bidders and partners
Our competitive analysis focuses on a curated set of companies that illustrate three strategic archetypes: prime system integrators, vertically integrated satellite and terminal developers, and specialized subsystem providers. Each archetype faces distinct opportunity and risk profiles.
- Prime integrators (examples reviewed): Firms with legacy systems engineering depth and prime contract experience retain advantage in large‑scale modernization programs. Their ability to package end‑to‑end solutions and to hold critical path responsibility for national continuity and NC3 modernization is a differentiator.
- Platform and operator entrants: Companies building or operating small satellites and hybrid service layers are disrupting traditional supplier relationships. Their advantage lies in rapid iteration, lower per‑unit capital intensity, and service‑level flexibility attractive to both program offices and allied partners.
- Specialist technology providers: Optical terminal vendors, anti‑jam modem manufacturers, and tactical comms hardware suppliers are the innovation engines. Consolidation moves and targeted acquisitions have expanded their industrial reach, enabling them to supply both government programs and new commercial backbones.
Strategically, winners will be those who master systems integration across radiofrequency, photonics, and software layers while navigating multi‑award IDIQs, teaming arrangements, and export/compliance constraints.
What the report contains — practical deliverables
The full study is structured to be immediately operational for commercial strategy teams, M&A investors, and procurement leads. Highlights include:
- Top‑line market sizing and a transparent, reproduceable model (base year 2025; historical window 2020–2025; forecast 2026–2032) with downloadable datasets in USD (Million).
- Scenario‑based forecasts under alternative policy and budget pathways, enabling rapid sensitivity testing of program win rates, pricing pressure, and technology adoption curves.
- Vendor profiles and capability maps that go beyond public press releases to assess program relevance, integration risk, and partnership fit—without exposing confidential commercial splits in the preview.
- Procurement playbooks that translate program timelines and contract vehicle structures into bidding and teaming recommendations, including go‑to‑market approaches for IDIQ pools and prototype opportunities.
- An operator and supplier heatmap that flags where price competition, technical differentiation, or regulatory constraints are likely to compress margins.
- Investment and M&A scoring frameworks with target shortlists and integration red‑flags tailored for investors seeking to enter or expand in military communications supply chains.
- Regulatory and spectrum risk modules that incorporate recent legislative changes, auction mechanics, and reimbursement frameworks—critical for financial planning and program cost‑of‑ownership estimates.
Policy and regulatory context — the unseen constraint
Policy developments in 2024–2026 have elevated spectrum strategy from a technical consideration to a core budgetary and programmatic risk. Recent legislation established a spectrum pipeline and identified bands for reallocation and study. At the same time, federal guidance on spectrum‑sharing mechanisms remains incomplete, and government actors have signaled that auction proceeds must cover federal relocation and sharing costs with defined reimbursement rules. For program planners, this creates two imperatives: model the cost of spectrum transitions conservatively, and engage early with spectrum policy teams to avoid schedule and funding surprises.
Strategic recommendations for 2026
- Prioritize modular, demonstrable capability: Win probability in multi‑award procurements favors teams that can present a demonstrator or flight‑proven subsystem tied to a clear path to scale.
- Build hybrid revenue pathways: Combine service contracts with hardware sales and managed service elements to stabilize cash flow against procurement timing variability.
- Invest in optical and anti‑spoofing competencies: These technologies are gatekeepers to next‑generation architectures and command premium margin in integration phases.
- Calibrate partnership strategies to concentration realities: The market is dominated by a few large primes, but targeted partnerships with incumbents or co‑development with specialist vendors yields differentiated access to program pipelines.
- Embed policy scenario planning: Invest in a small, focused capability to track spectrum policy, auction cues, and reimbursement rules—this reduces bid‑to‑contract timeline risk and protects program margins.
Risk profile — what could derail plans
- Policy uncertainty: Incomplete interagency guidance on spectrum sharing and pipeline timing can create program slips or unanticipated relocation costs.
- Supply chain constraints: Optical terminal production, specialized RF components, and certain semiconductor lines remain chokepoints that can inflate lead times.
- Budget volatility: Shifts in defense appropriation priorities or reallocation to other domains could compress award opportunities in the short term.
- Competitive consolidation: M&A activity among specialist vendors can rapidly change competitive dynamics and create new integration dependencies.
How to use this briefing and next steps
This article is a strategic preview intended to surface the directional forces and practical recommendations that will shape successful plays in 2026. It intentionally omits granular regional and application revenue splits to preserve the commercial incentive for the full dataset. PW Consulting’s full Military Communications Market report contains the detailed segmentation, downloadable financial models in USD (Million), supplier scorecards, and scenario workbooks that allow you to:
- Quantify addressable market share by program and geographies for inclusion in investment memos;
- Create evidence‑based win strategies with sensitivity testing for pricing and program delays;
- Identify mid‑market acquisition targets and model accretive integration paths;
- Build procurement timetables tied to policy milestones and auction outcomes.
For executives mapping 2026 resource allocation, this study provides both the high‑level market architecture and the operational playbooks to convert forecasts into funded programs. To access the complete dataset, segmented forecasts, and supplier playbooks, please refer to the full PW Consulting Military Communications Market report available through our publications portal.
For detailed analysis of this topic, please visit the official page: Military Communications Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


