



PW Consulting: Wood Chippers Market to grow at 6.1% CAGR through 2032

Wood Chippers Market 2026 — Strategic Preview for Executive Decision-Makers
Executive summary
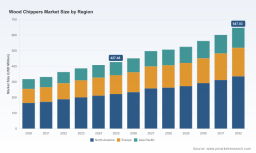
As a capital- and regulation-intensive segment of the broader forestry and biomass equipment market, wood chippers present a distinctive blend of mature demand and tactical disruption. Our 2025-base study shows the global wood chippers market expanded from roughly USD 318 million in 2020 to USD 427.5 million in 2025, and is projected to grow at a compound annual growth rate (CAGR) of 6.1% across the 2026–2032 forecast window — reaching an estimated USD 647 million by 2032. For corporate strategists planning capacity, product portfolios, M&A, or go-to-market strategies in 2026, these metrics are the macro scaffold on which more granular choices must be built.
Wood Chippers Market
Why this research matters for 2026 decisions
- Timing matters: 2026 is a hinge year. Regulatory headwinds (Tier 4 Final / EU Stage V) have been internalized by many OEMs and late adopters now face a steeper cost curve for compliant diesel units. Our report quantifies the cost and maintenance implications across machine classes and maps adoption pathways for low-emission alternatives.
- Capital allocation clarity: With mid-term growth at ~6.1% CAGR, executives must reconcile steady market expansion with pockets of disruption (electrification, digital services). The study provides ROI scenarios that help prioritize R&D vs. aftermarket investments.
- Risk-adjusted roadmap: Supply-chain pressure points — from knife and anvil wear rates to after-treatment component scarcity — materially affect TCO. We translate these operational risks into financial sensitivities and procurement safeguards ready for 2026 contracting cycles.
Market trajectory and structural dynamics
The market’s recent compound expansion is driven by converging forces: continued demand from land-clearing, biomass and pulp & paper segments; replacement cycles in municipal and arborist fleets; and technology-driven differentiation among OEMs. However, the headline growth number masks uneven economics across product tiers — low-cost entry machines demonstrate materially higher maintenance intensity and slower throughput, while premium industrial systems trade on uptime, modularity and serviceability.
Wood Chippers Market
Critical structural dynamics that will shape strategic options in 2026 include:
Wood Chippers Market
- Regulation-driven cost inflation: Emission after-treatment (diesel particulate filters, SCR systems) has increased upfront costs and ongoing maintenance for diesel platforms. Compliance timelines and retrofit economics are modeled in the report.
- TCO and maintenance economics: Our benchmarking finds that entry-level machines can incur substantially higher blade and anvil replacement frequencies, with knock-on effects for feed rates and lifecycle cost. Procurement decisions that focus solely on purchase price risk higher lifetime spend.
- Standardization and safety: EN 13525, AS/NZS 4024.1 and ISO 11448 remain binding for machine design and operation. Manufacturers that embed these standards early limit downstream liability and accelerate access to regulated markets.
- Product bifurcation: Demand is bifurcating into high-capacity industrial chippers for biomass and pulp operations, and compact, low-emission or electric solutions for arboriculture and urban applications. Each segment has distinct go-to-market and service requirements.
Competitive landscape — what the majors signal
The competitive map combines legacy OEM strengths (industrial scale, dealer networks) with agile regional specialists focused on niche requirements (compact tracked units, PTO-towed machines, or premium self-propelled designs). Our competitive chapter profiles leading OEMs and identifies the strategic implications of their recent moves without disclosing transaction-level or segment share tables reserved for the full report.
Highlights from company-level patterns:
- Product leadership and differentiation: Firms such as Vermeer emphasize proprietary crushing and feed technologies for throughput and consistency, while others (e.g., Morbark, Terex/CBI) reinforce high-capacity drum and whole-tree solutions tailored for biomass and industrial applications. These technology choices materially affect buyer segments, maintenance regimes and aftermarket opportunities.
- Warranty and service as competitive weapons: Extended warranty programs and parts availability (for example, multi-year or hour-based guarantees) are being used to offset premium pricing and to lock-in fleet operators.
- Geography-driven playbooks: Some manufacturers prioritize road-towable and compact chippers for arborists and municipalities, while others focus on tub grinders and industrial chippers for mills and land-clearing contractors. The report evaluates each player’s manufacturing footprint, channel depth and product roadmap to assess scalability.
- Recent strategic moves worth attention: Product launches of large-capacity whole-tree chippers and compact professional models, an OEM acquisition that consolidates complementary technologies, a contract award for a bespoke drum chipper to a major mill, and supplier appointments for critical wear parts — together, these developments indicate both ongoing product innovation and ecosystem strengthening among incumbents.
From insights to action — what executives can do in 2026
We designed this study as a playbook for the decisions that matter in the coming 12–24 months. Below are the practical outputs and how to use them.
- Portfolio & product decisions: Use our demand segmentation and elasticity models to decide whether to prioritize electrified compact units, invest in high-capacity whole-tree lines, or pursue modular architectures that lower service downtime.
- Pricing & go-to-market: Benchmarks for dealer margins, service revenue potential and replacement-part pricing enable data-driven pricing strategies and subscription models (e.g., knife-management contracts, uptime guarantees).
- Supply chain and sourcing: The report maps critical single-sourced components (after-treatment modules, high-grade steels for knives) and recommends near-term hedging, dual-sourcing, or local manufacturing options aligned with 2026 procurement cycles.
- M&A and partnerships screening: A targeted list of bolt-on opportunities and capability gaps is provided, scoring targets by strategic fit, integration complexity and likely synergies for both OEMs and investors.
- Compliance & safety roadmap: The study translates EN, ISO and national emission frameworks into an actionable compliance timetable and cost schedule so product teams can prioritize design changes ahead of regulatory enforcement windows.
What we do not publish here — and why you should request the full analysis
To preserve the commercial integrity of the intelligence and to encourage direct engagement, this preview intentionally omits the detailed segmentation tables, regional and end-use splits, and the full competitive concentration matrices. The complete report contains:
- Granular segmentation across geography, type and application with modeled revenue paths and elasticities;
- Consolidation metrics and concentration ratios with implication matrices for new entrants vs incumbents;
- Full financial-model workbooks (USD million base, forecasted P&Ls for product lines and scenario-adjusted capex plans);
- Vendor-level SWOTs and an executable 90-day market-entry checklist for OEMs, distributors and private equity investors.
Practical scenario examples (samples from the report)
- Scenario A — Premium industrial focus: A mid-sized OEM redirects 60–70% of R&D to high-capacity drum and whole-tree platforms and pursues a service-first warranty play. Our scenario model shows how this strategy affects utilization thresholds and aftermarket revenue over a 5-year horizon.
- Scenario B — Electrification and urban niche: A distributor pivots toward compact electric and low-emission petrol models for municipal and arborist fleets, pairing machines with battery-as-a-service offerings to reduce operator up-front cost and increase retention.
- Scenario C — Parts and service consolidation: An aftermarket specialist negotiates exclusive supply of knives and wear components to capture recurring revenues; our sensitivity analysis indicates the point at which parts margin begins to offset declining machine sales in a mature market.
Final guidance for 2026 planning
Executives should treat the 2026 planning cycle as an inflection point: the market is not a binary growth story, but a mosaic of stable core demand and fast-evolving subsegments. Strategic clarity requires marrying the macro growth trajectory (6.1% CAGR) with granular insights on regulatory cost, maintenance economics and competing OEM roadmaps. Where to compete, at what price, and how to lock-in aftermarket revenue will determine winners.
To access the full suite of models, segmentation data, competitor concentration metrics, and the executable 12–24 month playbook that underpins these executive recommendations, please consult the complete Wood Chippers Market report from PW Consulting. Our full analysis supplies the confidential line-item breakouts and scenario workbooks that boards and investment committees will need to make rigorous 2026 commitments.
For detailed analysis of this topic, please visit the official page: Wood Chippers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


