



PW Consulting: Wood Construction Screws Market to Reach USD 7.3B by 2032 at 5.07% CAGR

Wood Construction Screws Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused strategic preview of our new Wood Construction Screws Market study (base year 2025, historical 2020–2025, forecast 2026–2032). This preview is designed to demonstrate the analytical depth available in the full study and to highlight the specific kinds of decisions that 2026 executive teams can and should be preparing for. We intentionally keep detailed segment-level figures and proprietary tables out of this preview; those granular insights are available only in the full report and supporting datasets.
Wood Construction Screws Market
Quick market pulse — direction and scale
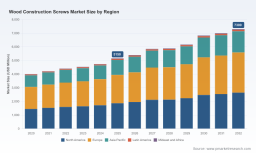
The wood construction screws market has reflected steady expansion through the early 2020s, rising from approximately USD 4.0 billion in 2020 to USD 5.15 billion in 2025. Our forecast scenario projects continued growth through the 2026–2032 horizon at a compound annual growth rate (CAGR) of roughly 5.07%, reaching an aggregate market size in the neighborhood of USD 7.3 billion by 2032. This growth trajectory is driven by a combination of rising construction activity in many markets, increasing adoption of engineered wood products, premiumization of fastening systems for structural applications, and tighter regulatory and certification requirements that favor higher-specification fasteners.
Wood Construction Screws Market
Why this study matters for 2026 corporate strategy
- Timing for capex and product investments. A mid-single-digit CAGR offers predictable demand expansion but requires targeted investments (product development, test labs, coating lines) to capture premium segments and defend margins against commoditisation.
- Certification becomes a competitive moat. With stricter building codes and a heavier emphasis on validated performance, firms that secure third-party approvals and test data will shorten sales cycles in structural and engineered-wood projects.
- M&A and distribution consolidation opportunities. The market remains fragmented enough to create attractive bolt-on targets for regional scale and technical capability; there are also clear advantages to consolidating distribution in key trade channels.
- Supply-chain risk management is not optional. Tariff shifts and raw material constraints require dynamic sourcing and hedging strategies. Scenario-ready procurement plans are a must for 2026.
- Value-based pricing and channel segmentation. Increasing product complexity (coatings, stainless grades, engineered-head designs) allows credible tiered pricing, but requires customer-education and channel incentives to realize margin uplift.
What the full PW Consulting study delivers (practical content)
The report is written for commercial and strategic teams who must turn market intelligence into executable plans. Key deliverables include:
Wood Construction Screws Market
- Verified market sizing and a time-series model (2020–2032) that supports top-down and bottom-up scenario runs.
- Forward-looking demand drivers and downside stress tests tied to macroeconomic, regulatory and construction-sector variables.
- Go-to-market playbooks for OEMs, branded manufacturers and distributors, including channel margin models, trade promotion frameworks and digital-sell strategies.
- Product roadmaps and technical decision matrices to prioritize coatings, alloys and form-factors for different structural use-cases.
- Supply-chain and procurement playbooks with cost-sensitivity analyses and multi-supplier sourcing templates that reflect tariff and raw material shock scenarios.
- M&A target-screening methodology and valuation ranges for tuck-in vs platform acquisitions, plus an acquisition due-diligence checklist focused on product certification, IP, and test assets.
- Implementation-ready KPIs, pilot designs, and a 90–180 day rapid-win list for commercial leaders to capture share during 2026.
- Primary qualitative intelligence: interviews with manufacturers, distributors, standards bodies and lead contractors, synthesized into actionable insights.
Competitive landscape — structural positions and recent moves
The competitive field combines established fastener brands, specialist screw manufacturers and broader industrial suppliers. Market concentration metrics point to a market where a small number of global players exert influence but meaningful share remains distributed across regional specialists and private-label manufacturers. PW Consulting’s analysis shows a modest top-three concentration and a broader top-five that still leaves room for nimble challengers.
- SPAX International GmbH & Co. KG (Ennepetal, Germany) — Recognized for engineered structural screw systems, SPAX continues to invest in corrosion-resistant series for heavy timber, underpinning its position in engineered-wood construction.
- SFS Group (Baar, Switzerland) — A diversified supplier with a strong foothold in timber fasteners. Recent European acquisitions expand its structural fastening portfolio and distribution reach, strengthening its bid to offer full-system solutions.
- Grip-Rite (Clinton, Missouri, USA) — Focused on outdoor and decking segments with branded DeckForce lines; its core strength is trade-channel penetration and volume SKU management.
- Simpson Strong-Tie (Pleasanton, California, USA) — Blends product innovation with code-driven positioning; recent launches of double-thread and specialty structural screws broaden its specification reach.
- GRK Fasteners (Twin Falls, Idaho, USA) — Differentiates on high-performance structural designs and targeted specification wins in heavy timber and engineered framing.
- fischer Group (Waldachtal, Germany) — Leverages system-engineering and countersunk product lines targeted at solid wood and engineered timber markets.
- Eurotec (Bozano, Italy), Würth Group (Künzelsau, Germany), Kyocera Senco (Fredericksburg, Virginia, USA), FastenMaster (Spartanburg, South Carolina, USA) — These players round out a competitive set that includes specialized design offerings, broad distribution networks, and strong brand recognition in trade channels and construction specifications.
Recent industry actions — acquisitions expanding European portfolios and targeted product launches — underline two concurrent trends: (1) consolidation along the value chain to deliver system-level solutions for timber construction, and (2) incremental innovation focused on corrosion resistance, drive efficiency, and load-bearing performance. Both trends create immediate strategic choices for incumbents and entrants.
Regulatory and certification context that will shape 2026 outcomes
- Stringent national and local building codes increasingly require certified structural fasteners; this shifts specification power toward suppliers that can provide third-party verification (e.g., ICC-ESR, TERS).
- International standards (e.g., ISO material and dimensional specifications) and environmental compliance rules are raising the bar for production processes and material compositions.
- Trade policy developments can create sudden margin pressure — for example, new tariffs on softwood imports introduce cost volatility for downstream timber construction and indirectly influence fastener demand dynamics.
Strategic playbook for 2026 — practical next moves
Based on our scenario analysis, executive teams should prioritize a small set of high-conviction actions in 2026:
- Secure certification and test capacity now. The lead time for third-party approvals and lab validation is long relative to procurement cycles. Start certification projects in H1 2026 to maximize spec wins in H2 and beyond.
- De-risk raw-material sourcing. Implement layered procurement strategies (dual sourcing, contractual hedges) and build contingency inventories keyed to tariff and supply shocks.
- Right-size product portfolios. Shift SKUs toward premium fasteners where technical differentiation and certification support price premiums; discontinue low-margin commodity SKUs that tie up working capital.
- Targeted M&A and partnerships. Use bolt-on acquisitions to access test laboratories, niche design IP, or strong regional distribution networks rather than broad, expensive roll-ups.
- Commercial transformation. Invest in specification engineering teams and training for distributor partners to translate technical benefits into procurement decisions at the contractor level.
- Scenario planning and cadence. Build a quarterly decision cadence that uses model outputs from our forecast toolkit—run downside and upside cases tied to construction activity, tariffs, and material-cost swings.
Why PW Consulting’s study is the right starting point
Our study combines quantitative forecasting (verified time-series models and sensitivity testing) with primary interviews, on-the-ground channel checks and a practical toolkit for implementation. We intentionally stop short of providing segment-level numbers in public previews; the full granularity — regional splits, type-by-application breakdowns, SKU-level price decks, and company-level market shares — is packaged in the report and associated data files to support investment memoranda, commercial planning and M&A diligence.
For leadership teams preparing 2026 budgets and strategic roadmaps: the market’s steady expansion (mid-single-digit CAGR to 2032) creates opportunities for disciplined, technically-led players to expand margins and share. The strategic choices you make in 2026 — around certification, product portfolio, supply-chain resilience and M&A discipline — will determine whether you capture the upside or become a low-margin supplier in an increasingly code-driven market.
Contact PW Consulting to request the full report, access our interactive forecast model, or arrange a senior-team workshop to translate these findings into a 90–180 day action plan tailored to your business.
For detailed analysis of this topic, please visit the official page: Wood Construction Screws Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


