



PW Consulting: SBC Market at USD 2,900M in 2025, poised for 5.5% CAGR (2026-2032)

Single Board Computer (SBC) Market — 2026 Strategic Primer
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a focused executive primer on our Single Board Computer (SBC) market study — a practitioner’s intelligence product designed to inform high-stakes corporate decisions in 2026. This overview distills the report’s strategic value, highlights the competitive fault lines reshaping supplier choice, and outlines the operational playbooks that matter for procurement, product architecture and M&A evaluation. It deliberately previews our analytical approach and headline market dynamics while reserving the granular segment and share data for the full report — the actionable intelligence that enables confident decisions.
Single Board Computer (SBC) Market
Market at a Glance: headline sizing and trajectory
By our base year (2025) accounting, the global SBC market reached roughly USD 2.9 billion. Looking forward, the market is expected to expand at a compound annual growth rate (CAGR) of approximately 5.5% across the 2026–2032 forecast horizon, taking the market into the low‑to‑mid USD 4‑billion range by 2032. That steady growth masks meaningful structural change: the market is shifting from hobbyist and education-first use cases to commercially driven deployments in edge AI, industrial automation and embedded IoT. For any organization evaluating platform choices or supplier strategies in 2026, the question is no longer whether SBCs fit your architecture — it is which SBC ecosystem, BOM structure and partner model will minimize technical debt and maximize time-to-market over the next five to seven years.
Single Board Computer (SBC) Market
Why this study matters for 2026 decision cycles
-
Portfolio prioritization under uncertainty — SBCs are now strategic components in product roadmaps for gateways, vision systems, and compact AI inferencing nodes. Our study translates macro growth into actionable decision triggers: when to standardize on ARM-based reference platforms, when to preserve x86 or RISC‑V options for legacy or specialized workloads, and when to hedge across multiple architectures to protect roadmap optionality.
Single Board Computer (SBC) Market -
Supply-chain realism — component concentration and SoC pricing dynamics materially affect unit economics. For higher‑spec boards, ARM-based SoCs represent the dominant cost position in the bill‑of‑materials, a factor you must quantify when negotiating supplier contracts or planning BOM substitutions. The report includes a procurement sensitivity model that shows how supplier pricing and SoC availability scenarios impact product gross margins.
-
Regulatory & export-policy risk — export controls on advanced semiconductors create asymmetric availability across regions and can upend supplier selection for multinational deployments. Our legal and trade annex translates current control regimes into practical sourcing constraints and contingency checklists suitable for product and legal teams.
-
Technology inflection points — the rapid introduction of AI‑capable boards and compute modules is changing system partitioning. Our technology roadmap maps the timing and practical thresholds (performance-per-watt, NPU availability, thermal envelopes) that tip a design from “software-only” to “hardware-accelerated” edge AI.
What the full report delivers (practical, hands‑on content)
-
Market-sizing methodology and validated historical series (2020–2025) plus scenario-driven forecasts (2026–2032) — with sensitivity bands reflecting supply shocks and accelerated AI adoption.
-
BOM and cost engineering playbooks that quantify the cost impact of alternate SoCs, memory tiers and connectivity options; includes vendor negotiation levers and SKU rationalization frameworks.
-
Go‑to‑market and channel strategies for enterprises and OEMs: design partnership models, volume discount strategies, and fulfilment architectures for global rollouts.
-
Competitive mapping and positioning matrices that analyze product, pricing, and downstream ecosystem strengths — essential for supplier selection and M&A screening.
-
Risk and compliance annexes: export control implications, quality management standards relevance (e.g., ISO 9001 in manufacturing chains), and an IP/supply compliance checklist for accelerated prototyping.
-
Decision tools — downloadable templates and dashboards: supplier scorecards, TCO calculators, migration roadmaps and an edge‑AI readiness index to benchmark candidate SBCs against project requirements.
Competitive landscape — who matters and why
The SBC ecosystem combines legacy community-driven players, nimble Chinese OEMs, and industrial suppliers focused on ruggedized, certified modules. Understanding each cohort’s strengths is essential to match a supplier to your program risk profile.
-
Raspberry Pi Foundation (Cambridge, UK): the de facto standard-bearer in community and education markets, and increasingly present in commercial prototyping thanks to strong software ecosystem and brand recognition. Recent product moves extend their keyboard-form and module offerings, reinforcing their role as a baseline reference platform for developers.
-
BeagleBoard.org Foundation (Oakland Twp, MI): maintains a strong open‑source interoperability and standards posture. For organizations prioritizing open hardware/software stacks and long‑term maintainability, BeagleBoard’s community-driven models reduce integration friction.
-
Chinese OEMs (Orange Pi, Radxa, Banana Pi, Khadas, FriendlyElec): these manufacturers are accelerating technical feature parity and price performance. Recent launches demonstrate broader support for high‑performance compute and alternative ISAs (including RISC‑V experiments), creating competitive pressure on traditional suppliers.
-
Industrial suppliers (Avalue Technology, Axiomtek, Kontron): focus on ruggedization, certification, and enterprise lifecycle support. Their Pico‑ITX and industrial SBCs are designed for longer product lifecycles and deterministic supply — crucial for automation and mission‑critical deployments.
New entrants and module vendors such as LattePanda and Quectel are also relevant for niche x86 use cases and integrated IoT prototyping respectively. Across the board, product launches from late 2025 through early 2026 underscore two dynamics: (1) feature convergence between hobbyist and industrial boards (performance, memory, onboard NPUs), and (2) faster cadence of new SKUs, which increases obsolescence risk for long‑lifecycle systems.
Recent product and market signals (selection)
-
Multiple vendors accelerated high‑performance and AI‑capable board releases in late 2025 and early 2026 — an indicator that vendors are racing to capture developer mindshare and early enterprise adopters.
-
Industrial suppliers introduced ultra‑compact Pico‑ITX solutions targeting AI-native portable systems — a clear signal that edge AI is pushing form‑factor innovation into certified industrial footprints.
-
Open‑source and community foundations continue to invest in interoperability standards — a structural advantage for enterprises seeking predictable software stacks and long-term maintainability.
Strategic implications and recommended actions for 2026
-
Define a platform taxonomy aligned to business objectives: “innovation,” “volume product,” and “mission‑critical” should map to distinct procurement rules (community boards for R&D, vetted OEMs for scaled products, industrial suppliers for critical systems).
-
Embed BOM scenario planning in product development: require suppliers to provide alternate SoC and memory pathways; run our sensitivity model to quantify margin and lead‑time risk for each design choice.
-
Prioritize supplier audit and compliance timelines: export controls and quality certifications materially affect cross‑border rollouts — integrate legal and T3 supplier audits before committing to long‑lead contracts.
-
Adopt a staged validation program for AI-capable boards: bench and field tests should validate performance, thermal behaviour, and software stack compatibility under representative loads — reduce surprise later in production.
-
Consider strategic partnerships and minority investments: selective engagement with innovative OEMs can secure supply and early access to roadmap features—particularly where RISC‑V or alternative architecture support is a strategic hedge.
How to use the full PW Consulting SBC study
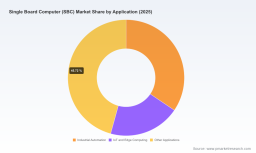
The report is built for execution teams: product managers, procurement, and corporate development. Use it to (a) accelerate supplier shortlists with our scorecards, (b) quantify cost and time-to-market trade-offs with the included TCO and BOM models, and (c) identify M&A and partnership targets via our competitive matrices and recent developments tracker. Importantly, the granular segment intelligence (regional splits, application shares, vendor revenue shares and CR metrics) is intentionally held in the substantive report package to preserve its value as decision-grade intelligence.
Conclusion — a pragmatic next step
For 2026, SBC strategy is less about whether to adopt and more about how to adopt resiliently. The market’s steady growth trajectory and rapid technical iteration require disciplined platform governance, supply‑chain contingency planning, and deliberate investment in software portability. Our study supplies the models, supplier intelligence, playbooks and compliance tools required to make those calls. For the detailed segment allocations, competitive shares and downloadable decision tools that execute the strategies summarized here, access the full PW Consulting SBC Market report and the accompanying Excel workbooks.
Contact PW Consulting for an executive briefing, tailored supplier scorecard, or deployment readiness assessment to translate these insights into an executable 2026 SBC strategy.
For detailed analysis of this topic, please visit the official page: Single Board Computer (SBC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


