



PW Consulting: Ultra-Pure Sulfuric Acid Market Outlook — 3.2% CAGR to 2032

Ultra-Pure Sulfuric Acid Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
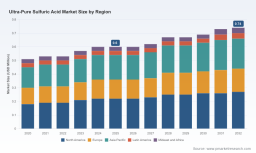
As PW Consulting’s lead industry analyst, I present a forward-looking briefing designed to equip C-suite and strategy teams with the context they need as 2026 unfolds. Our Ultra-Pure Sulfuric Acid (UPSA) Market study (base year 2025; historical 2020–2025; forecast 2026–2032) shows a compact, technically intensive market that has demonstrated steady, measured expansion—rising from roughly USD 0.5 Million in 2020 to about USD 0.6 Million in 2025. We expect continued, low-single-digit compound annual growth through the forecast window, with a 3.2% CAGR and a projected market size approaching USD 0.74 Million by 2032 (values in USD Million).
Ultra-Pure Sulfuric Acid Market
This briefing is a “trailer”: it communicates the report’s strategic value, highlights key dynamics and competitive moves, and outlines the kinds of actionable insights the full study delivers—while intentionally withholding granular segment-level figures and confidential modelling outputs to preserve the motivation for accessing the full report.
Ultra-Pure Sulfuric Acid Market
Why this market matters to 2026 strategic agendas
- Enabler of high-value ecosystems: Ultra-pure sulfuric acid is a critical consumable in semiconductor wafer processing, select pharmaceutical synthesis routes, and advanced chemical manufacturing. Its purity and supply reliability directly influence yield, throughput and contamination risk across wafer fabs and other precision plants.
- High technical and regulatory barrier to entry: Producing UPSA at semiconductor-grade purity requires specialized technology, rigorous quality systems, and regulatory compliance frameworks, creating defensible positions for incumbent manufacturers.
- Supply chain sensitivity: Feedstock volatility (notably elemental sulfur pricing and supply dynamics) and evolving environmental standards make procurement strategy and feedstock risk management top priorities for both suppliers and large end-users.
- Market structure concentrates influence: The market is relatively consolidated—top-tier suppliers command a majority share—so actions by a few players (capacity expansions, product qualification programs, strategic supply agreements) can materially affect availability and commercial terms.
What the full report delivers (practical scope)
- Validated historical market sizing (2020–2025) and a transparent forecasting model (2026–2032) with scenario analysis that isolates demand drivers tied to semiconductor capex, regional fab builds, and selected specialty chemical flows.
- Commercial playbooks for buyers and suppliers: qualification timelines, contamination mitigation protocols, specification harmonization checklists, and contracting templates aligned to semiconductor vendor practices.
- Supplier scorecards and a competitive benchmarking matrix evaluating production footprint, purity capability, on-spec yield, cost-of-quality, and go-to-market models—designed to inform sourcing and M&A diligence.
- Regulatory risk maps and compliance checklists (US, EU, and key APAC jurisdictions), plus stress-tested operational scenarios for emissions and reporting obligations under recent regulatory updates.
- Operational mitigation strategies: feedstock hedging options, co-product valorization, and recommendations for near-source buffer inventory and micro-logistics to minimize downtime risk for fabs and critical synthesis lines.
Market dynamics you must track in 2026
- Feedstock and input-cost volatility: Elemental sulfur supply tightness and price movements have reappeared as a material input risk. Supply constraints driven by fertilizer and metals-processing demand—together with recovery rates at refineries—are driving procurement teams to revisit supplier diversification and forward purchase programs.
- Regulatory tightening and reporting: Recent enforcement and reporting regimes (for example, US EPA New Source Performance Standards for sulfuric acid plants and chemical reporting mandates) increase compliance costs and lengthen qualification lead times for new production assets. These dynamics raise the bar for greenfield entrants and elevate the value of trusted, audited suppliers.
- Fab and regional capex alignment: New semiconductor capacity investments—particularly in regions with coordinated incentives—are stimulating localized demand spikes for ultra-pure chemicals. Strategic suppliers are responding with targeted capacity projects and qualification partnerships; buyers must map supplier roadmaps to their fab ramp schedules to avoid bottlenecks.
- Concentration and bargaining dynamics: With the top suppliers collectively commanding a significant share of market supply, commercial negotiations are asymmetric. Buyers with predictable multi-year volumes can secure favorable terms; smaller consumers face higher exposure to spot-price swings and lead-time risk.
Competitive landscape — what incumbents are doing
The industry is anchored by global chemical groups and specialty electronic-chemicals firms that combine legacy process knowledge with electronic-grade quality systems. Key market participants include established multinational producers and niche specialists known for semiconductor qualification programs and stringent materials management.
Ultra-Pure Sulfuric Acid Market
- Strategic capacity shifts: Leading producers have recently signaled capacity investments targeted at semiconductor-grade capability. Announcements include European capacity expansions expected to come online in the mid-decade window—moves that are explicitly intended to serve wafer-cleaning and fabs backed by public incentives.
- Vertical positioning: Some players are integrating quality and logistics services—offering on-site blending, dedicated-purity packaging, and qualification support—to shorten time-to-qualification for wafer fabs and to capture higher-margin service revenue.
- Selective regionalization: Suppliers are calibrating footprint strategies to align with the nearshoring of semiconductor fabs; where demand volumes justify investment, providers are accelerating local capacity and qualification roadmaps to de-risk customer supply chains.
Our report’s company-level assessments profile leadership, technical differentiators and commercial strategies for principal suppliers—providing procurement and corporate strategy teams with the intelligence needed to prioritize supplier engagement and M&A screening.
Regulatory and ESG considerations that change deals
- Emission and reporting regimes: New source performance and chemical reporting standards require firms to quantify and manage emissions and to report production/use data—factors that can increase time and cost to scale new capacity and that also affect the diligence profile for potential targets.
- Environmental performance as commercial leverage: Fabricators increasingly require suppliers to demonstrate low environmental impact and traceable audits. Suppliers that can prove lower emissions intensity, circular feedstock usage or best-in-class waste management will gain commercial preference.
- Permitting and community risk: Local permitting complexity can extend project timelines; the full study includes a permitting risk heatmap and mitigation playbook for planned capacity expansions.
Actionable recommendations for 2026 corporate agendas
- Buy-side: Secure qualification paths now. If your operations depend on ultra-pure sulfuric acid, initiate multi-party qualification programs tied to fab ramp schedules. Consider staged supply agreements that combine committed volumes with capped spot exposure to balance cost and security.
- Supply-side: Turn purity expertise into service revenue. Beyond commodity supply, package qualification support, contamination-control advisory services, and tailored logistics into higher-margin offerings—particularly for semiconductor customers that value fast time-to-production.
- Investors and M&A teams: Screen for strategic assets. With market concentration favoring a few high-capability suppliers, mid-sized assets that shorten qualification timelines or expand regional presence can be accretive. Prioritize targets with audited quality systems, low time-to-qualify, and manageable environmental footprints.
- Risk management: Hedge feedstock exposure and plan buffers. Given feedstock price movement and periodic shortages, design procurement strategies combining forward contracts, strategic inventory, and alternate sourcing lanes to preserve uptime for critical processes.
- Regulatory readiness: Build compliance into commercial proposals. Factor emissions and reporting obligations into pricing and project timelines. Early engagement with local regulators and transparent reporting roadmaps can materially shorten approval cycles.
What you will not find here (and why it matters)
To preserve the report’s utility as an operational decisioning tool, this preview omits granular segment-level allocations, region-by-region revenue breakdowns, and precise application share figures. Those outputs—alongside supplier scorecards, pricing curves, and bespoke scenario models—are included in the full PW Consulting report and are essential for contract negotiation, capex scheduling, and M&A valuation work.
Next steps — how to use our work in 2026 planning
- Commission the full report for procurement and technical teams to obtain the segment-level forecasts, supplier benchmarking and qualification timelines necessary for contracts and capex alignment.
- Use the included scenario models to stress-test your supply plans against feedstock-constraint and regulatory-change scenarios for robust contingency planning.
- Engage PW Consulting for a tailored supplier diligence or target-screening engagement if you are evaluating capacity build, JV or acquisition opportunities.
In markets where purity, reliability and regulatory certainty drive commercial outcomes, having the right intelligence is not optional—it’s a competitive differentiator. PW Consulting’s Ultra-Pure Sulfuric Acid Market study is designed to convert industry complexity into clear actions for 2026. For the detailed segmentation, vendor profiles, and financial models that corporate and procurement teams require to execute with confidence, consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Ultra-Pure Sulfuric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


