



PW Consulting: Ultrasonic Flaw Detector Market Set to Expand at 7.8% CAGR Through 2032

Ultrasonic Flaw Detector Market: Strategic Outlook for 2026 Decision‑Makers
Executive snapshot
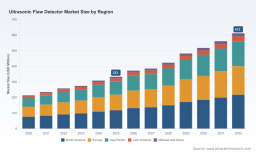
Between 2020 and 2025 the global market for ultrasonic flaw detectors moved from an early‑maturing niche toward a predictable growth phase, driven by stronger demand for non‑destructive testing across heavy industry, transport and energy sectors. Using 2025 as the base year, our research places the market at roughly USD 333 million and models a clear upward trajectory through the 2026–2032 forecast window, with a compound annual growth rate (CAGR) of 7.8% that sees the market roughly double in scale by the end of the period. This combination of steady organic demand and pockets of rapid adoption (phased‑array, digital workflows, service models) creates a set of high‑leverage strategic choices for suppliers, integrators and investors in 2026.
Ultrasonic Flaw Detector Market
Why this matters for 2026 decision cycles
- Investment timing: The projected mid‑to‑late decade acceleration means product roadmaps and capital allocation plans begun in 2026 will capture the most commercially attractive portion of the cycle.
- Go‑to‑market focus: Buyers increasingly prefer integrated hardware + software inspection solutions and service contracts; vendors who can bundle calibration, training and digital reporting will win share and margin.
- Regulatory and procurement risk: Heightened standardization around calibration and phased‑array verification is changing procurement checklists — compliance will be table stakes for enterprise contracts.
Forces shaping supply, demand and returns
Our analysis groups the dynamics into four influencing layers:
Ultrasonic Flaw Detector Market
- Technology: Phased‑array ultrasonic testing and interpretive software continue to migrate from specialized labs into routine field inspection. Portable devices are evolving into software‑centric instruments with cloud‑enabled data management and automated analysis pipelines.
- Standards and regulation: Recent updates to calibration and verification standards — including new emphasis on equipment traceability and reference block accuracy — change buyer evaluation criteria and extend sales cycles for non‑compliant offerings. UNE‑EN ISO 22232‑1 and related ISO updates are shaping RFP language and acceptance testing practices.
- Supply chain and components: Piezoelectric transducer technology remains the dominant sensor architecture; our sector analysis shows bulk piezoelectric segments capturing the lion’s share of related sensor demand by 2026, a structural factor that keeps unit costs down but concentrates raw‑material exposure in a few supplier lines.
- Operational economics: Adoption of automated inspection workflows reduces technician dependency, shortens on‑site time and lowers training burden. That same automation shifts value from hardware unit sales to software licenses, data services and recurring calibration/maintenance revenues.
Competitive landscape — who matters and why
The market is neither a monopoly nor highly fragmented: the leading vendors command meaningful share, but mid‑tier and regional suppliers remain important partners for field service and low‑cost segments. Top incumbent brands combine global channel reach with recognized hardware platforms; smaller vendors compete on price, service agility and local relationships.
Ultrasonic Flaw Detector Market
- Waygate Technologies (Houston, USA) — A platform leader with broad portable and phased‑array portfolios (Mentor UT family, Krautkramer models). Strengths: deep enterprise relationships in energy and heavy industry, advanced phased‑array capabilities and validated calibration workflows. Strategic implication: incumbency advantage in large industrial tenders but exposure to price competition at the base of the market.
- Evident Scientific / Olympus IMS (Waltham, USA) — Offers conventional and phased‑array systems (EPOCH, OmniScan series) with strong software ecosystems for data capture and analysis. Strengths: integration of hardware and analytics; preferred by service providers focused on complex inspections. Strategic implication: prime target for partnerships where software differentiation is the sales hinge.
- Sonatest (Pune, India) — Competes on portable and phased‑array products designed for field use (WAVE, Veo3, Sitescan lines). Recent product documentation updates in 2025 sharpen its product claims and channel collateral. Strengths: agile product refresh cycles and competitive pricing. Strategic implication: an effective challenger for growth in emerging markets and service fleets.
- Danatronics (USA) — Specialist in compact portable detectors (ECHO FD, Echo Pro), with a 2025 product launch emphasizing simplified user workflows. Strengths: focused product set with rapid time‑to‑market. Strategic implication: attractive acquisition target for larger firms wanting entry into specific portable segments.
- SIUI (Shantou, China) — Offers compact, cost‑effective portable detectors tailored for general industry. Strengths: low‑cost manufacturing and wide distribution in price‑sensitive markets. Strategic implication: continuing price pressure at the low end; necessity for western OEMs to upgrade service and compliance offerings to defend margins.
- NDT Systems Inc., Zetec Inc., Elcometer — These vendors add depth across legacy digital systems, high‑performance UT equipment and ergonomically designed handhelds. Strengths: niche specialization and strong aftermarket/service presence. Strategic implication: consolidation candidates or strategic partners for service expansion.
Market concentration is moderate: the top three vendors capture less than half of total revenue, and the top five capture just over half. That structure leaves room for targeted M&A and regional plays while preserving substantial opportunity for differentiated product and service strategies.
Strategic playbook for 2026
For executives preparing 2026 plans, the following moves translate the market outlook into action:
- Prioritize software and data services: Reallocate R&D budgets from incremental hardware refinements into analytics, cloud reporting and AI‑assisted defect calling. Even modest subscription revenue can materially improve long‑term value capture.
- Invest in compliance and verification: Ensure product roadmaps and factory calibration workflows comply with evolving standards. Winning enterprise deals increasingly hinges on transparent calibration traceability.
- Secure piezoelectric supply lines: Evaluate multi‑sourcing, long‑term purchase agreements or vertical partnerships for transducer supply to dampen component volatility and avoid single‑source risk.
- Design a hybrid go‑to‑market: Combine global OEM branding with local service partners to reach price‑sensitive segments without eroding margin in premium accounts. Use training and certification programs as lock‑in mechanisms.
- Hunt for tuck‑ins that add service revenue: Identify mid‑tier vendors with strong field service footprints or complementary software capabilities — these are the most accretive M&A targets for revenue growth and faster ARR conversion.
- Repackage offerings for OPEX buyers: Create inspection‑as‑a‑service and managed‑inspection programs tailored to oil & gas, aerospace and manufacturing customers that prefer predictable operating expenditures.
What PW Consulting’s full study delivers — operational and executable
This research is designed to be a practical toolkit for 2026 decision‑makers rather than a high‑level narrative. Deliverables include:
- Comprehensive market sizing and trajectory model (2020–2032) with scenario toggles — base, upside, downside — accessible as an interactive spreadsheet so finance teams can re‑run forecasts under alternative assumptions.
- Go‑to‑market playbooks for three archetypes (OEMs, service integrators, financial sponsors) including customer segmentation frameworks, price/value matrices and channel economics.
- Competitive benchmarking dashboard mapping product feature sets (portable vs stationary, phased‑array capability, software integrations), route‑to‑market strengths and aftermarket footprints for the eight core vendors profiled.
- Regulatory and compliance matrix that translates standards (calibration, verification, traceability) into product and process requirements, acceptance checklists and suggested certification timelines.
- Supply‑chain heat map and cost‑sensitivity analysis focused on transducer inputs and electronics — with practical mitigation options (buffer inventory, dual‑sourcing, supplier partnerships).
- M&A shortlist and valuation frameworks for acquisitive players — including suggested integration playbooks to convert hardware sales into recurring service revenue.
- 90/180/365‑day tactical action plan designed to accelerate wins in core accounts, deploy pilots of automated inspection workflows, and prioritize certification investments required by large buyers.
Practical first steps for executives in 2026
Short list of immediate actions to translate insight into results:
- Run a gap analysis between your product calibration processes and the latest standards; select a short list of corrective investments with clear ROI timelines.
- Launch a pilot that bundles inspection hardware with standardized cloud reporting and a subscription analytics tier; measure uplift in customer retention and bid conversion rates.
- Negotiate transducer supply options with at least two suppliers and model the P&L impact of tiered pricing scenarios across expected unit volumes.
- Identify one mid‑tier service firm with strong regional presence and evaluate a partnership or bolt‑on acquisition to accelerate service revenue and field coverage.
Conclusion — what this intelligence enables
For boards and executive teams planning allocations and strategic moves in 2026, the ultrasonic flaw detector sector presents a rare combination: steady, predictable growth at the market level combined with tactical inflection points at the product, service and regulatory layers. The winners will be those who convert hardware credibility into recurring data and service revenue, align product roadmaps to tightened calibration standards, and secure resilient component supply while defending premium accounts against low‑cost entrants.
Next step
PW Consulting’s full Ultrasonic Flaw Detector Market report includes the detailed tables, interactive models and segment‑level intelligence required to underwrite 2026 investments and M&A decisions. For access to the complete dataset, scenario models and proprietary company profiles, please visit our report page and request the executive briefing package.
For detailed analysis of this topic, please visit the official page: Ultrasonic Flaw Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


