



PW Consulting: Automotive Aluminium Extrusions Market to Reach USD 368.3M by 2032 at 8% CAGR

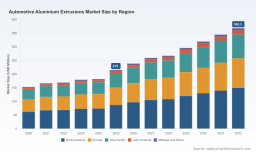
Automotive Aluminium Extrusions Market — Strategic Preview for 2026 Decision-Making
As automotive manufacturers and suppliers reset product roadmaps and capital plans for a post‑pandemic, electrified future, aluminium extrusions occupy a decisive position in the race to deliver lighter, safer and more energy‑efficient vehicles. PW Consulting’s forthcoming Automotive Aluminium Extrusions Market research — base year 2025, forecasting through 2032 — synthesizes the macro trajectory and the competitive dynamics firms must internalize to make confident 2026 investments.
Automotive Aluminium Extrusions Market
Why this research matters for 2026
-
Timing: With the study’s base year anchored in 2025 and a forecast window beginning in 2026, the analysis maps directly onto the investment horizon of many OEM and Tier‑1 capital projects, procurement contracts, and localization initiatives.
Automotive Aluminium Extrusions Market -
Market momentum: The global market shows a clear recovery and structural expansion — growing from approximately USD 153 million in 2020 to USD 215 million in 2025, and forecast to reach about USD 368 million by 2032 at a compound annual growth rate of 8.0%. This growth profile creates a runway for capacity investments, alloy development, and downstream integration.
Automotive Aluminium Extrusions Market -
Decision relevance: The report translates market growth into actionable choices — where to site capacity, which alloy platforms to prioritize, how to balance recycled content with mechanical performance, and how to reshape sourcing strategies in the face of supply concentration.
What’s changing in the market — dynamics that will shape 2026 plans
-
Electrification is accelerating aluminium demand: OEMs increasingly specify aluminium extrusions for EV structural frames and battery enclosures to achieve the twin goals of lightweighting and crash performance. This is not a marginal trend — industry research indicates aluminium content per vehicle is accelerating and will materially exceed early‑2020 levels as automakers reengineer platforms around battery packs.
-
Higher extrusion content per vehicle: Engineering trends and supplier designs have pushed extrusion content upward — historical estimates show a rise from roughly 35 pounds per vehicle in 2020 toward nearly 45 pounds by 2025, with modern vehicle architectures often containing around 50 pounds of extrusions in front‑end and roof structures. These per‑vehicle gains multiply quickly across global vehicle build plans.
-
Supply‑side consolidation and concentration: The market exhibits notable concentration at the top. The three largest suppliers control a substantial share of the market, and the top five command an even higher cumulative share. For procurement and risk managers, that concentration translates into both negotiating leverage and potential single‑point vulnerabilities.
-
Decarbonization and circularity: Low‑carbon and recycled aluminium is a competitive imperative. Leading suppliers are investing in closed‑loop recycling, low‑emission smelting, and alloy development targeted at retaining mechanical performance while lowering embodied carbon per kilogram.
-
Design complexity and integration: As multi‑material vehicles proliferate, extrusions are no longer standalone parts; they are engineered into hybrid assemblies, cast‑to‑extrusion joins, and adhesive‑integrated structural modules. Suppliers that can offer engineering services and validated assembly solutions win share more rapidly.
What the report contains — practical, transaction‑ready intelligence
-
Market sizing and scenario forecasts (2026–2032): Base‑year grounding plus three demand scenarios calibrated to EV penetration, aluminium price pathways, and vehicle production forecasts.
-
Value‑chain mapping and cost stacks: From billet sourcing to extrusion, heat treatment, finishing and machining — with pragmatic levers to reduce unit costs and carbon intensity.
-
Technology and alloy roadmaps: Comparative analysis of the 6xxx and 7xxx alloy families, high‑strength tempering routes, and secondary operations that affect part performance in crash and fatigue.
-
Buyer playbooks: Procurement frameworks, hedging approaches for aluminium feedstock, and supplier scorecards tailored for OEMs and Tier‑1s.
-
Operational diagnostics: Plant capacity planning templates, OEE benchmarks, and recommendations for ramp sequencing when converting legacy lines to higher‑precision extrusion workflows.
-
Risk registers: Supply concentration assessment, geopolitical scenarios, and near‑term raw material disruption matrices with mitigation options.
-
Deal and partnership playbooks: M&A valuation heuristics, JV structuring principles for local content programs, and cross‑border supply‑chain strategies.
Competitive landscape — strategic profiles and implications
The market features a mix of integrated upstream producers, specialist extruders, and regional champions. PW Consulting’s competitive analysis highlights strategic posture, capability gaps, and partnership vectors for the players that matter to OEMs and Tier‑1s.
-
Constellium SE (France) — Advanced extrusion systems and tailored structural components. Strength: engineering depth and program integration for structural integrity and sustainable mobility. Strategic implication: Constellium is a go‑to for OEMs seeking co‑development of crash‑relevant profiles and aluminium‑heavy architectures.
-
Novelis Inc. (United States) — Focus on high‑strength recycled alloys. Strength: closed‑loop recycling and rolled products that complement extrusion ecosystems. Strategic implication: Novelis’s emphasis on recycled content increasingly aligns with OEM ESG mandates, making it an attractive upstream partner for low‑carbon supply chains.
-
Norsk Hydro ASA (Norway) — Low‑carbon and recycled extrusion platforms. Strength: green aluminium credentials and supply integration. Strategic implication: Buyers with strict Scope 3 targets should prioritize contracts offering low‑emission aluminium claims validated by lifecycle analysis.
-
Kaiser Aluminum Corporation (United States) — High‑strength extrusion capabilities for EV battery frames and crash‑absorbing components. Strength: niche technical capability in high‑performance alloy systems. Strategic implication: Kaiser is well positioned to serve segments where mechanical performance and dimensional precision cannot be compromised.
-
UACJ Corporation (Japan) — Precision fabrication and tightly controlled process engineering. Strength: high‑volume, high‑precision production for body structures. Strategic implication: Asian OEMs and global platforms requiring tight dimensional and surface standards will favor UACJ’s offerings.
-
Arconic Corporation (United States) — Lightweight and corrosion‑resistant extrusion solutions. Strength: broad systems integration and multi‑material design support. Strategic implication: Arconic’s service breadth makes it a strong Tier‑1 candidate for global programs requiring coordinated materials engineering.
-
Bonnell Aluminum (United States) — IATF‑16949 certified supplier with OEM presence. Strength: certification pedigree and supplier reliability for mainstream automotive production. Strategic implication: Procurement teams will consider Bonnell for high‑volume closures and body‑in‑white integration where quality systems are non‑negotiable.
-
ETEM Gestamp Aluminium Extrusions (Bulgaria) — Crash‑relevant profiles and machined parts for OEMs and Tier‑1s. Strength: European footprint and tailored crash‑management designs. Strategic implication: Localized supplies for European programs and short lead‑time needs favor ETEM’s model.
-
Press‑Metal Aluminium Holdings Berhad (Malaysia) — Regional supplier for body‑in‑white components. Strength: competitive cost base and regional integration. Strategic implication: Cost‑sensitive programs and regional content policies make Press‑Metal a logical partner in Asia and adjacent markets.
-
Gränges AB (Sweden) — Extruded profiles for transportation applications. Strength: niche expertise in transport and finishing services. Strategic implication: Gränges is attractive for customers prioritizing surface engineering and downstream finishing standards.
Strategic takeaways for executives planning in 2026
-
Prioritize alloy and process flexibility: Given the pace of EV adoption and regulatory pressure on embodied carbon, firms must be capable of switching alloy mixes and heat‑treatment routes without costly line changeovers.
-
Embed carbon transparency into sourcing: Contracts with traceable recycled content and verified emissions data will increasingly be a procurement differentiator, not just a marketing advantage.
-
De‑risk supply concentration: With the top suppliers controlling a significant share of capacity, parallel sourcing, strategic stockpiles, and regional qualification pipelines are prudent tactics.
-
Make engineering services a commercial lever: Suppliers that offer co‑design, crash simulation, and assembly validation can capture part value and accelerate OEM time‑to‑market.
-
Plan capacity with scenario discipline: Use the report’s scenario forecasts to stress‑test capex decisions against EV adoption curves, aluminium price volatility, and geopolitical supply shifts.
How this preview intentionally withholds core segmentation
This article is designed as a strategic trailer: it highlights the market’s scale, growth trajectory and the practical levers that leaders must evaluate in 2026. To preserve the commercial utility of the full analysis, we have intentionally omitted the detailed segmentation matrices and the granular regional and application‑level splits that underpin supplier targeting, plant siting, and M&A valuation models. Those detailed matrices — including regional demand distribution, application mixes, and alloy‑level revenue breakdowns — are included in the full PW Consulting report and are essential for transaction execution and program qualification.
Next steps — how executives should use this intelligence
-
Procurement chiefs: Use the market concentration signals and supplier profiles to redesign sourcing strategies and hedge feedstock exposure.
-
Product and engineering leads: Validate alloy choices and extrusion content against the report’s scenario outputs before finalizing platform redesigns.
-
Strategy and corporate development teams: Leverage the report’s M&A playbook and valuation heuristics when screening acquisition targets or forming JVs to secure local content.
-
Operations and plant managers: Apply the operational diagnostics and ramp sequencing templates to reduce time‑to‑qualified production and mitigate rework rates.
For procurement contracts, capex decisions, and platform engineering that will be locked in during 2026, decision quality demands both a clear view of the macro growth curve and access to the granular segmentation that determines unit economics. PW Consulting’s full Automotive Aluminium Extrusions Market report provides that end‑to‑end intelligence — including the regional, application and alloy‑level breakdowns required to finalize supplier selections, capacity allocations and acquisition targets. Contact PW Consulting to access the complete dataset, detailed scenario models, and the supplier due‑diligence annex that underpins our recommendations.
For detailed analysis of this topic, please visit the official page: Automotive Aluminium Extrusions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


