



PW Consulting: Plastic Closure Market to Reach USD 344.8M by 2032 at 4.8% CAGR; Asia Pacific Leads

Plastic Closure Market 2026 Preview: Strategic Implications for Executive Decision-Making
As companies confront accelerating sustainability mandates, feedstock volatility, and a new wave of consolidation, the plastic-closure industry is entering a phase where strategic clarity will determine winners and laggards. PW Consulting’s latest Plastic Closure Market study (base year 2025) provides a practice-oriented toolbox for corporate leaders preparing 2026 budgets, capital plans, and M&A roadmaps. This preview explains why the report is material to boardroom decisions next year, what forces will most influence value creation, and how the full study equips executives to act — while intentionally withholding the granular segment tables and regional/application splits that are reserved for subscribers.
Plastic Closure Market
Market snapshot: scale, trajectory, and concentration
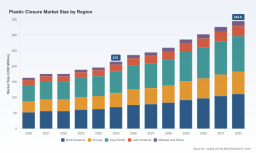
Our topline sizing places the global plastic-closure market firmly in expansion following a mid-cycle reset. After five years of historical measurement (2020–2025), the market reached an aggregate level in 2025 and is projected to grow through the forecast window at a compound annual growth rate (CAGR) of 4.8%. By the end of the 2026–2032 forecast horizon the industry is expected to be materially larger than it was in 2025, reflecting steady end-market demand across beverage, personal care, and pharmaceutical packaging.
Plastic Closure Market
Two structural features stand out. First, the market remains relatively fragmented: the top three and five suppliers together account for roughly a quarter of industry revenue, leaving meaningful commercial opportunity for regional specialists, niche innovators, and disciplined consolidators. Second, growth is sufficient to justify selective capacity investments but not so rapid as to eliminate downside risk from price and feedstock swings — a balance that calls for scenario-based capital allocation rather than binary “build or buy” decisions.
Plastic Closure Market
Why this matters for 2026 decisions
- Capex prioritization: With a moderate growth rate and pockets of overcapacity, greenfield and brownfield investments must be coupled with robust utilization scenarios. The report’s probabilistic capacity models convert market forecasts into utilization curves and payback windows specific to molding technologies (injection, compression, and hybrid solutions).
- M&A and partnership timing: The 2025 completion of Amcor’s acquisition of Berry Global — creating the largest combined rigid and flexible supplier — is a bellwether for further consolidation. Our M&A playbook quantifies potential synergies, integration risks, and defensive strategies for mid-sized players facing acquisition pressure.
- Procurement and raw-material strategy: Sustained feedstock volatility is no longer an episodic risk. Polypropylene, a core resin for caps and closures, experienced steep price appreciation in early 2026. The report provides hedging frameworks and supplier-contract structures to manage margin erosion across market cycles.
- Sustainability-driven product development: Regulation and brand commitments are forcing rapid adoption of tethered closures, increased PCR content, and material simplification. We map the regulatory triggers and cost implications for PCR adoption and chemical-recycling equivalence, and provide go-to-market options for sustainable closure portfolios.
Key market dynamics shaping 2026 strategy
- Regulatory ripple effects: Emerging standards — from regional rules on recycled food-grade plastics to revised guidance on container-closure systems — are tightening compliance requirements. Even guidance initially focused on non-plastic substrates can create downstream testing and qualification demands for pharmaceutical closures and supplier audits.
- Raw material volatility: Sharp polyolefin price swings in early 2026 have exposed margin sensitivity for producers and converters. Companies that combine purchasing flexibility with product design that reduces resin intensity will have a near-term cost advantage.
- Consolidation and capability aggregation: Large-scale deals in 2025 accelerated vertical integration: combined portfolios unlock cross-selling and scale synergies but also concentrate exposure to single-supplier risks. The practical implication is a renewed emphasis on multi-source strategies and contingency capacity.
- Technology and differentiation: Smart closures, precision dispensing, and value-added inserts (e.g., NFC-enabled caps) are moving from proofs-of-concept into commercial lines. Those capabilities create premium differentiation for brand partners but require investments in inline automation and quality controls.
Competitive landscape: what the majors are signalling
The competitive map includes diversified global integrators, specialty closure houses, and regional champions. Key behaviors observed across leading players point to four strategic postures.
- Scale seekers and integrators: The Amcor–Berry transaction demonstrates a push to combine flexible and rigid capabilities and to capture cross-market leverage. Reported integration synergies are substantial and will shift competitive dynamics in channels where combined portfolios can be offered end-to-end.
- Capacity and regional footprint expansion: Select players are adding targeted capacity in growth corridors. Notable examples include capacity investments and new facilities designed to service beverage customers in North America and Latin America, indicating an emphasis on speed-to-market and localized supply chains.
- Specialists focused on premium functionality: Firms with strength in precision dispensing, tamper-evidence, and pharma-grade systems are doubling down on engineering-led differentiation. Investments in inline electronics for smart closures and high-precision molds validate a premium pricing pathway for performance-critical segments.
- Sustainability-first actors: Several suppliers are prioritizing PCR integration, tethered designs, and lightweighting. These moves address both regulatory pressure and brand demand for closed-loop solutions.
For each of the named companies, the full report contains structured supplier dossiers: business model positioning, capacity footprint maps, recent M&A and capex events, and an assessment of strategic fit against five buyer archetypes (global beverage CPGs, regional dairy cooperatives, pharma CDMOs, personal-care brand platforms, and industrial users).
What the full PW Consulting report contains (practical deliverables)
- Top-down market sizing and bottom-up reconciled forecasts (2020–2032) with sensitivity bands keyed to resin pricing and GDP growth.
- Interactive scenario models for utilization, pricing, and margin impact under three macro pathways (soft demand, structural growth, and accelerated circularity).
- Regulatory and standards impact matrix linking regional rules to qualification timelines and compliance costs for food, beverage, and pharmaceutical closures.
- Supplier due-diligence templates, a three-tier vendor-risk heat map, and a procurement playbook for resin sourcing and PCR contracts.
- M&A playbook: target screening criteria, valuation multipliers adapted for closure specialists, and integration checklists emphasizing operational synergies and customer retention strategies.
- Commercial growth modules: price-elasticity matrices, SKU rationalization templates, and value-based packaging innovation frameworks for brand owners.
- A curated risk register and mitigation tracker covering feedstock shocks, regulatory shifts, trade barriers, and technology displacement.
2026 strategic playbook — recommendations for executives
- Model multiple futures, then hedge selectively: Use scenario outputs to set flexible capex triggers. Move from single-point forecasts to conditional spend authority that links capital outlays to resin-price bands and order-backlog thresholds.
- Lock in multi-source PCR supply and prioritize quality verification: As recycled content mandates proliferate, procurement must secure both volume and chain-of-custody traceability. Contracts should include step-in rights and qualification clauses to protect supply continuity.
- Differentiate or specialize — don’t be “me-too”: If you lack scale to compete on price, focus on functional differentiation (dispensing accuracy, tamper evidence, smart features) or rapid-response regional service for fast-growing markets.
- Prepare for consolidation — both as buyer and defensive seller: Identify non-core assets that could be monetized and establish playbooks for integrating acquired molding shops to capture cross-sell synergies quickly.
- Operationalize sustainability into product-cost models: Calculate the true cost of PCR integration (capex, process changes, scrap rates) and model pricing pathways that allow premium capture from brand partners.
- Invest selectively in automation and inline inspection: Demand for precision and traceability will favor suppliers that can demonstrate low-quality variation and electronic batch records at scale.
Risk outlook and sensitivities
Key downside risks for 2026 include sustained high feedstock prices and a regulatory mismatch across jurisdictions that complicates cross-border product approvals. Upside risks center on accelerated substitution of glass and metal in selected beverage and consumer markets, and the rapid adoption of reusable/tethered formats that can lift per-unit realized pricing for compliant suppliers.
To support rapid decision cycles, the PW Consulting suite includes stress tests that translate +/- 10–30% resin-cost moves into EBITDA impact for typical closure-factory operating models, and a regulatory-timeline sensitivity that quantifies the value of accelerated compliance programs.
Conclusion — the strategic value of the full study
PWC’s Plastic Closure Market preview establishes the contours of a market where modest but persistent growth, regulatory pressure, and technological differentiation converge. For 2026, decision-makers need more than intuition: they require scenario-tested capex commitments, a procurement playbook for volatile resin markets, and a defensible M&A thesis. The full PW Consulting report supplies those instruments — including the granular segment and regional breakouts, interactive models, and supplier dossiers that are reserved for subscribers.
To access the complete dataset, reconciled forecasts, and the actionable playbooks that translate these insights into 2026 decisions, please consult the full research release on our website.
For detailed analysis of this topic, please visit the official page: Plastic Closure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


