



Microreactor Market to Reach USD 311.05 Million by 2032 at 18.95% CAGR — PW Consulting

Microreactor Technology Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, this briefing introduces our full Microreactor Technology Market study (base year 2025, forecast 2026–2032). It distills the report’s most consequential, decision-relevant insights for executives, investors, and policy planners preparing moves in 2026 — while intentionally withholding the granular segment tables and proprietary company share matrices that are included in the paid report. Consider this a high-fidelity trailer: rigorous, evidence-based, and focused on the strategic implications that should drive near-term planning.
Microreactor Technology Market
Why this study matters in 2026
Microreactor technology has moved from a niche R&D topic to an investable industrial platform. Our modeling shows the market accelerating from a mid‑double‑digit base in 2025 and projecting rapid expansion through 2032 at a compounded annual growth rate that reflects strong adoption across lab-to-industrial transitions. For 2026 decision cycles, the study’s strategic value is threefold:
Microreactor Technology Market
- It translates macro momentum into actionable go/no-go triggers for capex and partnerships;
- It identifies which technical, regulatory, and commercial uncertainties drive value — and which can be hedged through specific operational choices; and
- It provides competitor archetypes and capability maps that help executives prioritize M&A, JV, or supplier strategies without having to rebuild market intelligence from scratch.
Market trajectory and what it implies
Our base-year synthesis (2025) and forecast (2026–2032) quantify a clear growth path: the microreactor market has demonstrated steady expansion during 2020–2025 and is expected to accelerate throughout the forecast window. With a robust compound annual growth rate underpinning the projection, the market’s size is set to multiply several-fold by the end of the forecast period. For strategic planners, this pattern signals two concurrent imperatives:
Microreactor Technology Market
- First‑mover advantage in modular and scalable platforms. Suppliers and industrial users that standardize interfaces and offer repeatable “lab-to-plant” pathways will capture outsized value as demand scales.
- Risk management for long‑lead investments. While macrodemand is strong, project success depends on regulatory alignment, supply‑chain resilience for specialty components, and demonstrable safety/performance in early deployments.
Because the full dataset in the premium report includes year-by-year market levels, scenario analyses and sensitivity testing (including upside and downside market paths), the document equips CFOs with NPV-ready inputs and gives business development teams quantifiable criteria for partnership selection.
Regulatory and programmatic tailwinds — what changed in 2025–2026
The regulatory and funding landscape has evolved materially, and these changes are already shaping commercial timelines:
- Regulators have introduced more suitable licensing pathways tailored to simplified microreactor designs, lowering permissible barriers for demonstration projects and accelerating time-to-deployment for lower-complexity units.
- Substantial federal funding and program launches have catalyzed vendor selection and prototyping activity. Significant public programs have allocated capital and designated testbeds, creating near-term demand for demonstration systems and supply-chain validation.
- Defense and energy agencies have explicitly shortlisted vendors for installation programs, signaling procurement pipelines that may rapidly translate into purchase orders once pilots prove operational reliability.
In practice, these developments change the investment calculus: public procurement and testbed availability de‑risk first-of‑a-kind projects and shift value from pure R&D into scale‑up engineering, supply‑chain integration, and operations support services.
Competitive landscape — positioning without revealing shares
The microreactor market remains moderately fragmented, with a mix of large industrial players, specialist OEMs, precision component suppliers, and systems integrators. The companies we profile in the full study represent representative capability clusters:
- Large industrial incumbents bringing advanced-flow reactor platforms and extended supply-chain networks. These firms compete on scale, reliability, and brand trust for industrial deployments.
- Modular system providers that emphasize lab-to-industrial continuity — flexible architectures that shorten development cycles and ease scale-up risk for chemical and pharmaceutical clients.
- Lab-scale innovators and process-development specialists who dominate early-stage adoption in research and specialty chemicals. Their value proposition is speed-to-data and rapid prototyping.
- Component and microfabrication specialists supplying chips, flow-control modules, and precision valves — critical bottlenecks for reliable, repeatable microreactor operation.
Representative vendor archetypes (detailed competitive profiles are included in the full report) include:
- Companies with advanced continuous-flow reactor lines and industrial partnerships focused on high-throughput processing and long-run reliability.
- Modular European and Japanese suppliers known for lab-to-industry platforms and process-development tooling that streamline qualification cycles.
- Chip and microfabrication firms offering bespoke devices and high‑precision components that materially affect yield and scale economics.
Our competitive analysis synthesizes product roadmaps, partnership networks, and R&D positioning to create actionable scenarios: who becomes a strategic supplier for large deployments; which vendors are attractive targets for bolt-on acquisitions; and where partnership models (OEM + integrator) outperform in speed and cost efficiency.
What the report contains — operational, transaction, and policy-ready outputs
The full study is deliberately practical. Its core components include:
- Market sizing and forecast tables (annualized 2020–2032) and scenario testing that model demand by portfolio strategy;
- Go-to-market playbooks for technology vendors, end-users (chemicals, pharma, specialty materials), and EPC/engineering firms, including procurement checklists and qualification roadmaps;
- Component-supply risk maps and a supplier scorecard for critical parts (flow controllers, microfabricated chips, sensor stacks), with mitigation options for single-source exposures;
- Regulatory impact analysis that links licensing pathways and public-program schedules to realistic project timelines and cost envelopes;
- Competitor dossiers with capability matrices, partnership histories, and strategic recommendations for M&A, JVs, or distribution alliances;
- Financial templates and sensitivity models that permit rapid build-out of project-level business cases, from pilot to serial deployments.
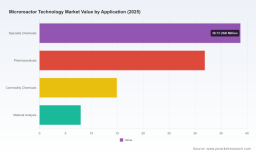
Note: This public preview intentionally omits the granular regional, application, and company share tables that are part of the paid dataset. Those elements are purposefully retained to preserve the study’s commercial and analytical rigor and are available in the subscription package.
Strategic imperatives for 2026 — a checklist
Based on the combined market projection, regulatory signals, and vendor landscape, executives should prioritize the following actions in 2026:
- Prioritize pilot projects in partnership with public testbeds or program-backed pilots. These arrangements offer validation paths and cost-sharing opportunities that materially shorten commercialization timelines.
- Lock early access to critical components through multi-year supply agreements or strategic investments in component suppliers; even modest supply-chain friction can delay rollouts and inflate unit economics.
- Segment go-to-market by use-case maturity: deploy modular lab platforms for R&D-heavy customers while aligning industrial-grade offerings with partners that can underwrite long-term operations and maintenance.
- Design regulatory engagement strategies. With licensing frameworks becoming more permissive for simplified microreactors, proactive dialogue with regulators will accelerate approvals and establish first-mover compliance advantages.
- Use staged financing tied to demonstrable milestones: tranche funding aligned with pilot completion, performance validation, and serial manufacturing readiness reduces investor downside and speeds scale deployment.
Policy and ecosystem plays
Public programs and regulatory reforms are creating a procurement-led growth mechanism. Companies that can craft proposals aligning technical specifications with public program objectives (resilience, distributed power, rapid deployment on bases or remote industrial sites) will find prioritized procurement queues and co-funding mechanisms. For investors, the implication is that public-private co-investment structures will subsidize early commercialization risk and improve portfolio IRR when tied to measurable milestones.
Limitations and invitation
This preview articulates the strategic contours of the market and highlights the tactical moves that materially influence success in 2026. It deliberately omits the granular segmentation tables (regional splits, application shares, and detailed company market-slices) to maintain analytical integrity and to encourage a direct engagement with the full study. If your team needs the full dataset — including year-by-year market figures, supplier scorecards, and downloadable financial models — PW Consulting provides secure access and tailored briefing sessions to integrate findings into investor decks, bid strategies, or R&D roadmaps.
Next steps
For executive teams preparing decisions in 2026, we recommend three immediate steps:
- Request the full report and schedule a tailored, 90‑minute executive briefing to map the study’s outputs to your investment or procurement timeline;
- Undertake a short due‑diligence sprint on targeted suppliers (use our supplier scorecard as the checklist) to validate component availability and long‑lead risks; and
- Engage with program administrators and testbed operators to secure pilot slots tied to conditional purchase options — this materially reduces commercialization uncertainty.
PW Consulting’s full Microreactor Technology Market study contains the proprietary datasets, modeling spreadsheets, and competitor dossiers needed to operationalize these recommendations. Contact our subscriptions desk to obtain access and to arrange a strategy workshop tailored to your organization’s agenda for 2026.
For detailed analysis of this topic, please visit the official page: Microreactor Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


