



PW Consulting: Liquid Dairy Market to Reach USD 508.45B by 2032 at 4.51% CAGR

Liquid Dairy Products Market — Strategic Brief for 2026 Decision-Makers
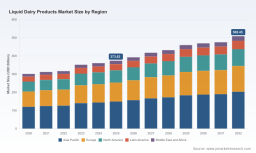
As companies position for the next cycle of growth and disruption in liquid dairy, PW Consulting’s latest market study provides a tactical compass for 2026. Built on a 2020–2025 historical lens with a 2026–2032 forecasting horizon, the analysis projects the global liquid dairy market to grow from a 2025 baseline of USD 373.63 Billion to USD 508.45 Billion by 2032, implying a compound annual growth rate (CAGR) of 4.51%. These headline numbers frame an industry that is simultaneously large, steadily expanding and materially reshaping competitive and supply dynamics — making the coming 12–18 months a critical window for strategic moves.
Liquid Dairy Products Market
Why this report matters now
-
Macro growth with micro volatility — The market’s mid-single-digit CAGR masks important volatility at raw material, channel and policy levels. Milk production upticks and regional supply swings are creating downward pressure on raw milk prices into 2026, while pockets of premiumization and functional innovation continue to expand faster than the headline.
Liquid Dairy Products Market -
Regulatory and channel inflection points — Recent policy shifts (including school nutrition law changes in the U.S. and region-specific bans aligned with EU animal-health standards) are altering institutional demand and compliance requirements for product formulation and labeling. These changes create near-term demand openings as well as compliance costs that require rapid operational alignment.
Liquid Dairy Products Market -
Competitive fragmentation = M&A and partnership runway — The market displays a moderate concentration profile: the top three and five groups do not dominate the landscape, leaving room for regional champions, private-label growth and consolidation plays that can rapidly scale supply footprint or route-to-market advantage.
What the report delivers (practical, decision-ready content)
-
Robust market sizing and forward-looking forecasting through 2032, including scenario paths sensitive to raw milk price swings, trade disruptions and demand shocks.
-
Demand-driver synthesis (demographics, urbanization, per-capita consumption trends, premiumization and functional nutrition dynamics) with prioritized growth pockets by product archetype and channel strategy.
-
Distribution channel intelligence covering modern trade, convenience, online retail and institutional channels, plus playbooks for optimizing assortment and pricing by channel.
-
Supply-side diagnostics: capacity maps, processing and packaging technology trends, cold-chain criticality and cost-to-serve modeling for key trading corridors.
-
Competitive landscaping with strategic profiles of global manufacturers, co-operatives and fast-growing regional players — including capability heatmaps, activity trackers and M&A opportunity filters.
-
Regulatory and food-safety checklist with implementation timelines and contingency plans for market access and school nutrition programs.
-
Commercial playbooks: SKU rationalization templates, promotion elasticities, private-label strategies and retailer negotiation frameworks designed for immediate deployment.
-
Operational tools: KPI dashboards, supplier scorecards and an interactive scenario model that lets executives stress-test investments under multiple price and demand assumptions.
Key strategic implications for 2026 decisions
-
Prioritize optionality in capacity and procurement. With global milk production rising and exerting downward price pressure, procurement teams should secure flexible supply contracts and hedging mechanisms while operations calibrate transient increases in throughput rather than over-committing to fixed-capex expansions.
-
Accelerate product differentiation where price competition is fiercest. Premium, functional and lactose-free lines continue to outgrow bulk white milk. R&D and branding budgets should be selectively redirected toward nutrition-led innovation and clear benefit-based positioning.
-
Invest in channel-tailored execution. The distribution mix is evolving rapidly: digital and convenience channels are creating growth and margin opportunities, while institutional channel reforms create new scale-volume buyers. Sales organizations must realign KPIs and promotions by channel to capture incremental share.
-
Make targeted portfolio and M&A plays in fragmented geographies. The market’s moderate concentration leaves acquisition runway for companies seeking scale, faster access to regional supply, or route-to-market acceleration; prioritize deals that deliver synergies in cold-chain logistics, packaging and retail relations.
-
Embed food-safety and regulatory responsiveness into launch timelines. Recent outbreaks in other dairy categories and country-level regulatory changes demonstrate how quickly consumer confidence and access can be impacted. Firms should maintain rapid response protocols and pre-cleared labeling formulations.
Competitor landscape — how the major players are shaping the market
The global field is occupied by a mixture of multinational processors, strong regional co-operatives and nimble local challengers. Below we summarize strategic positions and implications for rivals and partners.
-
Lactalis — Leveraging massive processing scale and global liquid-milk capacity, Lactalis remains the go-to partner for private-label and large-format retail programs. Their scale provides negotiating leverage on procurement and distribution but also requires targeted agility to win in premium niches.
-
Nestlé S.A. — A leader in branded dairy beverages and nutrition-oriented products. Nestlé combines strong R&D with global brand reach, making it a benchmark for functional and fortified drink launches in both mature and emerging markets.
-
Dairy Farmers of America (DFA) — As a cooperative focused on U.S. supply, DFA’s membership model delivers procurement resilience and close links to primary producers, a competitive advantage when raw-milk pricing and traceability are priority procurement criteria.
-
Danone — Strong in fresh dairy and innovative drinking yogurts, Danone is investing in regional capacity and high-value formats. Their push into manufacturing and distribution in adjacent regions is sharpening export and regional supply strategies.
-
Yili Group & Bright Dairy — Leading the charge in Asia, these companies combine domestic scale with accelerated internationalization and premium-tier launches. Their moves will be decisive in shaping liquid dairy dynamics across Asia and export corridors.
-
Arla Foods & FrieslandCampina — These European cooperatives emphasize sustainability, organic credentials and efficient distribution networks. Their investments in logistics and regional distribution centers strengthen market access across multiple channels.
-
Fonterra — As a major exporter and ingredient supplier, Fonterra’s strengths lie in global trade flows and upstream sourcing; it remains a partner of choice for manufacturers seeking consistent dairy ingredients and cream supplies.
-
Saputo, Meiji & Amul — Saputo drives North American commercial execution, Meiji sets benchmarks in premium and functional products in Asia, while Amul’s cooperative model is a reminder of the power of organized value chains in large domestic markets.
Recent industry developments underscore these strategic themes: packaging- and process-innovation capacity is being expanded by suppliers; select manufacturers are investing in regional factories and distribution centers to capture export lanes; and product launches such as lactose-free variants are accelerating to meet a more diverse consumer palette. At the same time, macro signals — rising milk production, a defined U.S. all-milk price forecast for 2026 and country-level regulatory shifts — require executives to balance growth investments with margin protection strategies.
Immediate 90-day playbook for executives
-
Run a scenario stress-test of the 2026 plan against two raw-milk pricing paths and one demand shock scenario; lock in short-term supplier options to protect margins.
-
Prioritize a SKU rationalization pilot in top-three retail partners to reduce complexity and free incremental trade funds for premium and functional SKUs.
-
Engage with packaging and processing partners on rapid prototyping — reducing time-to-market for lactose-free, fortified and single-serve innovations.
-
Set up a regulatory-watch cell focused on school nutrition, animal health policy shifts, and food-safety signals to pre-empt market access or recall risks.
How PW Consulting can accelerate your 2026 agenda
Our study is intended as both a strategic compass and a practical toolkit. Clients can license the full dataset, access our interactive forecasting model, and engage our advisory teams for tailored M&A diligence, supply-chain optimization workshops and channel-realignment programs. We also provide a rapid implementation pack that converts findings into measurable quarterly KPIs and a prioritized two-year investment roadmap.
For executives planning 2026 capital allocation, commercial reorientation or competitive defense, the intelligence in this report delivers the inputs required to choose between multiple plausible futures — without committing to a single path prematurely. The market’s size and steady growth create opportunity, but success in 2026 will hinge on flexibility, targeted differentiation and execution discipline.
To review full segment-level forecasts, proprietary channel elasticities and the underlying assumptions for scenario runs, please consult the full Liquid Dairy Products Market report on our website — the executive summary demonstrates the provenance and depth of the analysis; the full report contains the granular, transaction-grade data your team will need to operationalize decisions.
For detailed analysis of this topic, please visit the official page: Liquid Dairy Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


