



Rosin Resin Market to Reach USD 3,569.7 Million by 2032 at 4.42% CAGR | PW Consulting

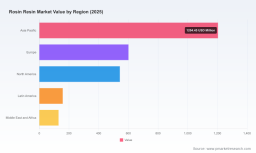
Rosin Resin Market 2026: Strategic Playbook for Decision-Makers
As companies prepare for 2026 boardroom decisions, the rosin resin market presents a mixture of steady growth, supply-side volatility and accelerating sustainability-driven demand shifts. PW Consulting’s forthcoming Rosin Resin Market study synthesizes the quantitative backbone—market sizing, trend curves and concentration metrics—with prescriptive, transaction-ready guidance that executives can put into action. This introduction highlights the report’s strategic value without disclosing the proprietary segmentation detail reserved for subscribers.
Rosin Resin Market
Market at a Glance: The Numbers That Matter to Strategy
By our base year benchmark (2025), the global rosin resin market approached the mid‑single billion dollar mark. The market is projected to grow at a compound annual growth rate (CAGR) of 4.42% across the 2026–2032 forecast window, bringing the market to the mid‑three billion dollar range by the end of the forecast. Near‑term projections indicate a modest uplift in 2026 following 2025 stability—an important signal for firms deciding whether to accelerate capacity investments or pursue acquisition opportunities.
Rosin Resin Market
Market concentration remains moderate: the leading three suppliers account for under one‑third of global revenues, and the top five firms represent less than 40% of the market. That fragmentation creates both competitive risk and strategic opportunity: established producers can defend margins through upstream integration and value‑added derivatives, while nimble challengers can capture share via regional specialization and sustainability claims.
Rosin Resin Market
Why This Report Matters for 2026 Decisions
- De‑risk capital allocation: We translate demand scenarios into cash‑flow sensitive capacity planning outputs so COO and CFO teams can evaluate brownfield expansions versus contract manufacturing and tolling options.
- Inform M&A and JV strategies: With an industry that is neither fully consolidated nor atomized, M&A remains a primary path to scale and geographic entry. Our proprietary screening narrows potential targets to those that materially improve feedstock access, technology IP or market‑channel reach.
- Operational agility against feedstock volatility: The report overlays pine resin and tall oil supply dynamics against price volatility scenarios and provides hedging playbooks for procurement heads.
- Regulatory and ESG readiness: We map the low‑VOC and bio‑based regulatory landscape across major markets and show how product reformulation roadmaps can be aligned to both compliance and premium pricing strategies.
Drivers, Constraints and Strategic Implications
- Sustainability as a structural demand driver: Rosin resins are uniquely positioned as bio‑based, low‑VOC alternatives in adhesives, coatings and specialty inks. Buyers in packaging and construction are increasingly awarding business to suppliers that can demonstrate lower lifecycle emissions and regulatory compliance—an axis that will shape procurement decisions in 2026 and beyond.
- Feedstock dynamics and regional tap‑time risks: Primary feedstocks—gum rosin from pine tapping and tall oil derivatives—have been subject to periodic supply interruptions and price swings tied to regional tapping cycles and weather‑driven yields. These upstream risks translate into input cost uncertainty for resin manufacturers; our supply‑risk matrix identifies the most exposed value chains and recommended contractual mitigations.
- Application evolution: Demand growth remains anchored in adhesives, printing inks and rubber compounding, but the rate of growth across applications is uneven. The report outlines which application segments are likely to expand, which will require formulation changes, and where value pools will concentrate—guidance that is essential for portfolio prioritization.
- Trade policy and tariffs: Recent tariff actions and reciprocal measures have introduced additional cross‑border risk for resins and related chemicals. Companies with export‑heavy models should revisit routing, duty engineering and nearshoring options in 2026 planning cycles.
Competitive Landscape: How Players Are Positioning
The rosin resin value chain includes a mix of multinational chemical firms, regionally strong specialty players and local commodity producers. Below are strategic observations on a selection of the core competitive set covered in the report.
- Eastman Chemical Company (Kingsport, Tennessee, USA): Eastman is advancing product innovation with heat‑activated rosin esters aimed at higher‑performance adhesives. Their strategy is to capture margin via differentiated chemistries and targeted application partnerships.
- Harima Chemicals Group (Japan): Harima continues to emphasize pine‑chemical expertise and eco‑oriented products for packaging and construction adhesives—aligning upstream capabilities with downstream sustainability demand.
- Arakawa Chemical Industries (Japan): Arakawa focuses on specialized tackifiers and high‑purity derivatives that serve technical adhesive and specialty chemical niches where switching costs are higher.
- Kraton Corporation (Houston, USA): Kraton leverages tall oil derivatives and bio‑based resins as part of a broader strategy to offer renewable polymer blends for sealants and rubber applications.
- DRT (Dax, France): DRT maintains a pine‑chemical integrated model, allowing it to supply both bulk resins and higher‑value derivative streams targeted at adhesives, coatings and fragrance markets.
- Regional suppliers (China, Indonesia, Brazil, Europe): A broad cohort of manufacturers—from large Chinese producers to Brazilian gum rosin specialists—continues to define local competitive dynamics, with variation in feedstock access, cost structures and compliance postures.
Recent product launches by several firms underscore a market move toward bio‑based and application‑specific formulations. These launches are not only product announcements but signal strategic bets on adhesive packaging growth and sanitary/consumer applications that prioritize heat‑activated and low‑VOC chemistry.
What the Report Contains: Actionable, Transaction‑Ready Deliverables
This study blends rigorous market modeling with practitioner tools designed for 2026 execution. Key inclusions:
- Market sizing and forecast model: Annualized market model (historical 2020–2025; forecast 2026–2032) with scenario toggles—baseline, sustainability‑led premium, and supply‑constrained downside.
- Segmentation frameworks: Detailed splits by region, resin type and application—accompanied by demand drivers, margin benchmarks and buyer archetypes (note: granular segmentation values are reserved for the full report).
- Supply chain maps and risk heatmaps: Facility‑level mapping for feedstock sourcing, refining capacity and logistics choke points—plus mitigation strategies (dual sourcing, strategic stock, tolling partnerships).
- Price and margin analytics: Input cost drivers, pass‑through scenarios and a dynamic sensitivity tool for procurement and pricing teams.
- Competitive scorecards: Comparative capability matrices, innovation profiles and M&A fit scoring for potential targets.
- Commercial playbooks: Go‑to‑market options by application (e.g., adhesives, inks, rubber), channel strategies, and contract negotiation templates that reflect current market realities.
- Regulatory and sustainability roadmap: Compliance checklists, reformulation timelines, and potential premium positioning tied to low‑VOC and bio‑based certifications.
How to Use These Insights in 2026 — A Practical Checklist
- For CEOs and Corporate Strategy teams: Use our scenario outputs to validate strategic bets—capacity expansion, M&A or divestiture—against plausible supply shocks and sustainability adoption rates.
- For CFOs and Investors: Run acquisition models with our risk‑adjusted cash‑flow assumptions and margin band expectations; prioritize targets that offer vertical integration or privileged feedstock access.
- For Heads of Procurement: Implement the procurement playbook: adopt layered contracts, evaluate tolling partnerships, and stress‑test supplier portfolios against the supply‑risk matrix.
- For R&D and Product Teams: Prioritize reformulation projects that align with low‑VOC targets and identify co‑development partners among resin suppliers with relevant esterification and hydrogenation capabilities.
- For Sales and Commercial teams: Rewire customer segmentation around value capture (sustainability‑linked premiums, performance adhesives) rather than volume alone.
Why PW Consulting’s Study Is Different
Rather than a static compilation of historical data, our study integrates a modeling engine, supplier intelligence and transaction playbooks. Clients receive both the raw datasets and the strategic narratives that translate numbers into decisions: where to invest, whom to partner with, what contracts to renegotiate, and how to position products for regulatory and commercial advantage in 2026.
Next Steps
PW Consulting has prepared a concise executive dashboard and a full data package for clients who require the granular segmentation and proprietary unit‑level models referenced here. If your strategic planning for 2026 involves capital deployment, supply‑chain redesign or portfolio reshaping in adhesives, inks, coatings or rubber compounding, the full report is the decision‑support tool you will rely on. Access to the complete dataset, supplier scorecards and scenario models is available through the PW Consulting Rosin Resin Market report portal.
For executives who want a focused briefing, PW Consulting offers tailored workshops that walk leadership teams through the scenarios most material to your P&L and balance sheet—transforming market insight into an actionable 90‑day plan.
For detailed analysis of this topic, please visit the official page: Rosin Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


