



PW Consulting: Countertop Water Flosser Market to Hit USD 970.36M by 2032 at 7.34% CAGR

Countertop Water Flosser Market — Strategic Briefing for 2026 Decision-Making
Executive teaser
As companies finalize 2026 portfolios and capital plans, the countertop water flosser market presents a clearly investable trajectory: the global market, after steady expansion from the low‑400s in 2020, reached an estimated USD 591 million in 2025 and is projected to approach roughly USD 970 million by 2032 at a compounded annual growth rate of about 7.3%. That macro momentum masks important strategic inflections — product design, channel orchestration, regulatory alignment, and competitive positioning — that will determine who captures the premium segment of growth. This briefing previews the strategic insight we deliver in our full Market Research report, highlighting how executives should think about 2026 actions while intentionally withholding detailed sub‑segment tables to encourage direct engagement with the primary research.
Countertop Water Flosser Market Research
Why this market matters for 2026 choices
-
Durable growth with defensible tails: A mid‑single‑digit-plus CAGR across the forecast window translates into a sizable incremental revenue pool — not a flash market — making investments in product innovation and distribution scale defensible for consumer health players and appliance incumbents alike.
Countertop Water Flosser Market Research -
Consolidation opportunity with room for challengers: Market concentration measures indicate a leading‑firm advantage, yet enough fragmentation remains for differentiated offerings — premium features, evidence‑backed claims, or channel exclusive models — to materially shift share.
Countertop Water Flosser Market Research -
Regulatory and clinical tailwinds: Classification of powered oral irrigators under Class I device rules, combined with long‑standing ADA acceptance for credible products, lowers regulatory friction for mainstream adoption while raising the bar for clinically supported claims.
Market dynamics — what is driving growth
-
Clinical legitimacy and professional endorsement: ADA recommendations for irrigators in specific patient cohorts (for example, orthodontic and prosthetic cases) underpin a therapy‑adjacent positioning that elevates perceived value versus commodity oral products.
-
Consumer convenience and hygiene behavior: Broader consumer acceptance of powered, water‑based interdental care is being reinforced by digital health narratives and hygiene consciousness, which disproportionately benefits countertop models that promise ergonomic performance and multi‑user convenience.
-
Materials and product safety expectations: Compliance with food‑contact and BPA‑free standards shapes supplier selection and bill‑of‑materials choices; product teams must reconcile cost pressure with regulatory‑grade plastics to avoid market access friction.
-
Channel evolution: While traditional retail remains important for demonstrations and trust, e‑commerce continues to scale unit volumes and enables direct data capture for subscription and consumables strategies.
Key market characteristics executives should note
-
Predictable upgrade cycles: Countertop devices are generally replaced on multi‑year cycles, supporting strategies that combine durable hardware with recurring consumables (tips/fluids) or service add‑ons to lift lifetime value.
-
Evidence differentiates: Products carrying ADA recognition or peer‑reviewed efficacy data command pricing premiums and easier acceptance among dental professionals; absence of such evidence constrains VoC‑driven marketing.
-
Design and ergonomics matter more than SKU count: Buyers trade up for perceived performance, easy maintenance, and quiet operation. Incremental feature innovations (water temperature control, antibacterial delivery tech, simplified tip change) win outsized attention.
-
Channel mix impacts margin and feedback loop: E‑commerce accelerates product iteration via richer customer data, but omnichannel trust-building through clinics and retail remains vital to reach older demographics and to secure professional endorsements.
Competitive landscape — strategic profiles
The market is led by household consumer health brands and appliance multinationals with differing strengths — brand equity, clinical endorsements, manufacturing scale, and channel reach. Below are concise strategic reads on core competitors that any 2026 plan must take into account.
-
Church & Dwight Co., Inc. (Waterpik brand) — Deep category ownership driven by high brand recognition and clinical validation. Waterpik’s product line combines broad price‑tier coverage with durable ADA‑backed claims, enabling both mass‑market and premium positioning. Their playbook centers on clinical credibility, retailer relationships, and steady product cadence — a defensive benchmark for any entrant.
-
Procter & Gamble (Oral‑B) — Leverages integrated oral care ecosystems, bundling powered brushes with irrigator offerings. Oral‑B’s route to market leverages cross‑category promotions and professional partnerships, positioning it strongly for customers seeking comprehensive oral regimens rather than single‑device purchases.
-
Panasonic Corporation — Focuses on technological differentiation and build quality, bringing innovations such as nanoe antibacterial water delivery to market. Panasonic’s strengths lie in appliance engineering and trusted global distribution, making it a credible challenger in premium segments where perceived technology leadership pays.
-
Dentaprobes, Inc. (HydroFloss) — A specialized player emphasizing electromagnetic drive systems and a clinical performance narrative. HydroFloss demonstrates how point‑technology leadership and a clinical messaging strategy can carve a profitable niche even against larger incumbents.
Regulatory and standards considerations
-
FDA classification as Class I (exempt from premarket notification) lowers time‑to‑market risk for conventional designs but does not obviate the need for quality systems, label accuracy, or claims substantiation.
-
Certified endorsements (for example ADA Seals) materially improve professional and consumer trust; achieving and maintaining such endorsements require sustained investment in clinical studies and compliance documentation.
-
Materials compliance (BPA‑free polycarbonate/Tritan and related food‑contact requirements) needs to be validated through upstream supplier audits; packaging and post‑market surveillance plans should be specified in contractual agreements.
Where the strategic openings are in 2026
-
Product premiumization: Introduce feature layers tied to measurable clinical outcomes (e.g., validated plaque reduction, specialized tips for orthodontic patients) to justify higher margins while protecting against commoditization.
-
Subscription and consumables lock‑in: Design tip ecosystems and maintenance consumables that are difficult to substitute; support with auto‑replenishment through direct channels to increase customer lifetime value.
-
Omnichannel demonstration strategies: Use clinical partnerships and in‑store demo arrangements to convert skeptical cohorts, while leveraging e‑commerce for repeat purchase funnels and data capture.
-
Strategic M&A and partnerships: Target bolt‑on acquisitions that add clinical IP, manufacturing capacity for advanced plastics, or distribution footholds in underserved channels; equally consider OEM partnerships to accelerate SKU breadth without heavy capex.
-
Evidence‑first marketing: Allocate budget to trials and peer‑reviewed studies early in the product lifecycle to accelerate ADA and professional acceptance, which materially reduces customer acquisition cost in clinical channels.
What the full report delivers — practical contents for 2026 planning
Our complete Market Research package is designed to be directly operational for strategy, commercial, and product teams. Highlights include:
-
Validated market sizing (historical and forecast) with scenario modeling to stress‑test investment cases.
-
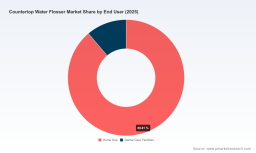
Segmentation frameworks across region, distribution channel, and end‑user with growth vectors and tactical implications (note: core split tables are available in the full report).
-
Competitive benchmarking with product mapping, pricing ladders, supply chain footprints, and go‑to‑market tactics for leading and challenger brands.
-
Distribution and retail playbooks for e‑commerce, mass retail, pharmacies, and clinical channels, including margin math and promotional cadence recommendations.
-
Regulatory pathway checklists, materials compliance templates, and recommended clinical evidence roadmaps for ADA consideration.
-
Commercial scenarios that model the impact of premiumization, consumables conversion, and channel mix shifts on EBITDA and working capital.
-
Actionable M&A target criteria and a short list of strategic assets worth pursuing in 2026 to leapfrog capability gaps.
Implications for 2026 planning cycles
Executives should treat 2026 as a year for disciplined investment rather than speculative expansion. Prioritize projects that (a) create recurring revenue, (b) secure clinical credibility, (c) reduce time to consumer trial via retail/clinic partnerships, and (d) control critical materials and manufacturing risk. Given the projected trajectory to 2032, early positioning around consumable ecosystems and professional endorsement yields outsized returns relative to incremental R&D spend.
Final note and next steps
The summary above is a strategic preview designed to inform executive discussion. For teams building 2026 budgets and three‑year roadmaps, the full Market Research report contains the granular segmentations, channel breakouts, supplier scorecards, and model workbooks necessary to convert these strategic directions into executable plans. PW Consulting’s analysts are available to present the findings to your leadership team and to run scenario modeling tailored to your portfolio. Contact our research desk to access the complete intelligence package and the underlying datasets referenced in this briefing.
For detailed analysis of this topic, please visit the official page: Countertop Water Flosser Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


