



PW Consulting: Electromechanical End Effectors Market — 12.52% CAGR to USD 4,789M by 2032

Electromechanical Robot End Effectors: A 2026 Strategic Preview for Decision-Makers
As companies plan capital allocation, product roadmaps, and M&A activity for 2026, the electromechanical robot end effectors market is an inflection point that requires a differentiated strategic response. PW Consulting’s newest market brief synthesizes multi-year market modeling, competitor moves, standards and trade dynamics, and technology trajectories to help executives convert uncertainty into actionable advantage.
Electromechanical Robot End Effectors Market
Market snapshot: scale, pace, and competitive density
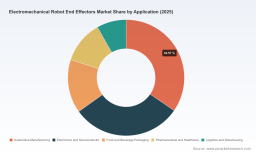
Our modeling shows the electromechanical robot end effectors market more than doubled in scale during the early 2020s, rising from roughly USD 1.15 billion in 2020 to about USD 2.10 billion in 2025. From 2026 through 2032 the market is projected to sustain robust expansion, tracking a compound annual growth rate (CAGR) of approximately 12.52% and reaching roughly USD 4.79 billion by 2032. These headline dynamics—rapid revenue growth combined with sustained technological investment—make end effectors one of the highest-leverage domains within factory automation for the coming planning cycle.
Electromechanical Robot End Effectors Market
Concentration is meaningful but not prohibitive: the top three suppliers control a sizeable portion of the market, while the top five raise that share substantially, leaving room for niche specialists and fast-follow entrants to capture value through specialization, integration, or service-led differentiation.
Electromechanical Robot End Effectors Market
Why this matters for 2026 corporate plans
- Capital deployment timing: With high double-digit CAGR and ongoing product innovation, 2026 is the window to commit to platform-level investment (e.g., modular EOAT architectures, embedded sensing and software) that will compound over the following five years.
- Go-to-market design: Buyers increasingly purchase capabilities (precision, adaptability, safety-compliance) rather than raw hardware. Suppliers that combine electromechanical hardware with integration toolkits and predictable lifecycle services will command premium margins.
- Supply-chain risk management: Raw-material normalization and tariff regimes are reconfiguring sourcing decisions—leading manufacturers must plan for component substitution, dual-sourcing critical actuators/sensors, and localized assembly to avoid duty and regulatory friction.
- Regulatory and safety compliance: Standards such as ISO/TS 15066 and evolving machinery regulation frameworks require design decisions now that will affect certification timelines and market access in 2026 and beyond.
What PW Consulting’s report delivers (practical, actionable outputs)
The full report is engineered as a toolkit for executives and product leaders. It goes beyond narrative to provide:
- Proprietary market-sizing and forecast models (historical 2020–2025, forecast 2026–2032) with scenario toggles to test price, adoption, and supply-shock assumptions.
- Capability maps and technology maturity assessments that rank electromechanical grippers, tool changers, force-torque sensing, and soft/adaptive solutions against adoption velocity and margin potential.
- A decision framework for OEMs and system integrators to prioritize investments across R&D, production capacity, and field services based on payback windows and strategic fit.
- Go-to-market playbooks—channel, pricing architecture, and partnership templates—for enterprise and SME segments (including cobot-centric models).
- M&A and alliance screening: a short-list of accretive targets by capability tier, plus valuation sensitivities under alternative growth and margin scenarios.
- Operational risk checklist: supplier concentration, critical component lead-times, tariff exposure, and certification timelines tied to common procurement contracts.
The report purposefully reserves granular segmentation tables and vendor-level revenue breakouts for subscribers; this preview outlines the strategic contours while guiding readers to the full analysis for executable numbers and target lists.
Competitive landscape — strategic postures and implications
The competitive map contains three distinct archetypes that shape how incumbents and challengers will act in 2026:
- Global platform incumbents — Large automation groups with broad portfolios that leverage modular product lines and global distribution to capture enterprise accounts. These players protect margin through scale and brand trust, and they invest in incremental product families aimed at industrial OEMs and high-volume manufacturing.
- Agile plug-and-play specialists — Vendors focused on fast integration, compatibility with multiple robot brands, and rapid deployment. They win in cobot and SME use cases by reducing integration risk and time-to-value.
- Deep-technology niches — Firms that own differentiated sensing, compliant actuation, or soft material handling IP. These companies command higher ASPs in specialized applications (delicate food handling, precision assembly) and are attractive targets for acquisition by platform players.
Representative company signals reinforce these archetypes. Established industrial suppliers continue to broaden modular electromechanical gripper and tool changer portfolios, while plug-and-play entrants focus on compatibility and ease of deployment for collaborative robots. Recent trade-show launches and product refreshes highlight an arms race in force-torque sensing accuracy and adaptive gripping payloads—two features buyers cite as decisive when replacing manual workflows.
Key external drivers you must factor into 2026 planning
- Standards-compliance as product design constraint: ISO/TS 15066 sets baseline safety expectations for collaborative systems, pushing designs toward force-limiting and predictable failure modes. Non-compliant products face market access barriers and indemnity risk.
- Regulatory certification: Regional machinery directives now demand CE marking and documented conformity pathways for end effectors sold in major markets—project timelines for certification need to be integrated into product launch calendars.
- Trade and tariff exposure: Tariff measures on certain actuator and sensor imports materially affect landed cost and supplier selection. For many firms, assembly localization or alternate sourcing in 2026 will be a necessary hedge.
- Input cost normalization: Raw-material and component price stabilization in late 2024 removed a near-term price shock but does not eliminate future volatility; dynamic procurement strategies will protect margin.
- Labor-cost arbitrage driving automation ROI: Rising manufacturing labor costs in key markets continue to compress payback periods for end effector investments, especially where pick-and-place tasks can be automated with high-repeatability electromechanical solutions.
Five strategic options for 2026 (recommendations)
- Platformize and modularize: If you are a product supplier, accelerate development of plug-and-play modules and open interfaces. Strategic APIs and integration kits reduce buyer risk and increase replacement frequency.
- Service-up the offering: Build subscription models for predictive maintenance, spare parts, and software updates. Services increase lifetime value and insulate against hardware commoditization.
- Hedge your supply chain: Identify dual sources for critical actuators and sensors, and evaluate near-shoring assembly to mitigate tariff and logistics exposure. Lock in long-lead items through strategic supplier agreements.
- Acquire capability, not just capacity: Pursue tuck-in acquisitions that add specialized sensing, compliant gripper IP, or proven system integration capability—these deals accelerate market entry with lower execution risk than greenfield R&D.
- Align compliance and go-to-market cadence: Integrate certification milestones (ISO/TS 15066, CE pathways) into your product development sprints to avoid late-stage product holds that delay revenue recognition.
Case signals from the field
Recent vendor activity demonstrates the playbook in action: several plug-and-play firms refreshed adaptive grippers and force/torque sensors to improve payload and integration ease; global industrial groups showcased new compact electric actuators aimed at smaller robot arms; and trade-show cycles are leaning toward systems that reduce application engineering time. These moves underscore two conclusions: buyers prize reduction in integration friction, and technology differentiation is migrating from raw actuation power to embedded sensing and software intelligence.
How to use the full PW Consulting report in your 2026 decision process
Treat the report as a decision support system: use our sensitivity models to stress-test strategic options (build vs. buy, localize vs. centralize), apply the capability map to rank internal R&D bets, and use the M&A screening to identify targets that fill capability gaps while preserving cultural fit. Executives should run a cross-functional planning workshop in Q1–Q2 2026 that aligns procurement, product, and corporate development around a single prioritized pathway—our template in the report reduces that workshop planning time from weeks to days.
Concluding note: a trailer that points to full leverage
The electromechanical end effector market offers outsized opportunity for firms that move early to combine robust hardware with sensing, software, and services—while carefully managing regulatory, tariff, and supply-chain exposure. This preview maps the strategic terrain and highlights where 2026 choices will create durable advantage. For companies that require the complete set of tables, vendor-level breakouts, scenario models, and the executable M&A shortlist, the full PW Consulting report provides the missing numbers and the prescriptive roadmaps you need to act decisively.
Contact PW Consulting to access the full dataset, model files, and bespoke advisory engagement options tailored to your role—whether you lead product, procurement, or corporate development. The timing of your next move matters: the market is growing quickly, and 2026 will separate winners who architect integrated solutions from followers who only respond.
For detailed analysis of this topic, please visit the official page: Electromechanical Robot End Effectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


