



PW Consulting: Phased Array Coil Market to Reach USD 1,270.79M by 2032 at 6.32% CAGR (2026–2032)

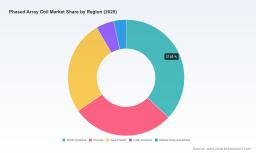
Phased Array Coil Market 2026: Strategic Intelligence for Executive Decision-Making
As healthcare providers and imaging OEMs prepare capital allocation and product roadmaps for 2026, the phased array coil market emerges as a quietly expanding but strategically pivotal segment of the MRI ecosystem. Our PW Consulting market study — based on a 2025 base year and a seven-year forecast horizon (2026–2032) — synthesizes historical performance (2020–2025), competitive dynamics, regulatory pressures, and practical go-to-market playbooks. At the macro level the market is characterized by steady expansion, underpinned by a 6.32% compound annual growth rate through the forecast period and clear evidence of accelerating monetization opportunities tied to multi-channel, flexible, and application-specific coil innovations.
Phased Array Coil Market
Why this study matters for 2026 planning
-
Capital prioritization: Imaging leaders must decide whether to invest in in-house coil development, strategic partnerships with tier-1 OEMs, or third-party manufacturing and refurbishment. Our research translates market trajectory and concentration dynamics into actionable capital allocation guardrails for CFOs and product executives.
Phased Array Coil Market -
Product roadmap focus: With increasing clinical demand for higher channel counts, flexible form factors, and specialty arrays (e.g., dual-tuned and non-proton), R&D roadmaps that prioritize signal-to-noise (SNR) gains and patient ergonomics will capture disproportionate value. The report identifies the technological inflection points most likely to deliver commercial differentiation before 2032.
Phased Array Coil Market -
Commercial strategy: The market’s competitive structure and regulatory realities change the economics of channel counts, compatibility testing, and aftermarket service. Our study clarifies which routes-to-market (OEM-certified, third-party aftermarket, contract manufacturing, or refurbished equipment models) best fit different business models.
-
Regulatory and reimbursement alignment: For 2026, companies must plan for device clearances and local reimbursement dynamics that materially affect adoption curves. The study operationalizes regulatory timelines and reimbursement levers so teams can sequence product launches and market-entry investments.
Market context — macro signals and what they imply
After a period of steady recovery and modernization between 2020 and 2025, the market is projected to extend its growth into the forecast window with a robust trajectory that supports both incumbent expansion and targeted disruption. The growth is not merely volume-driven; it reflects a qualitative shift in demand toward higher-channel, multi-purpose coil systems that enable faster acquisition, better resolution, and improved patient throughput. For executives, this implies that growth investments will need to be directed less at commodity coil production and more at sophisticated, platform-compatible offerings that address clinical productivity and differentiated imaging outcomes.
Market concentration is meaningful and persistent: leading OEMs capture a dominant share of installed-base purchases and bundled system upgrades, while a healthy aftermarket and specialized suppliers service niche clinical and research needs. This duality creates a two-track opportunity for entrants: align with OEMs to access scale, or specialize in high-value niches (e.g., pediatric, non-proton spectroscopy, and high-field research) where agility and customization matter more than volume economics.
Technology and clinical drivers — where competitive advantage will be won
-
Increasing channel density and parallel imaging: Higher element counts and advanced parallel imaging techniques continue to raise the bar for achievable resolution and scan times. Success metrics for R&D investments should therefore be measured in SNR improvement per channel and demonstrable workflow efficiency gains.
-
Form factor innovation: Flexible, ultra-light, and patient-centric designs — particularly for pediatric and claustrophobic patient populations — are moving from “nice-to-have” to differentiators in procurement decisions tied to throughput and patient satisfaction.
-
Specialty capabilities: Dual-tuned coils and non-proton arrays open new clinical and research pathways (e.g., metabolic imaging), creating premium segments where certification and compatibility with research scanners command higher margins.
-
System compatibility and software integration: The commercial success of a coil increasingly depends on seamless integration with scanner platforms and reconstruction pipelines. Co-development and validated compatibility are fast becoming prerequisites for OEM endorsement and clinical adoption.
Regulatory and reimbursement dynamics
The pathway to market remains regulated: phased array coils are typically classified under established medical device frameworks and require conformity with international safety standards (including SAR management during parallel imaging). For companies planning product introductions in 2026, timing and resource allocation for regulatory submissions (e.g., 510(k) in the U.S.) should be embedded early in the project plan.
Reimbursement environments also matter. Regions with favorable reimbursement for high-resolution MRI workflows show materially higher adoption rates of multi-channel arrays. Product and market-entry strategies that anticipate local reimbursement realities will be rewarded with faster uptake and better pricing power.
Competitive landscape — profiles and strategic implications
-
Siemens Healthineers — A platform leader that bundles high-channel arrays and flex coils with integrated MRI systems. Competitive play: innovators should evaluate OEM partnerships or differentiated feature sets (comfort, weight, or niche capabilities) that complement Siemens’ system roadmaps.
-
GE HealthCare — Offers multi-channel arrays optimized for clinical and research use. Competitive play: alignment with GE’s reconstruction and workflow priorities can accelerate adoption in high-volume clinical settings.
-
Philips — Known for SENSE-optimized coils and pediatric-focused collaborations. Competitive play: companies prioritizing ergonomic and pediatric innovations can find receptive co-development partners.
-
Canon Medical — Focuses on high-performance clinical imaging coils for Vantage systems. Competitive play: strong emphasis on clinical results creates opportunities for specialty coils that demonstrate measurable diagnostic improvements.
-
United Imaging — Rapidly scaling arrays with very high channel counts as part of integrated systems. Competitive play: market entrants should be prepared for performance benchmarking and compatibility validation across high-channel platforms.
-
RAPID Biomedical, NORAS, Magnetica, Bruker — Specialists with deep preclinical, high-field, or bespoke coil design capabilities. Competitive play: their agility in custom designs makes them ideal partners for research institutions and niche clinical needs.
-
InkSpace Imaging & ScanMed — Examples of nimble innovators and contract manufacturers/refurbishers that demonstrate the viability of aftermarket and service-led models. Competitive play: outsourcing manufacturing or leveraging refurbishment channels can be a capital-efficient scaling route.
Recent product and regulatory events (e.g., flexible pediatric arrays receiving market clearances, expanded high-channel product launches, and approvals for dual-tuned coils) validate that technological advancement continues to be matched by regulatory progress — an important signal for investment timing.
Commercial models and go-to-market playbooks
-
OEM-aligned co-development: Shortens validation cycles and eases market access at scale, but requires revenue sharing and tighter IP arrangements.
-
Third-party aftermarket and compatibility-certified products: Faster to market for focused innovations (e.g., pediatric comfort coils) but demands rigorous compatibility testing and often formal certification to be clinically acceptable.
-
Contract manufacturing and refurbishment services: Provide margins tied to volume and service quality; especially attractive for companies seeking to minimize capex while capturing aftermarket value.
-
Research-and-specialty premiumization: High-margin strategy leveraging custom, high-field, or dual-tuned coils for academic and specialty clinical centers.
Practical takeaways — what leaders should do now for 2026
-
Prioritize product investments on demonstrable SNR, workflow gains, and ergonomic improvements rather than incremental channel count increases.
-
Embed regulatory strategy and reimbursement mapping into every product launch plan to avoid go-to-market delays and to optimize pricing strategies by region.
-
Evaluate hybrid commercial models: use OEM partnerships for scale and aftermarket/refurbishing channels for margin capture and installed-base monetization.
-
Invest in validated compatibility and integration engineering to reduce adoption friction with the major scanner platforms.
-
Consider strategic M&A or partnerships to acquire niche design capabilities (e.g., dual-tuned, pediatric, or ultra-flexible arrays) that are costly to develop organically.
What the PW Consulting report delivers — practical contents you can act on
-
Demand forecasting and scenario analysis through 2032, grounded in historical trends and a 6.32% CAGR outlook to support multi-year budgeting.
-
Regulatory pathway maps and compliance checklists tailored to major markets, accelerating product approvals and market entry.
-
Competitive benchmarking with strategic recommendations for OEM alignment, third-party strategies, and manufacturing options.
-
Commercial playbooks, including pricing frameworks, reimbursement sensitivity analyses, and partnership models for scale.
-
Risk and mitigation matrices covering supply chain constraints, standards compliance (e.g., MRI safety limits), and integration risks across scanner platforms.
Our analysis is designed as a strategic “preview”: it demonstrates the depth of commercial, technical, and regulatory nuance you need to make high-confidence decisions in 2026 — while reserving the granular segmentation tables, proprietary vendor scoring, and downloadable financial models for the full report. Those elements translate insight into executable plans and are available through our detailed report package.
To convert the market’s steady expansion into a competitive advantage, leaders must move beyond generic product bets and adopt a platform-aware, regulation-savvy strategy that aligns design, certification, and commercial channels. PW Consulting’s phased array coil research decodes those choices and provides the operational roadmaps necessary for a decisive 2026.
Access the complete study for the full dataset, segmented forecasts, and our tactical implementation templates. Your 2026 program deserves intelligence that connects market growth to executable outcomes — this report is that bridge.
For detailed analysis of this topic, please visit the official page: Phased Array Coil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


